

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Airport Furniture Market: Why the 5.45% CAGR Story Unfolds Beyond Growth

Navigating the Worldwide Airport Furniture Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
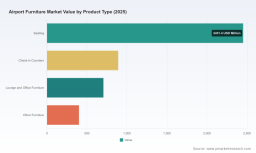
The global airport furniture market has demonstrated remarkable resilience and steady expansion over the past half-decade. Valued at approximately $3.15 billion in 2020, the market has grown consistently to reach an estimated $4.45 billion by 2025. This trajectory reflects a compound annual growth rate of 5.45 percent across the 2026-2032 forecast horizon, with projected revenues climbing toward $6.45 billion by 2032. Such sustained expansion underscores the sector's fundamental role in supporting modern aviation infrastructure and passenger experience standards.
This growth is not merely cyclical but structural, driven by long-term investments in terminal redevelopment, capacity expansion at major hubs, and the modernization of aging facilities in emerging markets. However, the path forward is not without friction. Several critical challenges are reshaping how manufacturers, suppliers, and airport operators approach furniture procurement and design. First, the intensifying focus on sustainability and green building certifications is forcing a fundamental reevaluation of material selection, manufacturing processes, and end-of-life considerations. Airports are increasingly mandated to meet stringent environmental standards, which complicates traditional procurement models that historically prioritized cost and durability over ecological impact.
Second, supply chain volatility and regulatory shifts around material sourcing are introducing new cost structures and lead time uncertainties. Recent trade policy adjustments, including tariff measures on certain upholstered and wood-based products in key markets, have altered the competitive calculus for imported furniture and pushed stakeholders to reconsider sourcing strategies. These regulatory dynamics are not static, and their prolonged uncertainty complicates long-term planning for both manufacturers and airport procurement teams. Third, the rapid evolution of passenger expectations is raising the bar for functionality and integration. Travelers now expect seamless access to power, connectivity, and flexible seating configurations that adapt to varying dwell times and crowd densities. Furniture that fails to accommodate these demands risks becoming a liability rather than a value driver in terminal design.
Together, these challenges represent a pivotal moment for the industry. Companies that continue to treat airport furniture as a purely commodity-driven category will likely find themselves squeezed by margin pressure, compliance costs, and shifting buyer preferences. Conversely, those that proactively align product development with sustainability mandates, regulatory realities, and passenger-centric design principles are positioned to capture disproportionate value as the market expands.
Key Drivers Shaping Market Dynamics
Technological Innovation and Passenger-Centric Design
The integration of technology into airport furniture has moved from a premium afterthought to a baseline expectation. High-density seating with embedded power solutions, modular configurations that adapt to fluctuating passenger flows, and integrated waste and recycling units are becoming standard specifications in new terminal builds and major renovations. The emphasis on flexibility is particularly pronounced. Airports operate in environments where passenger volumes fluctuate dramatically by hour, season, and route network changes. Furniture systems that can be reconfigured quickly without specialized labor or significant downtime offer clear operational advantages. Manufacturers that have invested in modular architectures, lightweight yet durable materials, and seamless integration of charging infrastructure are gaining favor in competitive bidding processes.
Regulatory and Sustainability Pressures
Environmental regulation and voluntary certification programs are reshaping procurement criteria across regions. Airports pursuing green building certifications are prioritizing furniture made from recycled content, sustainably sourced materials, and designs that facilitate disassembly and recycling at end-of-life. This shift is not purely ethical; it carries tangible financial implications through eligibility for incentives, alignment with operator sustainability targets, and improved public perception. At the same time, regulatory measures around material sourcing and imports are influencing cost structures. Recent tariff actions on certain upholstered furniture and wood-based products in the United States illustrate how trade policy can alter the economics of imported seating solutions. While some measures have been deferred, the underlying uncertainty encourages regional sourcing diversification and closer scrutiny of supply chain dependencies.
Airport Lighting Market
Demand-Side Shifts in Passenger Behavior and Airport Operations
Rising global air passenger volumes continue to drive demand for high-capacity, comfortable, and durable terminal furniture. Airports are not simply adding seats; they are rethinking how spaces function. Gate areas, security queues, landside arrivals, and premium lounges each present distinct usage patterns that require tailored solutions. The growing prevalence of longer layovers, expanded retail and dining footprints, and the blurring of boundaries between waiting and leisure spaces have elevated the importance of lounge and office furniture alongside traditional seating. Operators are also placing greater value on furniture that supports wayfinding, crowd management, and hygiene considerations, lessons reinforced by recent operational disruptions.
Supply Chain Evolution and Cost Structure Realignment
The post-pandemic period exposed significant vulnerabilities in global supply chains, prompting airports and manufacturers to reassess sourcing models. Lead time variability, logistics costs, and material availability have all influenced pricing dynamics. In response, many suppliers are expanding regional manufacturing footprints, investing in inventory buffering for core product lines, and developing stronger partnerships with airport operators to align production cycles with procurement timelines. These adjustments are gradually stabilizing supply but also reflect a broader trend toward resilience over pure cost minimization. For buyers, this means a shift in evaluation criteria that balances total cost of ownership, reliability, and compliance with operational schedules.
Competitive Landscape and Leading Strategies
The worldwide airport furniture market remains relatively fragmented at the top, with the largest three players accounting for less than a fifth of total revenue and the top five representing just over a quarter. This concentration suggests ample room for specialized leaders to differentiate through design, regional expertise, and integrated service offerings rather than relying purely on scale. Several manufacturers have established distinct strategic positions that illuminate the pathways to competitive advantage in this sector.
Hotel Furniture Market
Arconas has carved out a leading position in North America by emphasizing high-performance seating, power integration, and modular counter solutions that span the passenger journey from curb to gate. Its recent activity at major industry exhibitions, including the launch of new seating series designed for flexible passenger-centered spaces, signals a continued focus on adaptability and experience-driven design. AGATI, a family-owned U.S. manufacturer with deep roots in durable, custom terminal furniture, has reinforced its differentiation through thought leadership on emerging trends such as flexible layouts and high-density seating. Its emphasis on regional and international airport environments highlights the value of tailored solutions that balance durability with aesthetic coherence.
In Europe, Zoeftig leverages more than fifty years of experience to supply ergonomic chair systems and terminal furniture to a broad international airport base, with a clear focus on comfort, durability, and the ability to deliver both bespoke and off-the-shelf options. Kusch+Co, another design-driven European manufacturer, has built a substantial international footprint by prioritizing capacity, safety, and comfort across beam seating, waiting benches, and lounge soft seating. Vitra complements this landscape with a strong design orientation, offering extensive airport seating portfolios that emphasize high-quality public space design across waiting zones, gates, and lounges. Sellex adds further variety with design-oriented benches and chairs fabricated from aluminum and stainless steel, targeting both waiting and commercial terminal integration.
Beyond these established Western manufacturers, active players in Asia Pacific and China are expanding their global reach. UFL Airports provides end-to-end custom solutions for landside to airside environments with a notable presence in Asia Pacific, while Winner Furniture and Oshujian Furniture have built extensive project portfolios in public seating and airport chairs, exporting to multiple regions including the Middle East, Southeast Asia, and Europe. ModernLine Furniture and Harrows contribute specialized strengths in upholstered lounge, banquette, and soft seating solutions, reflecting the market's growing appetite for differentiated comfort and aesthetic variety.
The competitive evolution is characterized by both consolidation pressure and continued fragmentation at the specialist level. Larger players with broad geographic reach and integrated product lines are well positioned to serve multi-site airport groups and large-scale redevelopment programs. At the same time, niche manufacturers that excel in specific product categories, regional certifications, or customization capabilities retain strong value propositions for airports with unique design requirements or localized procurement preferences. Trade show activity and product launches in recent months illustrate a market where differentiation is increasingly tied to passenger experience, sustainability credentials, and the ability to deliver flexible, technology-ready configurations. New entrants and regional suppliers are likely to continue challenging incumbents in cost-sensitive segments, while established leaders defend their positions through design leadership, service integration, and long-term airport partnerships.
Future Trends and Strategic Outlook
Looking ahead to the next three to five years, several interconnected trends will define the market's direction and shape the commercial opportunities available to manufacturers, investors, and airport operators. The first is the accelerating convergence of sustainability and performance. Furniture that meets green building criteria while delivering high durability, low maintenance, and integrated functionality will increasingly become the default expectation rather than a premium option. Manufacturers that can substantiate environmental claims with transparent material sourcing, recyclable architectures, and lifecycle efficiency will gain a meaningful edge in procurement evaluations. This trend also creates opportunities for material innovation, including advanced composites, recycled metals, and responsibly sourced wood alternatives that satisfy both regulatory and aesthetic demands.
PW Consulting
The second trend is the deepening integration of passenger-facing technology into furniture systems. Seating with dependable power access, modular layouts that respond to real-time passenger flow, and designs that support digital wayfinding and connectivity will move further into the mainstream. Airports are under pressure to optimize dwell space utilization, improve passenger satisfaction scores, and accommodate diverse traveler profiles ranging from business commuters to long-haul transit passengers. Furniture that adapts to these needs without requiring extensive retrofitting will be particularly valuable in both new builds and phased terminal upgrades. This creates a clear commercial pathway for suppliers that can offer integrated solutions rather than standalone seating products.
The third trend involves the ongoing realignment of supply chains and regulatory landscapes. Trade policy uncertainty, evolving material standards, and shifting cost structures will continue to influence sourcing decisions. Airports and manufacturers alike are likely to pursue greater regional diversification, stronger inventory planning, and closer collaboration between design, production, and procurement teams. While this can introduce short-term complexity, it also rewards organizations that build flexible supply networks and maintain a clear view of regulatory developments across key markets. The commercial opportunity lies in anticipating these shifts early and positioning product portfolios to remain competitive under multiple regulatory and cost scenarios.
These trends are not without risk. Overinvestment in narrow technology features that fail to gain operational traction, misinterpretation of sustainability requirements, or exposure to sudden policy changes can erode margins and delay project wins. The most resilient players will be those that balance innovation with practical deployment, align product roadmaps with verifiable airport priorities, and maintain the agility to adapt as regulations and passenger expectations evolve.
Actionable Recommendations for Decision Makers
For manufacturers and product developers, the imperative is to embed sustainability, modularity, and technology integration into core product architectures rather than treating them as add-on features. Prioritize verifiable environmental credentials, design for disassembly and material recovery, and develop seating and lounge systems that can be reconfigured with minimal effort. Strengthening regional supply capabilities and maintaining close alignment with airport procurement cycles will reduce exposure to lead time volatility and tariff uncertainty. Differentiation through design quality, durability, and integrated power and connectivity solutions remains a proven path to commanding premium positioning in competitive bids.
For investors evaluating exposure to this sector, focus on companies with clear regional strengths, diversified product portfolios, and demonstrated ability to serve both large hub programs and specialized regional projects. Firms that combine design leadership with practical execution, possess transparent sustainability practices, and maintain flexible supply chains are better positioned to benefit from the projected growth trajectory. Monitor regulatory developments in key import markets and assess how potential policy shifts could affect cost structures and competitive dynamics across regions.
For airport procurement teams and operators, the priority is to align furniture specifications with long-term operational goals rather than short-term cost minimization. Evaluate total cost of ownership, including maintenance, reconfiguration flexibility, passenger experience impact, and compliance with sustainability targets. Engage suppliers early in the terminal planning process to ensure furniture strategies integrate seamlessly with spatial design, passenger flow management, and technology infrastructure. Building multi-phase procurement roadmaps with clear performance criteria will help balance budget constraints with the need for durable, future-ready terminal environments.
As market dynamics continue to evolve, the organizations that succeed will be those that treat airport furniture as a strategic component of the passenger experience and terminal operations, not a peripheral procurement item. Detailed segmentation data, region-specific cost structures, and tailored scenario planning can further sharpen these strategic decisions and uncover opportunities that broader market narratives may overlook. For decision makers seeking a deeper, data-backed view of the worldwide airport furniture market, the complete research report provides comprehensive breakdowns across regions, product types, materials, and competitive profiles, along with customized guidance aligned to specific business objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Airport Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com