

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
How 5G Is Redefining Copper Clad Laminate Market Dynamics Through 2032

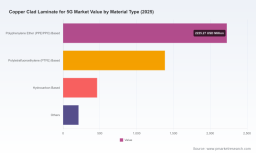
Strategic Shifts and Commercial Opportunities in the Worldwide Copper Clad Laminate for 5G Market
Market Dynamics: A Trajectory of Growth Amid Structural Pressures
The global market for copper clad laminate (CCL) tailored to 5G applications has firmly entered a phase of accelerated expansion. Valued at over 4.2 billion USD in 2025, the sector is projected to surpass 9.7 billion USD by 2032, reflecting a compound annual growth rate of 12.42 percent. This growth trajectory, sustained from a 2020 baseline near 2.48 billion USD, underscores the material's critical role in enabling high-frequency signal integrity across next-generation telecommunications and computing infrastructure. The market is no longer a niche supplier to PCB manufacturers; it has become a strategic bottleneck and enabler for the broader 5G ecosystem.
Despite the robust demand curve, the industry sits at a critical juncture defined by three interconnected challenges. First, raw material volatility is compressing margins and forcing reactive pricing strategies across the value chain. Second, geographic and supply chain concentration is creating strategic vulnerabilities, particularly as regulatory frameworks around critical minerals and processing technologies tighten. Third, the technical threshold for qualifying materials for millimeter-wave and sub-terahertz applications is rising, creating a barrier that favors entrenched players with advanced R&D pipelines while squeezing mid-tier manufacturers. The market is simultaneously expanding in volume and contracting in accessible entry points, a dynamic that will reshape competitive positioning over the next three to five years.
The structural shift is not merely about volume growth; it is about a redefinition of value capture. Historically, CCL competition revolved around cost efficiency and volume production. Today, the premium is shifting toward signal performance, thermal stability, and supply reliability. Companies that can decouple their competitive advantage from commodity resin and copper pricing will dictate the next cycle of industry consolidation. The pressure points are visible across the supply chain, from extended lead times and allocation tightening at key suppliers to material-specific price adjustments that reflect underlying chemical and textile cost inflation. These dynamics are transforming CCL procurement from a tactical purchasing function into a strategic risk management imperative.
Core Drivers Reshaping the Market Trajectory
The acceleration of 5G infrastructure deployment and the parallel densification of data center architectures form the foundational demand engine. High-frequency base stations, particularly those operating in millimeter-wave bands, require laminates with exceptionally low dielectric loss and stable thermal expansion coefficients. As telecom operators push toward network slicing, edge computing integration, and ultra-reliable low-latency communication, the performance bar for CCL materials continues to rise. This is not a linear upgrade cycle; each network generation introduces new signal integrity constraints that filter out legacy material formulations. The result is a structural pull toward advanced polymer systems that can maintain impedance control at higher switching speeds and under tighter thermal cycling.
Policy and regulatory environments are simultaneously acting as both accelerators and constraints. On one hand, national 5G rollout mandates, spectrum auctions, and industrial digitalization subsidies are injecting sustained capital into base station deployment and enterprise network upgrades. On the other hand, tightening export controls and critical material governance are reshaping procurement strategies. Regulatory actions on medium and heavy rare earth elements, alongside restrictions on related processing equipment and technologies, illustrate a broader shift toward material sovereignty. For CCL manufacturers and downstream system integrators, this means that supply continuity can no longer be assumed on globalized sourcing models alone. Strategic inventory positioning, regional qualification pathways, and multi-sourcing frameworks are becoming standard practice for operators seeking to insulate their roadmaps from policy-driven disruptions.
Worldwide High Frequency Hydrocarbon Copper Clad Laminate Market
Demand-side behavior is evolving beyond telecom infrastructure into adjacent high-growth verticals. Automotive electronics leveraging cellular vehicle-to-everything communication, high-performance computing clusters, and advanced packaging for data centers are all placing new requirements on CCL performance envelopes. The convergence of these applications creates cross-industry pull for materials that can serve both RF front-end and high-speed digital routing without compromising reliability. At the same time, supply chain and cost structures are undergoing a visible recalibration. Price adjustments across key raw material categories, including copper foil, glass fiber cloth, and epoxy-based systems, are pressuring cost models and prompting suppliers to rebalance capacity allocation. Recent material-specific price actions and extended lead times reflect a broader trend where availability and specification fidelity are increasingly valued over spot pricing.
Technological innovation continues to act as the differentiator that converts raw demand into sustainable market share. The pace of speed milestones in server and network equipment is forcing material scientists to push transmission loss lower while maintaining manufacturability. New material series targeting operation above 112 Gbps illustrate how performance breakdowns are being re-engineered at the resin, filler, and foil interface. These advances are not isolated product launches; they represent a structural shift toward materials engineered for co-design with high-speed SerDes channels, advanced packaging substrates, and phased-array antenna architectures. The companies that integrate material development with system-level simulation and qualification support will capture the highest-margin segments of the market.
Competitive Landscape and Strategic Positioning
The competitive field is characterized by a mix of established regional specialists and global technology leaders, with concentration metrics indicating that a limited number of players control a significant share of high-value output. The market structure favors companies that can combine scale with application-specific engineering, particularly in high-frequency, low-loss, and halogen-free formulations. The competitive edge is increasingly defined by three dimensions: material performance consistency, supply resilience, and ecosystem partnership depth.
Several firms have carved out clear strategic positioning. Japanese and Taiwanese technology leaders are emphasizing ultra-low transmission loss portfolios and multi-series platforms designed for mmWave antennas, high-speed network equipment, and advanced interconnect solutions. Their differentiation rests on long-standing resin chemistry expertise, extensive qualification track records, and the ability to co-develop materials alongside equipment OEMs. Chinese manufacturers, meanwhile, are executing aggressive capacity expansion to capture volume growth in 5G infrastructure and data center applications, leveraging localized supply chains and rapid scale-up capabilities. North American and European players are focusing on high-reliability segments where performance validation, regulatory compliance, and long-cycle procurement relationships create durable moats.
Recent corporate actions signal where strategic emphasis is intensifying. One major Japanese supplier introduced a new series of ultra-low transmission loss CCL materials within its flagship brand, explicitly targeting next-generation servers and network equipment operating above 112 Gbps. This move reinforces a performance-led strategy aimed at the premium segment where switching speed and signal integrity justify higher price points. In parallel, a leading Chinese producer announced construction of a dedicated facility for high-frequency and high-speed CCL, reflecting a deliberate push to secure capacity for 5G and data center demand. These developments illustrate a dual-track evolution: performance differentiation at the top end and capacity-led scale at the volume end.
The market is also showing signs of both consolidation and fragmentation, depending on the segment. High-performance, low-loss materials are trending toward concentration as qualification cycles lengthen and system designers prefer fewer, deeply integrated suppliers. Volume-oriented segments, by contrast, remain more competitive, with regional players competing on cost, delivery reliability, and localized technical support. New entrants face a steep curve because performance validation, copper foil and glass fiber sourcing relationships, and long-term procurement commitments create high switching costs. The practical implication for incumbents is that strategic advantage will come from locking in system-level partnerships, controlling critical input availability, and maintaining a pipeline of materials that anticipate the next speed and frequency thresholds.
PW Consulting
Forward Outlook: Trends Defining the Next Three to Five Years
The market's next phase will be shaped by the intersection of performance escalation, supply recalibration, and application convergence. Three trends stand out as particularly consequential.
First, ultra-low loss and multi-functional material platforms will become the default expectation for flagship 5G and edge infrastructure, not a premium differentiator. As base station architectures grow denser and parallel signaling speeds climb, materials that previously satisfied mid-tier requirements will be phased out of high-value designs. The commercial opportunity lies in offering application-matched grades that balance loss performance, thermal robustness, and manufacturability, rather than pursuing a single highest-specification product for every use case.
Second, supply chain resilience will be priced into procurement decisions. Extended lead times, allocation tightening, and input cost adjustments are shifting buyer priorities toward predictable availability and qualified secondary sources. Manufacturers that can demonstrate stable input sourcing, transparent capacity planning, and regional qualification support will command preference in constrained environments. This trend creates opportunities for suppliers that invest in vertical coordination, buffer strategies for critical inputs, and clear communication around allocation frameworks.
Third, cross-vertical material convergence will accelerate. The same underlying material science advances that serve 5G base stations are increasingly applicable to automotive connectivity, high-performance computing, and advanced packaging. Companies that can reposition material families across these applications, with appropriate qualification pathways and technical documentation, will unlock broader revenue pools and reduce cyclical dependency on any single end market. The risk is that rapid application expansion can strain qualification resources and blur focus if not managed with disciplined product segmentation.
Underlying these trends are uncertainties that demand scenario planning. Raw material cost trajectories, regulatory shifts affecting critical inputs, and the pace of next-generation speed adoption can each alter the timing and magnitude of demand realization. Overreliance on a single input category or a single application vertical amplifies exposure. The companies that navigate this period effectively will be those that treat material strategy as a dynamic system rather than a static product roadmap.
Actionable Guidance for Decision-Makers
For CCL and advanced materials manufacturers, the priority is to align capacity investments with performance-tier demand rather than pursuing undifferentiated volume. This means prioritizing ultra-low loss and application-specific formulations where qualification depth and co-development capabilities create pricing power, while simultaneously securing input availability for higher-volume grades through coordinated sourcing and transparent allocation practices.
For investors, the value creation map is shifting toward firms with credible pipelines in high-frequency, low-loss materials, strong technical support ecosystems, and resilient input strategies. Due diligence should focus on qualification momentum with system OEMs, the ability to sustain performance consistency across batches, and exposure to adjacent demand pools such as data center interconnects and automotive connectivity. Capacity expansion alone is insufficient without a clear path to differentiated performance and reliable delivery.
For procurement and engineering leaders, the practical move is to treat CCL selection as a multi-year strategic decision rather than a transactional purchase. Building dual-source qualification, aligning material specifications with anticipated speed and frequency roadmaps, and incorporating supply resilience criteria into vendor evaluations will reduce later-stage redesign risk and production disruption. Early engagement with suppliers on next-generation material grades can also accelerate qualification timelines and protect program schedules.
Strategic clarity in this market requires access to detailed segmentation insights, company-specific positioning data, and forward-looking scenario analysis that connect material performance trends with end-market demand cycles. Readers seeking deeper segmentation breakdowns, regional demand patterns, and customized strategic recommendations can explore the full PW Consulting research suite for structured data and tailored advisory support.
Copper Clad Laminate Market
For detailed analysis of this topic, please visit the official page: Worldwide Copper Clad Laminate for 5G Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com