

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
6.85% CAGR and $263M by 2032: The Low Energy Electron Gun Market's Key Growth Drivers Unpacked

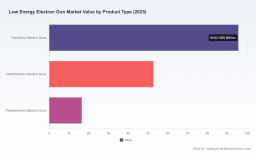
Strategic Trends and Commercial Opportunities in the Global Low Energy Electron Gun Market
Market Status and Core Challenges
The worldwide low energy electron gun market has reached a mature inflection point, with global revenues climbing from approximately 144.5 million in 2023 to 164.88 million in 2025. Projections indicate steady expansion through 2032, with annual revenues expected to reach 263.03 million, translating to a compound annual growth rate of 6.85 percent across the 2026 to 2032 forecast horizon. This trajectory reflects a market that has moved beyond experimental validation and into routine deployment across high-value scientific and industrial workflows. Rather than chasing rapid, speculative growth, the sector is consolidating around applications where controlled, low-kinetic-energy electron beams deliver irreplaceable analytical precision and process reliability.
Neutron Generators Market
Despite this constructive backdrop, three structural challenges are reshaping how manufacturers and end-users approach procurement, product design, and operational deployment.
The first challenge centers on performance uniformity and standardization. Low energy electron guns serve as critical components in surface science instrumentation, semiconductor metrology platforms, and nanotechnology research setups, where even minor deviations in beam energy, spot size, or current stability can compromise measurement integrity. The industry relies on specialized calibration protocols that define uncertainty thresholds for kinetic energy scales, yet interoperability across vendor systems, aging infrastructure, and cross-platform data comparability remain persistent friction points. As research laboratories and advanced manufacturing lines increasingly integrate multi-instrument workflows, the absence of universally adopted performance baselines introduces procurement complexity and raises validation costs.
The second challenge involves regulatory compliance and operational licensing. Operating low energy electron beam systems often triggers jurisdictional radiation control requirements, ranging from import and installation approvals to ongoing compliance documentation. In certain regions, self-shielded systems demand explicit licensing, CE certification with documented risk analysis, and adherence to radiation protection frameworks. North American markets similarly require equipment suppliers and end-users to register with state or provincial radiation control authorities. These obligations extend time-to-deployment, elevate total cost of ownership, and create uneven competitive conditions for manufacturers that must navigate divergent regional frameworks while maintaining consistent product architectures.
The third challenge relates to cathode material constraints and vacuum compatibility requirements. Low energy electron guns depend on cathode formulations such as barium oxide, yttria-coated iridium, tantalum, and lanthanum hexaboride, each selected for specific emission characteristics and operating environments. Performance envelopes vary widely depending on vacuum levels, thermal management, and application duty cycles. As demand grows for higher current density, longer cathode life, and broader vacuum compatibility, suppliers face trade-offs between material cost, manufacturing precision, and field reliability. This dynamic is especially pronounced among smaller research buyers and emerging nanotechnology users, where procurement teams must balance specification requirements against budget limitations and long-term maintenance expectations.
Key Drivers of Market Change
A clear set of reinforcing drivers explains why the low energy electron gun market continues to expand at a resilient pace, even amid the challenges outlined above. The growth is not accidental; it emerges from converging shifts in technology capability, policy expectations, demand-side behavior, and manufacturing economics.
Technological innovation and source-design breakthroughs form the most immediate driver. The market increasingly rewards electron gun architectures that deliver tighter beam focusing, more stable low-energy operation, and flexible cathode configurations. Recent product catalog expansions reflect this direction, with suppliers introducing cathode options and system documentation that explicitly address low energy performance parameters, matching power supplies, and ultra-high-vacuum compatibility. These developments matter because analytical and deposition workflows are becoming more demanding. Surface science applications require reliable operation at low retarding energies, semiconductor metrology depends on repeatable beam characteristics for defect inspection and process control, and nanotechnology research increasingly integrates low-energy sources into multi-modal characterization platforms. Manufacturers that can offer configurable systems—spanning thermionic, field emission, and photoemission principles—capture broader demand while maintaining technical credibility in specialized end-use sectors.
Policy and regulatory evolution is another powerful driver, though its impact operates through compliance burden rather than direct demand stimulation. Radiation protection rules, import and installation licensing structures, and standardized calibration expectations shape purchasing decisions and product roadmaps. Standardization frameworks for kinetic energy calibration, sterilization process requirements, and regional registration obligations create a compliance landscape that favors vendors with mature documentation practices, traceable calibration support, and strong application engineering teams. In practical terms, this shifts buying preference away from lowest-unit-cost offerings and toward suppliers that can reduce integration risk, simplify regulatory navigation, and provide defensible performance validation. The result is a market where technical support and compliance readiness are becoming core differentiators alongside hardware specifications.
Demand-side changes are equally significant. Research institutions, advanced materials companies, and semiconductor manufacturers are steadily increasing their reliance on low-energy electron beam tools for surface analysis, thin-film characterization, and precision metrology. Rather than treating these instruments as occasional-use equipment, many organizations now embed them into recurring analytical workflows, which improves utilization rates and justifies higher specification thresholds. At the same time, imaging and industrial processing applications continue to adopt low energy beam configurations for specialized tasks that benefit from controlled deposition, charge neutralization, and localized treatment. This broadening use pattern reduces dependence on any single vertical and encourages modular system design, custom engineering, and application-specific tuning.
Supply chain and cost structure dynamics complete the picture. Electron gun components remain closely tied to specialized cathode materials, precision machining, vacuum-compatible assembly, and high-performance power supply integration. Recent pricing adjustments in product lines and related vacuum components highlight how material cost movements, component availability, and fabrication complexity influence end-market pricing. For buyers, this translates into greater sensitivity to total lifecycle cost rather than initial purchase price alone. For manufacturers, it reinforces the value of stable cathode sourcing strategies, improved yield in brazing and assembly processes, and inventory planning that accounts for long lead times on critical subcomponents. Companies that manage these cost levers effectively can preserve margin while remaining competitive in specification-driven procurement.
Competitive Landscape and Leading Strategies
The competitive environment in the low energy electron gun market is defined by a mix of specialized system providers, established instrument manufacturers, and application-focused suppliers. Market concentration remains moderate, with the top three firms accounting for roughly 48.5 percent of sector revenues and the top five approaching 62.2 percent. This structure indicates a landscape where incumbents hold meaningful share but differentiation is still achievable through product flexibility, application coverage, and compliance readiness.
Leading players have carved out distinct strategic positions. Several U.S.-based manufacturers emphasize configurable electron gun systems with broad operating ranges, multiple cathode options, and custom project support for surface science and vacuum applications. Their approach centers on modular flexibility, enabling buyers to match source characteristics to specific experimental requirements while maintaining ultra-high-vacuum compatibility. In parallel, European suppliers have built reputations around comprehensive electron source portfolios spanning low-, medium-, and high-energy categories, with strong emphasis on beam control features such as blanking, pulsing, computer control, and integration into analytical workflows like Auger electron spectroscopy and electron light scattering. This breadth allows them to serve both research and industrial customers who require more than a single-purpose source.
Other participants position around manufacturing precision and component-level expertise. One U.S. company focuses on electron gun assemblies and cathodes for vacuum technology, lithography, and accelerator contexts, offering both standard and custom models with high current density emitters. Another emphasizes high-precision brazed components and replacement units for linear accelerator applications, with engineering capabilities that extend into lower-energy configurations where accelerator platforms intersect with specialized beam needs. A separate group of suppliers targets surface analysis instrumentation directly, providing compact electron guns and sources optimized for low-energy retarding modes and techniques such as LEED and RHEED. These companies compete by aligning product form factors with the practical constraints of laboratory space, integration complexity, and instrument-level performance.
Broader instrumentation and electron optics expertise also shape the competitive field. Japanese manufacturers bring established know-how in electron beam sources for industrial deposition and electron optics for microscopy and lithography systems, which creates natural adjacency to low-energy beam applications. Large multinational scientific instrumentation providers contribute through high-resolution imaging and materials analysis platforms that incorporate low-energy electron gun capabilities, leveraging scale, service networks, and software integration to support demanding laboratory environments. Together, these players illustrate how the market rewards both specialization and ecosystem breadth.
Recent developments reinforce the ways in which incumbents defend and extend their positions. Price adjustments in electron gun products and related vacuum components signal how suppliers are managing cost pressures while preserving value positioning. Product catalog updates and new cathode compatibility expansions demonstrate continued attention to material options and specification clarity, which matters in a market where matching the source to the application is often more important than the hardware brand alone. Documentation updates that consolidate low energy system details further indicate an industry-wide emphasis on reducing specification ambiguity and shortening customer evaluation cycles.
PW Consulting
Looking across these dynamics, two competitive trends are becoming clearer. First, differentiation is shifting from pure hardware specification toward application reliability, calibration support, and regulatory readiness. Second, the market is simultaneously consolidating around established players with broad portfolios and fragmenting at the application level, where custom engineering and niche cathode or source configurations create room for focused specialists. New entrants that can deliver credible performance, clean documentation, and strong integration support may find opportunities in underserved applications, but they will need to navigate stringent compliance expectations and a buyer base that increasingly prioritizes validated results over incremental cost savings.
Future Trends and Commercial Opportunities
Over the next three to five years, the low energy electron gun market is likely to be shaped by three interconnected trends, each of which carries distinct commercial implications. The first trend is specification convergence around tighter energy control, improved source longevity, and clearer calibration alignment. As analytical and metrology workflows become more standardized across laboratories and production environments, buyers will increasingly prioritize sources that reduce measurement uncertainty and simplify cross-instrument comparability. Commercial opportunity lies in vendors that can provide traceable calibration support, robust documentation, and system configurations that integrate smoothly with existing instrumentation while maintaining consistent low-energy performance.
The second trend is the growing reliance on application-tailored configurations rather than one-size-fits-all products. Surface science, semiconductor metrology, nanotechnology research, and specialized imaging applications each impose different beam requirements, vacuum conditions, and duty cycles. This reduces the effectiveness of generic hardware offerings and increases the value of modular design, multiple cathode options, and rapid custom engineering. In this environment, suppliers that can shorten configuration cycles, provide clear application guidance, and maintain reliable delivery timelines are well positioned to capture high-value projects and recurring instrument-level demand.
The third trend is the continued elevation of compliance and integration risk as purchasing criteria. Regional licensing, radiation control registration, and certification requirements are not disappearing; they are becoming embedded into procurement due diligence. Buyers will favor suppliers that reduce deployment friction through clear documentation, validated safety and risk analysis practices, and dependable service support. Commercial opportunity will flow to organizations that treat compliance as part of the product experience rather than an afterthought. At the same time, this trend introduces risk: companies that depend on a narrow set of cathode materials or specialized subcomponents may face margin pressure if supply conditions tighten or if regulatory expectations become more stringent across multiple jurisdictions.
Strategic Recommendations for Decision-Makers
For manufacturers and system developers, the priority is to treat low energy electron gun offerings as application solutions rather than standalone components. This means investing in cathode option breadth, power supply integration, and documentation that reduces ambiguity for buyers evaluating low energy performance. Equally important is building compliance-ready product narratives that help customers navigate licensing, registration, and calibration expectations without adding procurement friction. Companies that can combine specification flexibility with reliable delivery and strong support will capture more project work and improve reuse of engineering assets across applications.
For investors, the most attractive signals are recurring demand in surface analysis and semiconductor metrology, increasing utilization of low energy beam tools in multi-instrument workflows, and value migration toward suppliers that reduce compliance and integration risk. Capital allocation should favor organizations with stable cathode and vacuum-compatible component strategies, credible calibration and documentation practices, and portfolios that can serve both research and industrial buyers. Exposure to single-application or single-material dependencies deserves closer scrutiny, especially where pricing pressure and supply variability could compress margins.
For procurement and technical buyers, the strategic question is less about finding the lowest initial cost and more about minimizing total deployment risk. Evaluation criteria should include cathode compatibility with intended vacuum conditions, beam stability at low energies, calibration support, and the supplier’s ability to provide clear regulatory and integration guidance. Where applications are specialized, the ability to configure or customize source and power supply pairing can matter more than brand familiarity. Buyers that structure evaluation around operational reliability, documentation clarity, and long-term serviceability are better positioned to avoid costly rework and delayed deployment.
E Beam Accelerators Market
As the market continues its steady expansion, the most valuable intelligence is the kind that connects market sizing, application demand, competitive positioning, and compliance dynamics into a decision-ready view. Access to the full research report provides more granular segmentation data, detailed company comparisons, and customized guidance tailored to specific commercial objectives, making it a practical next step for teams seeking to act on the trends outlined here.
For detailed analysis of this topic, please visit the official page: Worldwide Low Energy Electron Gun Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com