

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Anti-Emetic Drug Market: Why 4.85% CAGR Growth Redefines Oncology Demand

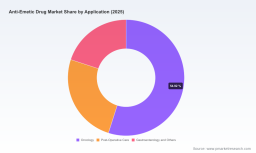
Beyond Nausea Control: Strategic Shifts in the Global Anti-Emetic Drug Market
Market Landscape: Size, Growth, and Structural Challenges
The global anti-emetic drug market has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately 3,314 million in 2020 to an estimated 4,200 million in 2025. This trajectory reflects a compound annual growth rate of 4.85 percent across the historical period, with projections indicating the market will reach 5,850 million by 2032. The growth is not merely a function of population aging or increased healthcare access; it is driven by deeper clinical integration of anti-emetic protocols into oncology, surgical care, and chronic gastrointestinal management. Revenue streams have become increasingly tied to standardized prophylaxis regimens, particularly in highly emetogenic chemotherapy settings where treatment adherence and patient quality of life directly influence clinical outcomes.
Despite the upward trajectory, the industry is navigating three structural inflection points that will define competitive positioning over the next cycle. The first is the tension between volume expansion and margin compression. As foundational molecules lose intellectual property protection, pricing pressure intensifies across mature therapeutic classes, forcing manufacturers to balance high-volume generic distribution with targeted branded innovation. The second challenge lies in regulatory complexity layered onto clinical deployment. Risk evaluation and mitigation strategies now accompany certain active ingredients, requiring healthcare providers to manage administrative compliance alongside dosing protocols. This adds friction to formulary adoption, particularly in institutions where pharmacy and therapeutics committees prioritize streamlined procurement pathways. The third inflection point is supply chain volatility. Recent intermittent shortages of widely used anti-emetics highlighted the fragility of concentrated manufacturing bases and the downstream impact on hospital scheduling, outpatient clinics, and community oncology practices. The resolution of these disruptions required coordinated production scaling, but the episode underscored how quickly formulary substitutions and therapeutic alternatives become necessary when inventory gaps emerge.
For decision-makers, these dynamics signal a market that is growing but structurally maturing. Expansion will increasingly come from optimized clinical pathways, formulation innovation, and strategic pricing architectures rather than from broad-based volume growth alone. Companies that treat anti-emetics as commoditized supportive care products risk being squeezed by margin erosion and formulary displacement. Those that align product architecture with real-world administration constraints, procurement cycles, and reimbursement mechanics are better positioned to capture sustained share.
Strategic Drivers Reshaping Demand, Innovation, and Commercial Architecture
Several interlocking forces are accelerating change in how anti-emetic therapies are developed, priced, prescribed, and distributed. The most visible driver is clinical innovation centered on receptor-targeted combinations and extended-delivery formulations. Fixed-dose pairing of neurokinin-1 and serotonin antagonists has gained traction for chemotherapy-induced nausea and vomiting prophylaxis, while prolonged-release injectable formats address gaps in dosing adherence for highly emetogenic regimens. Pediatric-specific formulation work has also progressed, reflecting the recognition that supportive care protocols cannot simply scale down adult dosing without pharmacokinetic and tolerability calibration. These clinical refinements create differentiation beyond active ingredient competition and support premium positioning where efficacy, convenience, and regimen simplification resonate with oncologists and surgical teams.
Anti-tumor Drug Market
Regulatory and reimbursement architecture forms the second major driver. Policy requirements around safety monitoring, adverse event reporting, and restricted-distribution frameworks influence both market access and operational burden. At the same time, pricing benchmarks tied to average sales prices and wholesale acquisition cost structures place downward pressure on mature molecules, while creating transparency that payers and hospital procurement teams increasingly use in formulary negotiations. The effect is a bifurcated commercial environment: older therapeutic classes face aggressive generic substitution and price erosion, while newer or combination formulations rely on clinical differentiation and service-oriented adoption support to maintain value.
Demand-side behavior is evolving in parallel. Oncology centers, surgical suites, and gastroenterology practices are placing greater emphasis on proactive nausea control as a determinant of treatment continuity, early hospital discharge, and patient satisfaction. This shifts procurement logic from unit-price evaluation toward total episode cost and adherence outcomes. Buyers are increasingly comparing regimens based on administration frequency, rescue medication utilization, and compatibility with existing chemotherapy protocols. The clinical conversation has moved beyond whether to prevent nausea to how to minimize downstream interruptions in therapy, which favors products and service models that integrate smoothly into high-throughput care settings.
Supply chain and cost structure dynamics complete the driver set. Manufacturing concentration, active pharmaceutical ingredient availability, and regional production capacity influence market resilience. When global supply disruptions occur, the response depends on the speed at which multiple producers can scale output and on regulatory mechanisms that identify and prioritize shortage resolution. Cost structures are also being reshaped by geographic diversification of generic manufacturing and shifting procurement strategies that blend volume commitments with contingency sourcing. These factors matter because anti-emetic procurement often operates as a predictable recurring expense for healthcare systems, and any break in continuity can cascade into operational friction and therapeutic substitution costs.
Taken together, these drivers suggest that competitive advantage will increasingly belong to organizations that can connect clinical innovation with market access discipline. The winning playbook involves formulation differentiation, proactive regulatory engagement, procurement-aligned pricing, and supply resilience that reduces exposure to intermittent shortages.
Competitive Positioning and the Evolution of Market Structure
The competitive field in the anti-emetic market spans multinational innovation leaders, established branded franchises, and broad generic portfolios. Companies with NK1 receptor antagonist platforms have built commercial strength around chemotherapy-induced nausea and vomiting prevention, often leveraging label expansion to cover additional emetogenic regimens and patient populations. Meanwhile, the most widely deployed 5-HT3 antagonist portfolios have long served as foundational options in post-operative and oncology settings, supported by extensive clinical familiarity and broad distribution networks. Several Swiss and U.S. players maintain positions through fixed-dose combinations or extended-release variants, aiming to improve adherence and reduce dosing complexity. Other participants compete through high-volume generic manufacturing of ondansetron, granisetron, and related molecules, emphasizing affordability, formulary breadth, and supply availability across multiple markets.
Strategic differentiation among leading firms is increasingly defined by portfolio architecture rather than single-molecule dominance. Branded leaders tend to invest in clinical evidence generation, regimen-specific label positioning, and targeted patient population expansion, including pediatric and specialty oncology cohorts. Generic-focused participants differentiate through manufacturing scale, pricing agility, and multi-market distribution, making them essential partners for hospital systems seeking cost control and continuity of supply. Combination and extended-release offerings create a middle ground, allowing developers to compete on convenience and prophylaxis durability rather than raw molecule novelty alone. The commercial result is a layered competitive landscape where brand-level differentiation, generic substitution, and formulation innovation coexist in the same therapeutic category.
Market structure is evolving along several clear trends. Patent expirations in widely used older molecules continue to open the door to generic entrants, compressing pricing and shifting revenue composition toward volume-driven sales in mature segments. At the same time, targeted approvals and label updates in specialized indications preserve room for premium positioning where clinical need and regimen complexity justify differentiation. Recent milestones illustrate this pattern: regulatory approvals for pediatric formulations broaden addressable populations in supportive care, positive late-stage trial readouts for new NK1 candidates sustain the innovation pipeline, and label expansions widen the clinical footprint of established branded assets. Conversely, generic launches following patent expiry in combination formulations demonstrate how quickly value can shift once exclusivity ends.
The market is also showing signs of pragmatic consolidation and specialization. Large diversified pharmaceutical companies maintain anti-emetics as part of broader oncology and supportive care portfolios, using cross-portfolio integration to strengthen formulary positioning and sales coverage. Specialist and mid-sized players often concentrate on niche value propositions, such as extended-release delivery or specific prophylaxis combinations, where focused clinical messaging can outweigh scale advantages. At the same time, generics manufacturers continue to expand capacity and global distribution, reinforcing their role as the structural backbone of accessible supportive care.
For executives evaluating this landscape, the key insight is that competitive success is no longer determined by molecule ownership alone. It depends on the ability to align therapeutic positioning with procurement realities, manage regulatory and reimbursement constraints, and maintain reliable supply in a category where continuity directly affects clinical workflows. Differentiation will increasingly come from formulation design, evidence packaging, access strategy, and supply reliability rather than from a single winner-takes-all asset.
Outlook: The Next Wave of Growth, Disruption, and Commercial Opportunity
Looking toward the 2026 to 2032 horizon, three developments are likely to shape market direction. The first is a continued shift from reactive symptom management toward standardized prophylactic regimens embedded in chemotherapy and surgical pathways. As clinical teams prioritize reducing treatment interruptions and improving patient experience, demand should remain concentrated around molecules and combinations that deliver durable control with manageable administration burden. This creates commercial opportunity for products and protocols that can demonstrate real-world adherence benefits and lower downstream rescue medication use, especially in high-emetogenic settings.
Nausea and Vomiting Treatment Market
The second trend is the ongoing repricing of mature categories alongside selective premium positioning in differentiated segments. Generics will remain the price anchors across broad anti-emetic use, but combination therapies, extended-release formats, and indication-specific formulations will continue to support value capture where clinical justification and formulary alignment exist. The commercial implication is that pricing strategy must be segmented carefully: volume and cost efficiency will drive generic share, while evidence, convenience, and access support will determine premium adoption. Procurement teams will increasingly evaluate these segments through total-cost lenses rather than unit price alone.
The third trend is greater emphasis on supply resilience and formulation diversification. Intermittent shortages have demonstrated that even well-established molecules can face availability constraints when manufacturing, demand surges, or regulatory actions intersect. This encourages broader sourcing strategies, dual-supplier arrangements, and regional production planning among healthcare systems and distributors. For manufacturers, it creates a strategic premium for operational reliability and for participants who can demonstrate consistent capacity, transparency, and responsiveness during demand volatility.
These trends carry both opportunity and uncertainty. Growth prospects are supported by expanding oncology volumes, surgical caseloads, and supportive care standardization, but they are tempered by persistent margin pressure in generic-heavy segments and evolving regulatory and reimbursement expectations. Companies that can combine clinical differentiation with procurement-aware pricing and robust supply planning are best placed to navigate this environment. Those relying solely on volume without access strategy may find share growth offset by pricing erosion and substitution pressure.
Decision-Maker Playbook: Positioning for Value in a Maturing Category
For manufacturers and brand leaders, the priority is to reinforce differentiation where it translates into formulary preference and clinical adoption. That means investing in regimen-specific evidence, expanding indications and population coverage where clinically defensible, and designing access strategies that reflect average pricing benchmarks and procurement cycles. Formulation innovation that reduces administration burden or improves adherence should be framed in practical care-pathway terms rather than as isolated product features. Supply continuity planning should also be treated as a commercial asset, not just an operational function, because reliability increasingly influences purchasing decisions in high-throughput oncology and surgical settings.
For investors, the market rewards disciplined exposure to differentiated supportive care assets and scalable generic operations. The clearest opportunities lie in portfolios that combine clinical relevance with cost-efficient manufacturing, and in companies that can manage the transition from exclusivity to competitive positioning without eroding margin structure. Pipeline readouts, label expansion potential, and formulation milestones matter, but so does the ability to anticipate pricing dynamics following patent events and to assess supply chain exposure across active ingredients and production geographies. Due diligence should account for reimbursement architecture, procurement sensitivity, and the operational cost of maintaining continuity in a category where shortages can quickly reshape purchasing behavior.
For procurement teams and healthcare operators, the strategic task is to balance cost control with therapy continuity and clinical outcomes. That involves evaluating anti-emetic regimens as part of total episode management, comparing options based on dosing frequency, prophylaxis durability, rescue utilization, and supply reliability, rather than selecting purely on lowest unit price. Formulary design should incorporate contingency planning for shortage scenarios and acknowledge the administrative burden associated with safety monitoring requirements for certain molecules. The goal is to protect patient access and workflow stability while managing expenditure in a category that remains essential to oncology, surgical, and gastrointestinal care.
The strategic stakes in this market are rising as growth becomes more segmented and competitive advantage shifts toward execution quality across clinical positioning, access architecture, and supply resilience. Working-level teams seeking to translate these dynamics into procurement, investment, or product strategy will benefit from a more granular view of regional demand patterns, segment-level volume and pricing trends, and scenario analysis around patent events, reimbursement shifts, and shortage risk. A deeper research dossier can provide that level of detail, including breakouts by region, drug class, application, and company-level competitive mapping, to support more precise planning and prioritization.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Anti-Emetic Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com