

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Fisetin Market: How 8.96% CAGR and Supplement Demand Reshape 2032 Revenue

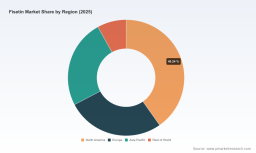
Strategic Trends and Commercial Opportunities in the Global Fisetin Market
Market Overview and Core Challenges
The global fisetin market has transitioned from a niche botanical extract to a high-value ingredient category, driven by accumulating clinical and preclinical evidence around its senolytic, anti-inflammatory, and metabolic-modulating properties. Between 2020 and 2025, the market expanded from approximately USD 38.45 million to USD 57.8 million, reflecting a structural shift rather than a cyclical uptick. Forward projections extending through 2032 indicate a compound annual growth rate of 8.96 percent, positioning fisetin as a sustained growth vector within the broader functional ingredients landscape. Revenue trajectory suggests that by 2032, global market size will approach USD 105.42 million, a level that underscores maturation but also signals intensifying competition for market share.
This growth trajectory is not without friction. The industry currently faces several structural challenges that will define the next phase of market evolution. First, purity standardization and bioequivalence remain unresolved . Fisetin exhibits variable extraction yields and stability profiles depending on the plant source, solvent method, and downstream processing. Without universally accepted pharmacopeial standards, manufacturers and formulators face uncertainty in dosing consistency, which complicates both regulatory submissions and consumer trust. Second, raw material sourcing is under transition . Traditional trunk-based extraction is increasingly being replaced by leaf and branch sourcing from Cotinus coggygria or Rhus succedanea , a shift designed to improve yield per hectare, reduce ecological impact, and lower unit costs. While this transition supports scaling, it introduces variability in active content and requires tighter quality control frameworks. Third, geopolitical and trade dynamics are reshaping cost structures . Ongoing tariff policies on certain botanical and chemical imports, particularly from China, have raised landed costs for raw fisetin and finished extracts. Companies that rely on single-source procurement without hedging strategies or alternative supply routes are experiencing margin compression, forcing a reevaluation of global sourcing architectures.
Hesperidin Market
Key Growth Drivers
Technological Innovation in Extraction and Purification
The most consequential driver of fisetin market expansion is the maturation of extraction and purification technologies. Early commercial fisetin was often associated with moderate purity levels and inconsistent batch-to-batch performance, limiting its use to research and low-dose supplement formulations. Recent advances in controlled solvent systems, selective crystallization, and advanced chromatographic purification have enabled producers to consistently achieve 98 percent to 99 percent purity. These technological gains directly translate into higher active concentrations per gram, which reduces formulation volume, improves stability in complex matrices, and supports higher-value applications. The shift is not merely technical; it is commercial. Higher-purity fisetin commands premium pricing, supports longer shelf-life expectations, and opens the door to cosmeceutical and pharmaceutical-grade applications that were previously inaccessible. Producers investing in closed-loop extraction, in-process analytics, and validated purification pathways are positioning themselves to capture margin while simultaneously reducing waste and solvent recovery costs.
Regulatory Evolution and Safety Validation
Regulatory clarity is accelerating market confidence. The achievement of self-affirmed Generally Recognized as Safe (SA-GRAS) status for a leading branded fisetin ingredient marks a pivotal inflection point. This status, validated through systematic safety documentation and toxicological assessment, reduces regulatory friction for downstream dietary supplement and health product manufacturers seeking to incorporate fisetin into new formulations. Parallel developments reinforce this trajectory. An NDI notification filing for fisetin sourced from Cotinus coggygria was recorded in early 2025, signaling formal engagement with FDA processes for novel dietary ingredients. Toxicological data, including animal subchronic studies indicating a no-observed-adverse-effect level of 500 mg/kg/day, and human tolerability studies at 100 mg/day reporting no adverse events, provide a practical safety foundation that supports dose escalation in consumer and clinical applications. Regulatory progress does more than satisfy compliance; it lowers the barrier to commercial adoption, shortens formulation timelines, and enables marketing claims grounded in documented safety profiles.
Demand-Side Transformation Across Applications
Consumer and enterprise behavior is reshaping where fisetin creates value. In dietary supplements, demand is being driven by anti-aging, cellular longevity, and cognitive wellness narratives. Consumers are increasingly seeking ingredients with dual functional and health-span benefits, and fisetin's senolytic and neuroprotective research profile aligns with that expectation. Simultaneously, the cosmetics and personal care sector is exploring fisetin for its antioxidant and skin-resilience potential, although this application represents a smaller share of current revenue. The pharmaceutical and research segment remains focused on mechanistic studies, bioavailability optimization, and early-stage therapeutic exploration. Across these segments, a common theme emerges: buyers are moving from ingredient curiosity to evidence-based procurement. Formulators and brand owners are requesting batch-specific Certificates of Analysis, stability data, source transparency, and increasingly, clinical or tolerability documentation. This shift is compressing the market toward suppliers who can provide not only high-purity material but also verifiable quality systems and application support.
Supply Chain Reconfiguration and Cost Dynamics
Supply chain dynamics are evolving from cost-minimization to resilience-building. The market has seen a marked concentration of manufacturing capacity in China, where scale, extraction expertise, and certification infrastructure have matured rapidly. This concentration offers efficiency and price advantages but also introduces exposure to trade policy volatility, logistics disruption, and quality assurance complexity. In response, several manufacturers and distributors are diversifying source origins, qualifying multiple extraction sites, and strengthening documentation for traceability and compliance. At the same time, capacity expansion, with monthly production capabilities reaching multi-ton levels for select facilities, is beginning to address supply tightness for high-purity specifications. The net effect is a market where cost competitiveness is increasingly tied to process efficiency, yield optimization, and multi-source qualification rather than raw commodity pricing alone. Companies that structure their supply chains around redundancy, certification depth, and transparent sourcing are better positioned to protect margins while meeting the growing demand for auditable quality.
Worldwide Aescin Market
Competitive Landscape and Leading Strategies
The fisetin market is characterized by a concentrated yet evolving competitive field. Market concentration data indicates that a relatively small group of firms controls a substantial share of revenue, yet the landscape is not static. Leading players differentiate along purity capability, regulatory positioning, source material strategy, and application focus.
Strategic Positioning of Key Players
Companies with a demonstrated focus on high-purity fisetin are building defensible positions through process control and certification depth. Manufacturers specializing in 99 percent purity for nutraceutical and anti-aging supplement markets are competing on batch consistency, extraction yield, and downstream application support rather than price alone. Branded high-purity fisetin offerings that have achieved SA-GRAS status illustrate how regulatory differentiation can translate into commercial advantage. By combining purity at the 98–99 percent range with documented safety validation, such products reduce the compliance burden for customers and enable faster time-to-market for supplement and health product lines.
PW Consulting
Other manufacturers emphasize certification portfolios and sourcing flexibility. Factories operating with BRC, Organic, ISO9001, GMP, HACCP, and halal/kosher certifications address the procurement requirements of global buyers who need auditable quality systems. Some producers have expanded capacity significantly, with monthly output reaching several tons across multiple specifications, which improves supply reliability for bulk customers. This scale focus serves price-sensitive and volume-driven segments while maintaining access to a broad specification range. Meanwhile, suppliers focused on extract from Rhus succedanea or Cotinus coggygria differentiate by botanical origin, purity thresholds, and application orientation. Some position their material for cognitive health and nootropic formulations, while others serve food, nutraceutical, and pharmaceutical ingredient channels with purity up to 98 percent. Distributors and specialty chemical suppliers complement the landscape by providing API-grade fisetin, reference standards, and research-grade material, serving customers whose primary need is documentation, traceability, and analytical consistency rather than large-scale commercial volume.
Market Evolution Trends: Consolidation, Differentiation, and New Entry
Several structural trends are reshaping how the competitive field will evolve. First, consolidation pressure is rising among producers who lack scale or differentiated purity capability. As demand for 98 percent-plus fisetin grows and buyers demand stronger quality documentation, smaller extractors without advanced purification or certification infrastructure face margin erosion and potential acquisition or partnership scenarios. Second, differentiation is becoming the primary competitive lever. Brands that combine purity, regulatory status, and application-specific documentation are capturing premium positioning. This creates a bifurcated market: high-value, documentation-rich offerings on one side, and volume-oriented, specification-broad alternatives on the other. Third, new entrants are likely to emerge from two directions. Ingredient and formulation companies may enter by leveraging branded fisetin with regulatory credentials, while contract manufacturers may enter by offering toll-processing and purification services for buyers who prefer to own the botanical or extract source but outsource downstream purification. Regional diversification is also probable, as trade cost pressures incentivize buyers and suppliers to qualify non-China sourcing options or regional blending strategies to mitigate tariff exposure.
Forward Outlook: Three Trends Shaping the Next 3–5 Years
The data trajectory and current developments point to three interconnected trends.
- Purity and documentation become table stakes. The rapid uptake of 98 percent-plus fisetin, coupled with regulatory milestones such as SA-GRAS status and NDI filings, suggests that high-purity, well-documented material will increasingly be the baseline expectation rather than a premium differentiator. Suppliers that standardize high-purity production, batch quality analytics, and safety documentation will capture disproportionate share with formulators and brand owners.
- Application breadth will expand, but at uneven pace. Dietary supplements will likely remain the largest revenue anchor, supported by longevity and cognitive wellness demand. Cosmeceutical applications may grow as topical antioxidant and skin-resilience formulations incorporate fisetin, though this segment will require formulation stability data and cosmetic regulatory alignment. Pharmaceutical and research use will continue to advance in exploratory directions, but clinical translation will be stepwise and dependent on bioavailability improvements and trial outcomes.
- Supply chain resilience will determine margin stability. Trade policy, sourcing diversification, and capacity scaling will interact to shape cost structures. Companies with multi-source qualification, process efficiency, and documented quality systems will be better insulated from tariff-driven cost shocks and logistics volatility. Conversely, single-source dependency without hedging or qualification alternatives will remain a vulnerability.
These trends translate into clear commercial opportunities for players that act early. Suppliers can pursue premium positioning through purity-plus-documentation bundles and application support. Formulators and brands can accelerate product development by aligning with suppliers that reduce regulatory friction and provide batch consistency. Investors and corporate development teams can focus on assets with scalable purification capacity, certification depth, and diversified sourcing. At the same time, uncertainty warrants caution. Bioavailability limitations, the pace of clinical translation, and potential shifts in trade or regulatory policy could alter adoption speed. Demand concentration in a few application categories also means that market growth is sensitive to consumer sentiment and scientific narrative shifts.
Strategic Recommendations for Decision Makers
For manufacturers and ingredient producers, the priority is to convert extraction and purification capability into a defensible commercial position. Investments in consistent high-purity output, in-process quality analytics, and certification breadth will differentiate offerings in a market where batch reliability and documentation increasingly drive purchasing decisions. Producers should also evaluate source diversification and regional supply qualification to reduce exposure to trade-related cost volatility, and consider branded positioning where regulatory status can be leveraged to shorten customer adoption cycles.
For investors and corporate strategy teams, the opportunity lies in identifying assets that combine scale, purity capability, and compliance readiness. Due diligence should emphasize production capacity stability, purity consistency across batches, documentation depth, and the ability to serve multiple application segments. Portfolio exposure should account for the uneven pace of application growth, with dietary supplements likely offering near-term scale and cosmeceutical or pharmaceutical pathways requiring longer development horizons and milestone-based risk assessment.
For procurement leaders and formulation teams, the focus should be on supplier qualification that prioritizes purity consistency, CoA transparency, stability data, and regulatory documentation over lowest unit price alone. Structuring supplier relationships around multi-source qualification, clear specification agreements, and application support can reduce formulation risk and accelerate product launches. Sourcing diversification should be evaluated not only for cost but also for resilience against trade and logistics disruptions.
Given the pace of regulatory developments, capacity expansions, and application evolution, decision makers benefit from continuous visibility into purity standardization progress, emerging regulatory milestones, competitive moves, and sourcing alternatives. Access to segmented, up-to-date market intelligence enables more precise timing for product development, supplier selection, and strategic investment. Additional detailed segmentation data and tailored commercial guidance remain available through the full PW Consulting report, which provides deeper breakdowns across purity specifications, application channels, regional dynamics, and company-level strategic benchmarks for those seeking to translate these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Fisetin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com