

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Fondant Market 2026: 5 Strategic Shifts Reshaping Industry Growth Beyond 5.24% CAGR

Navigating the Global Fondant Market: Strategic Trends & Commercial Opportunities Through 2032
Market Landscape & Core Challenges
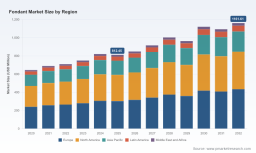
The worldwide fondant market has demonstrated resilient growth over the past five years, expanding from approximately $645 million in 2020 to an estimated $812 million in 2025. The forecast horizon through 2032 points to a compound annual growth rate of 5.24%, with projected revenues reaching $1.16 billion by the end of the period. This trajectory reflects a mature but steadily evolving category, where incremental innovation and shifting consumer preferences are reshaping demand patterns rather than triggering abrupt volume spikes.
Revenue distribution across regions reveals a distinctly Western-leaning baseline, with Europe and North America collectively accounting for the majority of current sales. Asia Pacific, Latin America, and the Middle East & Africa represent smaller but dynamically growing shares, often driven by urbanization, rising disposable incomes, and the gradual professionalization of baking supply chains. From an application perspective, commercial bakeries remain the dominant end-use channel, followed by residential and home use, with hotels, restaurants, and catering forming a specialized but high-value segment. By formulation type, rolled fondant continues to command the largest share, while poured and sculpting/modeling variants serve niche professional and artisan workflows.
The competitive structure remains moderately consolidated. The top three players hold roughly 38.5% of global revenue, while the top five extend their combined share to approximately 52.3%. This concentration suggests established incumbents retain meaningful pricing power and distribution leverage, yet it also leaves substantial room for specialized entrants, regional champions, and private-label expansion in underserved markets.
Despite the positive macro outlook, the industry is navigating several structural friction points that will define competitive outcomes over the next cycle:
- Input cost volatility and margin pressure. Sugar price movements have shown pronounced swings, with a 15% increase recorded in 2025 due to weather-related supply constraints in key producing regions. For a category where sugar and sugar derivatives form the backbone of formulations, such swings compress margins for manufacturers and create pricing uncertainty for downstream bakeries and retailers.
- Regulatory complexity around labeling and ingredients. Updated allergen labeling requirements in key markets, including recent EU rules clarifying disclosure for milk derivatives in fondant products, are raising compliance costs and forcing reformulation or packaging adjustments. These requirements are not merely bureaucratic; they reshape shelf visibility, procurement standards, and cross-border trade workflows.
- Labor cost inflation in commercial baking. Wage pressures in developed markets have raised operational costs for commercial bakeries, with U.S. bakery labor costs rising 7.2% year-over-year in late 2024. Higher labor expenses push buyers toward products that reduce preparation time, improve consistency, and simplify decoration workflows, subtly shifting demand toward ready-to-use and pre-formatted fondant solutions.
Together, these dynamics create a market that is growing but not frictionless. Companies that treat cost volatility, regulatory shifts, and labor-driven workflow changes as strategic design parameters rather than episodic headaches are better positioned to protect margins and capture share.
Key Drivers Reshaping the Market
Technological and Formulation Innovation
Product innovation has become a primary lever for differentiation in a category where base functionality is well established. Recent launches illustrate how manufacturers are expanding beyond traditional sugar-based formats to address dietary restrictions, flavor variety, and application convenience. A notable example is the introduction of vegan and allergen-free fondant lines targeting global markets, reflecting a broader push to align product portfolios with plant-based and free-from consumer preferences. Alongside such formulation shifts, improvements in texture stability, kneadability, and finish quality are helping brands win over professional decorators who demand predictable performance under varying ambient conditions.
On the tool and workflow side, integrated decorating kits, updated catalogs featuring new application tools, and expanded portfolios showcased at major trade events signal an industry-wide emphasis on end-to-end solutions rather than standalone ingredients. This matters because fondant is increasingly evaluated not just on taste or appearance, but on how efficiently it fits into high-throughput bakery operations or home-baking experiences.
Consumer and Enterprise Demand Shifts
Demand-side behavior is evolving on two parallel tracks. In residential and home-use settings, the continued popularity of DIY cake decorating, celebration-driven baking, and social-media-visible presentation keeps demand for user-friendly fondant products robust. In commercial channels, buyers are prioritizing consistency, speed, and compliance. The structural rise in plant-based fondant demand in 2024, growing at approximately 12%, underscores a consumer-led shift that is crossing over into procurement specifications. Retail and food-service buyers increasingly request options that accommodate vegan, allergen-sensitive, or reduced-sugar preferences without sacrificing finish quality.
This convergence is changing the value proposition. Manufacturers that can offer a spectrum of formats, from standard rolled products to specialized modeling pastes and pourable variants, are better equipped to serve both mass-market and specialist applications. The ability to provide clear labeling, consistent batch quality, and format flexibility has become a decisive advantage in winning repeat orders from professional customers.
PW Consulting
Supply Chain, Raw Materials, and Cost Structure
The cost structure of fondant production is tightly linked to agricultural commodity dynamics and logistics. Sugar supply disruptions in major producing countries have already demonstrated how quickly input costs can escalate, forcing manufacturers to reconsider hedging strategies, forward contracting, and pricing mechanisms. Beyond raw materials, transportation and packaging costs remain sensitive to broader macroeconomic conditions, and any sustained increase in bakery labor costs further pressures end-users to seek efficiency gains from the ingredients and tools they purchase.
In response, supply chain resilience is becoming a strategic differentiator. Companies that diversify sourcing, invest in inventory buffering for critical inputs, and design products that reduce on-site labor intensity are gaining operational advantages. For commercial bakeries and patisseries, the appeal of pre-made fondants, sheeting equipment, and bulk formats is amplified when labor is expensive and throughput targets are high. This creates a reinforcing cycle: cost pressure drives demand for labor-saving formats, which in turn encourages suppliers to expand ready-to-use and wholesale-friendly offerings.
Regulatory and Standards Environment
Regulatory developments are quietly reconfiguring market access and product design. Updated allergen labeling rules, particularly where milk derivatives and other common allergens are concerned, require clearer disclosure and sometimes reformulation to maintain market eligibility. While compliance adds cost, it also raises the barrier to entry for lower-quality or poorly documented offerings. Established brands with robust quality systems and transparent ingredient documentation are consequently advantaged in regulated retail and food-service channels. Over time, harmonization of labeling expectations across regions could simplify cross-border distribution, but near-term fragmentation continues to reward players with strong regulatory affairs capabilities and flexible packaging infrastructure.
Competitive Landscape & Leading Strategies
The competitive field blends global-scale manufacturers, regional specialists, and tool-and-kit providers that extend the fondant ecosystem. Several patterns stand out in how leading companies position themselves and compete for share.
One clear axis of differentiation is portfolio breadth combined with application focus. Leading manufacturers of ready-to-roll icings, modeling pastes, and gum pastes have built distribution networks that reach professional decorators and retail channels worldwide. Their advantage lies in offering a cohesive range that supports multiple decoration techniques, reducing the need for buyers to source disparate products from multiple suppliers. Complementary players emphasize premium flavor portfolios, including vanilla, chocolate, and sugar-free options, and supply globally to bakeries and retailers. This premium-plus-variety positioning appeals to customers seeking finished aesthetics and taste variety without sacrificing reliability.
Another strategic cluster focuses on the home and prosumer segments through mixes, pre-rolled products, and decorating kits with international distribution. By bundling tools with consumables, these companies increase basket size and simplify adoption for less experienced users. In parallel, suppliers targeting commercial bakeries and patisseries have expanded into professional-grade sheeters and pre-made fondants, directly addressing labor efficiency and throughput requirements. Bulk producers offering pourable fondants and multiple colors and flavors serve wholesale markets where standardization and volume matter most.
European and specialty producers add further nuance. High-quality fondant icings and chocolate fondants for industrial and artisan use illustrate how regional expertise can be scaled internationally. Export activity to Europe and Asia by professional-focused suppliers shows that formulation quality and application support can open doors beyond a company's home market.
Recent market moves reinforce these strategic directions:
- Vegan and allergen-free fondant lines have been launched for global markets, signaling a deliberate pivot toward inclusive formulations and broader procurement eligibility.
- Expanded fondant portfolios have been exhibited at major industry trade shows, highlighting the importance of face-to-face engagement, cross-category visibility, and B2B relationship building.
- Updated catalogs featuring new decorating tools and flavors have been released, underlining the continuing relevance of tool-and-consumable bundling and seasonal innovation rhythms.
Looking at the structure of competition, the market appears to be moving along two tracks simultaneously. On one hand, consolidation is plausible in wholesale and commercial channels where scale, distribution density, and compliance infrastructure confer advantages. On the other hand, fragmentation persists in artisan, regional, and specialty segments where formulation distinctiveness, local taste preferences, and service intensity matter more than sheer volume. New entrants are most likely to succeed by targeting specific dietary needs, specialized applications, or underserved geographies rather than challenging incumbents across the full spectrum of a mature category.
Forward Outlook: Trends to 2032
Pulling together the market trajectory and current dynamics, a few trends are likely to shape the next three to five years.
Sugar Sphere Market
First, formulation inclusivity will move from niche to mainstream expectation. The combination of rising plant-based demand, allergen-aware procurement, and regulatory pressure on labeling suggests that brands without vegan, free-from, or clearly documented ingredient options will face growing friction in retail and food-service channels. Companies that integrate these attributes early, while maintaining finish quality and stability, are likely to capture incremental share and command stronger customer loyalty.
Second, labor economics will continue to tilt demand toward convenience and consistency. As wage pressures persist in commercial baking, the value proposition of pre-made fondants, sheeting equipment, and bulk formats will remain strong. Suppliers that can quantify time savings, reduce variability, and support high-throughput workflows will be better positioned to win and retain commercial accounts. This trend also creates cross-selling opportunities between consumables and equipment, particularly for professional bakeries and patisseries.
Third, regional divergence will deepen even as global brands expand. Europe and North America will likely remain revenue anchors, but growth rates may accelerate in Asia Pacific and other emerging regions as baking cultures professionalize and retail modernizes. Localizing flavor profiles, packaging sizes, and compliance documentation will be critical for companies seeking to convert regional potential into durable share. At the same time, exposure to commodity volatility and regulatory fragmentation will require disciplined risk management and flexible sourcing strategies.
Potential risks should not be overlooked. Continued sugar price volatility could compress margins and slow volume growth if manufacturers pass through costs unevenly. Regulatory divergence, especially around allergens and labeling, could increase time-to-market for new products and raise compliance overhead. In addition, if economic conditions tighten in key consumer markets, discretionary spending on celebration baking and premium decoration could soften, temporarily affecting residential and hospitality-related demand.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product architecture with where demand is heading, not where it has been. That means strengthening vegan and allergen-free lines, improving texture and stability consistency across batches, and offering format choices that reduce labor intensity for commercial buyers. Equally important is building a supply chain that can absorb commodity shocks without disrupting service levels, aided by forward contracting, diversified sourcing, and sensible inventory buffers. Clear allergen documentation and packaging flexibility should be treated as competitive assets, not administrative burdens.
For investors, the most compelling value creation opportunities lie at the intersection of formulation innovation and workflow efficiency. Exposure to brands with credible free-from portfolios, strong professional-channel relationships, and integrated tool-and-consumable offerings is likely to be more resilient than pure exposure to undifferentiated commodity-style fondant production. Monitoring regional growth pockets, especially where modern retail and professional baking infrastructure are expanding, can help identify markets where share gains may compound over time.
For procurement leaders and bakery operators, the strategic imperative is to evaluate fondant suppliers on total cost of ownership rather than unit price alone. Labor savings, reduction in rework, clearer labeling, and reliable batch consistency can outweigh modest price premiums. Establishing multi-supplier arrangements for critical formats, securing commitments on vegan and allergen-free availability, and aligning order patterns with labor planning can improve operational stability in a volatile input environment.
Detailed segmentation data, company-level revenue estimates, regional growth decompositions, and scenario-based forecasts can sharpen these decisions further. For teams that need granular comparisons across types, applications, and regions, or customized guidance tied to specific product portfolios and go-to-market plans, the full PW Consulting research report provides the deeper datasets and tailored analysis required to translate these market-level insights into executable strategy.
Marzipan Market
For detailed analysis of this topic, please visit the official page: Worldwide Fondant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com