

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Magnetic Levitation 3D Bioprinting Market: 20% CAGR and 57% North America Share

Strategic Trends and Commercial Opportunities in the Worldwide Magnetic Levitation 3D Bioprinting Market
Market Landscape and Core Challenges
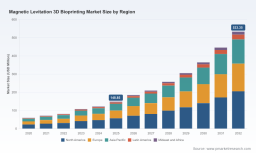
The global market for magnetic levitation 3D bioprinting has transitioned from an experimental niche to a commercially viable segment of the broader bioprinting and life sciences tools industry. Between 2020 and 2025, market valuations expanded from approximately $59.82 million to $148.85 million, reflecting a compound annual growth rate of 20.0% through the forecast period ending in 2032. Projections indicate the market will surpass $300 million by 2029 and approach $533 million by 2032. This trajectory positions magnetic levitation bioprinting among the faster-growing subcategories within advanced manufacturing for biological applications, driven by its ability to handle delicate cell suspensions without nozzle clogging and to construct complex three-dimensional architectures that better mimic native tissue environments.
Despite this momentum, the industry sits at a critical inflection point. Three structural challenges define the current landscape. First, standardization and validation remain fragmented. While research laboratories and early-stage therapeutic developers are adopting levitation-based bioprinting for organ-on-chip models and disease modeling, the absence of unified quality benchmarks, reproducibility protocols, and regulatory-accepted documentation pathways limits broader industrial deployment. Second, integration complexity continues to slow adoption. Magnetic levitation workflows require precise coordination between bio-magnetic particle formulation, specialized printing hardware, and downstream culture or assay systems. Organizations without established bioengineering infrastructure face steep learning curves, raising the total cost of implementation beyond hardware acquisition. Third, the market is navigating a maturity gap between academic proof-of-concept and commercial scale-up. Many systems demonstrate impressive capabilities in small-scale experiments, yet translating those outcomes to consistent batch production, long-term culture stability, and cost-effective consumables supply remains an unresolved engineering and operational hurdle.
These challenges do not diminish the market's potential; rather, they clarify where value creation will concentrate. Organizations that solve reproducibility, streamline integration, and align solutions with regulatory expectations will capture outsized share as the market moves from prototype validation to routine application in drug development and regenerative medicine pipelines.
Key Drivers Reshaping the Market
Several interconnected forces are accelerating adoption and redirecting investment toward magnetic levitation bioprinting. Understanding these drivers provides a clearer picture of where demand will intensify and which capabilities will differentiate winners.
Technological Innovation and Precision Biomanufacturing
The core appeal of magnetic levitation bioprinting lies in its non-contact manipulation of cells and biomaterials. By using bio-magnetic particles and controlled magnetic fields, systems can position cell-laden droplets and assemble three-dimensional structures without the shear stress associated with extrusion-based nozzles. This capability has proven particularly valuable for constructing perfusable microtissues, vascularized networks, and heterogeneous cell arrangements that are difficult to achieve with traditional methods. Recent progress in bio-ink formulation, particle functionalization, and software-driven deposition control has expanded the range of usable cell types and improved structural fidelity. In parallel, the integration of imaging feedback and automated calibration is reducing setup time and operator dependence, making systems more accessible to groups that lack deep biofabrication expertise.
These technical advances are shifting the conversation from feasibility to utility. Rather than asking whether magnetic levitation can produce a tissue-like construct, developers are now evaluating whether the approach can generate physiologically relevant models with sufficient reproducibility to support compound screening, toxicity assessment, and disease mechanism studies. That shift is a powerful adoption catalyst, especially for organizations seeking alternatives to animal models and two-dimensional cultures.
Regulatory Evolution and the Push for Predictive Human Models
Policy and regulatory dynamics are reinforcing demand for more human-relevant testing platforms. In multiple regions, regulatory agencies and funding bodies have increased emphasis on new approach methodologies, organ-on-chip systems, and advanced in vitro models that can reduce reliance on animal testing while improving translational predictivity. This environment favors bioprinting approaches that can generate standardized, multi-cellular architectures with controlled spatial organization. Magnetic levitation systems, by enabling delicate assembly and modular design, are well positioned to contribute to these platforms.
At the same time, regulatory expectations are raising the bar for documentation, batch consistency, and assay validation. Companies that proactively build quality management practices into their bioprinting workflows, and that provide customers with clear usage protocols and performance specifications, are more likely to see accelerated qualification in regulated development pipelines. The trend is not simply about compliance; it is about creating tools that can be trusted inside decision-making processes for candidate selection and safety evaluation.
Demand-Side Shifts in Drug Discovery and Regenerative Pipelines
On the demand side, pharmaceutical and biotechnology organizations are under continuous pressure to improve early-stage success rates and shorten development timelines. High attrition in preclinical and clinical stages is prompting greater investment in better predictive models, including human cell-based assays and microphysiological systems. Magnetic levitation bioprinting supports this shift by enabling the creation of tissue models that more closely replicate cell-cell interactions, tissue architecture, and microenvironmental cues. In oncology research and toxicity screening, where spatial organization and cell heterogeneity strongly influence outcomes, these capabilities have direct relevance.
Beyond drug discovery, regenerative medicine applications are expanding the long-term addressable market. Research programs focused on tissue repair, disease modeling, and cell-based therapies are exploring bioprinted constructs as both research tools and potential therapeutic components. While commercial regenerative products remain further out, the growing volume of early-stage work is increasing demand for flexible bioprinting platforms that can accommodate diverse cell sources, biomaterials, and geometries.
Supply Chain and Cost Structure Dynamics
The economics of bioprinting adoption are also changing. Laboratories and companies increasingly evaluate not only the capital cost of equipment but also the recurring expenses associated with consumables, bio-inks, maintenance, and technical support. Magnetic levitation systems depend on specialized particles and formulated bio-inks, which means consumable supply reliability and pricing directly affect total cost of ownership. At the same time, manufacturing scale-up and broader adoption of advanced materials are gradually improving availability and reducing per-unit costs for certain consumables.
A second supply-side dynamic involves the growing preference for integrated solutions rather than isolated instruments. Purchasers want platforms that connect more smoothly with downstream workflows, including cell culture, assay readouts, and data analysis. Suppliers that reduce friction across the workflow chain can command stronger positions, even if their hardware pricing is not the lowest. This dynamic is encouraging partnerships between instrument makers, material suppliers, and service providers, and it is reshaping how value is captured across the ecosystem.
Competitive Landscape and Leading Strategies
The market's growth is unfolding within a concentrated competitive structure. A relatively small group of leading vendors accounts for a substantial share of revenue, reflecting the technical barriers to entry, the importance of application-specific know-how, and the value of established customer relationships in research and development settings. Concentration at the top underscores a market where differentiation comes less from price competition and more from performance reliability, workflow integration, and the ability to support demanding use cases.
Leading players are pursuing distinct strategic positions. Some emphasize high-performance systems engineered for complex tissue assembly and advanced research applications, targeting customers who prioritize capability and precision. Others focus on broadening adoption by simplifying workflows, strengthening consumables supply, and offering stronger application support. This split creates a natural segmentation between performance-oriented and accessibility-oriented offerings, with the most successful companies often blending both by delivering capable systems alongside practical support, training, and reliable material supply.
Recent activity in the sector reflects these strategic priorities. Development efforts are increasingly directed toward improving user experience, strengthening reproducibility, and expanding the consumable ecosystem. In a market where experimental outcomes depend heavily on material consistency and process control, vendors that can provide well-characterized bio-magnetic particles, standardized bio-inks, and clear operational guidance are building a meaningful advantage. Equally important is the move toward software enhancements that simplify process setup, enable repeatable protocols, and support data capture for quality assurance.
PW Consulting
Market structure is also evolving through selective consolidation and targeted entry. Incumbents with established distribution, regulatory-facing support, and cross-selling opportunities into adjacent life science tools are well placed to expand share. At the same time, new entrants with novel material formulations, specialized software, or differentiated printing mechanics continue to appear, particularly where they address a specific bottleneck such as vascularization, high-throughput model generation, or improved cell viability. The likely trajectory is not a race to the bottom but a layered market in which a few broad-platform leaders coexist with specialists serving high-value niches. For customers, this means an expanding set of options, but also a greater need to evaluate vendors against the specific requirements of their workflows and development goals.
Future Trends and Commercial Implications
Looking ahead, several trends are likely to shape the next three to five years and create distinct commercial opportunities.
Worldwide Hydrogel Bioink Market
- From models to standardized workflows. Magnetic levitation bioprinting will increasingly be judged not only by what it can produce, but by how consistently it can do so across users and sites. Expect stronger emphasis on protocol libraries, quality controls, and integration with laboratory data systems. Organizations that offer repeatable, well-documented workflows will be better positioned for adoption in both research and preclinical settings.
- Convergence with organ-on-chip and microphysiological systems. Bioprinting will increasingly serve as an enabling layer within broader model platforms. Magnetic levitation's ability to assemble delicate, multi-cellular structures makes it a natural fit for constructing more representative tissue models that feed into screening and mechanistic studies. Commercial value will accrue to solutions that connect printing with culture, sensing, and analysis rather than to standalone hardware alone.
- Consumables and services as strategic moats. As hardware becomes more widely available, differentiation will shift toward consumables, application support, and service reliability. Suppliers that secure dependable material supply, offer validated formulations, and help customers accelerate assay integration can create stickier relationships and more predictable revenue streams.
These trends point to clear opportunities, but they also carry risk. Regulatory expectations may evolve in ways that require additional validation burden, particularly for applications moving closer to decision-critical use. Supply chain fragility for specialized biomaterials could affect cost and continuity. In addition, competition from alternative bioprinting and model-building technologies will remain intense, especially where other approaches offer simpler integration or lower operating cost. Companies entering or expanding in this space should therefore treat technology performance as necessary but not sufficient, and should invest early in workflow maturity, support infrastructure, and customer success capabilities.
Actionable Guidance for Decision-Makers
For manufacturers and technology developers, the priority is to reduce adoption friction while protecting performance credibility. That means investing in consumables reliability, user-centric software, and application support that helps customers move from pilot experiments to routine use. Differentiated value will come from making complex biology easier to execute reproducibly, not simply from adding features.
Worldwide Photocuring Biological 3D Printer Market
For investors, the most compelling opportunities lie in companies that combine technical capability with commercial execution: strong material supply chains, clear workflow integration, and a credible path to recurring revenue through consumables and services. Evaluating exposure to regulatory shifts and the ability to support regulated development environments should be part of the due diligence process, particularly as customers seek tools that can fit into formal development pipelines.
For procurement and research leadership, selection decisions should be based on workflow fit and total cost of ownership rather than headline specifications. Key considerations include consumables availability, protocol support, training, and the vendor's ability to help with reproducibility and documentation. Early engagement with vendors that can demonstrate practical implementation paths will reduce downstream risk and accelerate time to value.
Detailed segmentation data, company-level assessments, regional dynamics, and scenario analysis can sharpen these decisions further. Readers seeking a deeper, customized view of the market can request the full PW Consulting research report for comprehensive figures, competitive profiling, and application-specific guidance tailored to their strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Magnetic Levitation 3D Bioprinting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com