

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
EHF Technology Market: How 21.66% CAGR and Telecom Demand Redefine Growth

Navigating the EHF Technology Revolution: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Scale, Momentum, and Critical Inflection Points
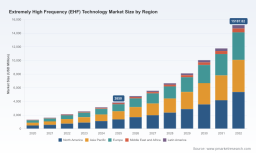
The global Extremely High Frequency (EHF) technology market has entered a period of accelerated expansion, driven by the convergence of advanced communications infrastructure, defense modernization, and next-generation automotive connectivity. Valued at approximately 1320.5 million USD in 2020, the market has demonstrated consistent upward momentum, reaching 3850.0 million USD by 2025. Projections indicate this trajectory will intensify, with the market expected to surpass 4776.71 million USD in 2026 and climb to 15187.82 million USD by 2032. This expansion translates to a compound annual growth rate of 21.66 percent across the forecast horizon, signaling a structural shift rather than a cyclical upturn. The breadth of this growth underscores EHF's transition from a niche capability to a foundational layer across multiple critical industries.
Despite the compelling growth narrative, the industry is navigating several structural inflection points that will determine which organizations capture value and which struggle to scale. The first challenge lies in hardware maturity and thermal-electrical tradeoffs. At frequencies spanning 30 to 300 GHz, system designers face compounding physical constraints, including low power amplifier efficiency, elevated insertion losses across interconnections and waveguides, and the limitations of analog-to-digital converters operating at extreme frequencies. Thermal management in densely integrated EHF systems further complicates performance optimization, creating a persistent engineering bottleneck that slows time-to-market for next-generation terminals, relays, and test platforms.
A second critical challenge involves the evolving spectrum governance landscape. Regulatory bodies such as the Federal Communications Commission maintain detailed frequency allocation tables that govern EHF band usage across communications, radar, and scientific applications, with recent revisions reinforcing the need for precise licensing and interference mitigation. International standardization efforts, including updated ITU-R nomenclature and emerging IEEE specifications targeting multi-gigabit wireless links in the 252 to 325 GHz range, are simultaneously expanding the technical envelope while introducing compliance complexity. organizations must now align product development cycles with a regulatory environment that is becoming more granular and internationally coordinated.
The third inflection point centers on market concentration and competitive differentiation. A relatively concentrated set of players currently controls a substantial share of value capture, with the top three organizations accounting for roughly 38.5 percent of market revenue and the top five collectively representing approximately 52.15 percent. This concentration reflects the capital intensity of high-frequency development, the importance of established defense and aerospace relationships, and the premium placed on validated test and measurement ecosystems. For emerging entrants and adjacent technology providers, breaking into this landscape requires more than incremental innovation; it demands differentiated positioning in specific end-use verticals, strategic component specialization, or novel deployment models that reduce integration friction.
Strategic Catalysts: What Is Accelerating EHF Adoption
Technological Innovation and High-Frequency Breakthroughs
The EHF ecosystem is being reshaped by a series of technical advancements that are progressively lowering the barriers to practical deployment. Progress in millimeter-wave and sub-terahertz architectures has enabled more efficient signal routing, improved beam steering, and higher-throughput wireless links that were previously confined to laboratory environments. Test and measurement vendors have extended signal analyzer capabilities to validate EHF and millimeter-wave performance across 5G infrastructure, aerospace platforms, and satellite communications, providing engineering teams with the instrumentation needed to de-risk design cycles. Simultaneously, standardization initiatives are formalizing the technical parameters for ultra-high-speed links, creating a clearer roadmap for interoperable products and accelerating commercial confidence.
These advancements are not occurring in isolation. The push toward multi-gigabit wireless connectivity has spurred innovation in radio design, relay architectures, and over-the-air testing methodologies. Organizations that can deliver validated high-frequency components with predictable performance characteristics are finding increasing demand from network operators, defense primes, and aerospace integrators who require reliable EHF subsystems for mission-critical applications. The compounding effect of better validation tooling, standardized performance targets, and improved component design is shrinking the gap between concept and commercial deployment.
Policy, Spectrum Allocation, and Regulatory Alignment
Policy and regulatory dynamics are functioning as both an enabler and a structuring force for EHF market growth. National regulators continue to refine frequency allocations for the EHF band, ensuring that communications, radar, and scientific use cases operate within clearly defined boundaries. The FCC's ongoing maintenance of its online frequency allocation table illustrates the importance of regulatory clarity for companies planning long-cycle product development and network rollout strategies. At the same time, licensing requirements for satellite communications and terrestrial systems above certain thresholds introduce a compliance layer that favors organizations with robust regulatory engagement and spectrum management capabilities.
Worldwide Over-the-horizon Radar Market
International bodies are also contributing to a more coherent global framework. Updated ITU-R recommendations have reinforced the nomenclature and technical definition of the EHF band, while IEEE working groups continue to advance standards that support high-throughput links in specific high-frequency ranges. This convergence of national and international coordination is reducing ambiguity for multinational deployments and creating a more predictable environment for suppliers that need to serve multiple jurisdictions. For market participants, regulatory alignment is increasingly a competitive advantage, not merely a compliance obligation.
Demand-Side Transformation Across End-Use Verticals
Demand for EHF technology is being driven by structural changes in how organizations approach connectivity, sensing, and secure communications. Telecommunications operators are expanding high-capacity wireless networks to address congestion, latency, and capacity constraints, with a growing number of operators actively investing in millimeter-wave and EHF-enabled infrastructure. Recent industry reporting indicates broad global participation, with dozens of operators across multiple continents pursuing network deployments and a meaningful subset having moved into commercial launch phases. This demand is not limited to urban densification; it also extends to backhaul, fixed wireless access, and coverage expansion strategies that rely on high-frequency relays to overcome propagation limitations.
In parallel, the automotive and transport sector is exploring EHF's role in advanced sensing, vehicle-to-infrastructure communication, and next-generation platform connectivity. Aerospace and defense organizations continue to prioritize protected, jam-resistant communications for strategic and tactical operations, sustaining demand for EHF satellite communications payloads, ground segments, and tactical terminals. Healthcare and security applications are also contributing incremental demand, particularly where high-frequency sensing, imaging, and secure data transmission offer performance advantages over lower-frequency alternatives. The diversity of demand sources is an important stabilizing factor, reducing dependence on any single vertical's procurement cycle.
Supply Chain Evolution and Cost Structure Dynamics
Supply chain and cost dynamics are undergoing a recalibration as EHF moves from specialized prototyping toward broader commercialization. Early-stage development was characterized by high unit costs, limited component availability, and long integration timelines. As the technology base matures, suppliers are investing in more repeatable manufacturing approaches, broader test coverage, and modular subsystem designs that reduce customization overhead. At the same time, the hardware bottleneck around power efficiency, interconnection loss, and thermal management is prompting more collaboration between component manufacturers, integrators, and test providers to optimize the full signal chain rather than individual elements in isolation.
Cost structures are also being influenced by the increasing importance of validation and certification. High-frequency systems require rigorous over-the-air testing and signal integrity verification, and providers that can deliver integrated test and measurement capabilities are helping customers compress development timelines. In effect, the supply chain is becoming more service- and validation-intensive, with value shifting toward organizations that can ensure performance across the entire deployment lifecycle. This shift favors ecosystems that combine hardware, software, and services rather than point-solution vendors operating in silos.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The EHF market is anchored by a set of established organizations with strong positions in defense communications, aerospace systems, and advanced test infrastructure. Major defense and aerospace primes have built durable advantages through long-standing roles in protected satellite communications programs, EHF payload development, and tactical terminal supply. Their differentiation stems from the ability to deliver systems that meet stringent reliability, security, and interoperability requirements, often across multi-year programs of record. These organizations benefit from deep systems integration capabilities, established procurement relationships, and experience navigating the regulatory and certification demands associated with high-frequency defense applications.
A second competitive cluster is formed by test, measurement, and validation specialists. These companies provide EHF-capable signal analysis platforms, over-the-air testing environments, and high-frequency validation tools that support 5G, aerospace, defense, and satellite communications development. Their strategic positioning is defined by technical breadth, measurement accuracy, and the ability to support customers across the design, production, and deployment phases. As EHF adoption broadens beyond defense and into commercial telecommunications and automotive use cases, these players are increasingly important as enablers of cost-effective development and risk reduction. Their advantage lies in helping customers translate high-frequency theory into repeatable, field-ready performance.
A third group includes telecommunications equipment developers, millimeter-wave radio providers, and satellite communications firms expanding into higher-frequency bands. These organizations are pursuing more commercially oriented strategies, emphasizing point-to-point wireless connectivity, coverage extension relays, and high-capacity satellite architectures that extend into EHF-related spectrum. Their differentiation often centers on deployment practicality, scalability, and the ability to integrate high-frequency radios into existing network architectures. Recent field deployments illustrate this commercial trajectory, with relay-based approaches used to materially expand millimeter-wave coverage in dense urban environments, moving coverage levels from partial to near-complete in targeted zones.
The competitive landscape is evolving along multiple axes. Consolidation remains a plausible path for organizations seeking to combine end-to-end capabilities across components, subsystems, test, and services. At the same time, fragmentation is likely in specialized niches such as EHF security screening, high-frequency component fabrication, and proprietary relay or terminal designs. New entrants are most likely to succeed by addressing specific bottlenecks rather than attempting to compete head-to-head across the full stack. The recent acceleration in global operator activity around millimeter-wave and EHF-adjacent deployments is expanding the total addressable opportunity, but it also raises the bar for integration readiness, regulatory compliance, and field validation. Companies that can demonstrate proven performance in live environments while maintaining cost discipline will be best positioned to capture share as the market scales.
Forward-Looking Trends: The Next Three to Five Years
Over the next several years, the EHF market is likely to be defined by three interrelated trends. First, high-frequency connectivity will move further into mainstream deployment as operators and enterprises convert pilot activity into scaled rollouts. The growing number of operators investing in millimeter-wave and EHF-adjacent networks suggests that coverage expansion, backhaul augmentation, and high-capacity fixed wireless access will become more common use cases. This creates a widening opportunity for relay technologies, compact terminal designs, and integration services that reduce deployment friction in dense or challenging environments.
PW Consulting
Second, standardization and regulatory coordination will increasingly shape commercial architectures. As ITU-R designations, IEEE specifications, and national licensing frameworks become more detailed, products that are designed from the outset for compliance and interoperability will gain preference in procurement processes. The effect will be a market that rewards engineering rigor and documentation discipline, particularly for suppliers serving multiple regions or working on systems that must interface with both terrestrial and satellite infrastructures. Organizations that treat regulatory alignment as a design parameter rather than a post-development checklist will have a clearer path to international scaling.
Third, the hardware bottleneck narrative will shift from pure performance to integrated efficiency. Improvements in power amplifier design, interconnection loss reduction, and thermal management will remain critical, but competitive differentiation will increasingly depend on how well these elements are optimized together within complete subsystems. This favors collaborative development models and vertically coordinated offerings that can deliver validated performance at the system level. At the same time, supply chain and cost pressures will require disciplined scaling strategies, especially for companies planning to serve both defense and commercial markets with overlapping component bases. The principal risk is that expectations for rapid commercialization outpace the pace of hardware maturity, creating pockets of performance unpredictability or deployment delay. Organizations should therefore balance growth ambitions with realistic validation timelines and ensure that test and measurement capabilities are embedded early in product planning.
Actionable Recommendations for Decision-Makers
Manufacturers and technology developers should prioritize system-level validation and interoperability alongside component performance. The most durable competitive advantages will belong to organizations that can demonstrate reliable EHF behavior across thermal, spectral, and integration constraints while meeting the documentation and compliance needs of multi-region customers. Investing in test coverage, modular architecture, and clear certification pathways will reduce time-to-market risk and improve positioning in both defense and commercial procurement environments.
Investors and strategic financiers should assess not only technical promise but also the maturity of the surrounding ecosystem. Companies that are tightly coupled to validated end-use demand, regulatory clarity, and repeatable test and deployment processes are better insulated from the volatility that often accompanies high-frequency technology cycles. Attention to supply chain resilience, thermal and power efficiency roadmaps, and the ability to serve multiple verticals from shared platforms can provide stronger indicators of sustainable scaling than headline performance claims alone.
Procurement leaders and enterprise buyers should evaluate EHF solutions based on deployment readiness, integration complexity, and long-term support rather than peak specification sheets. Proven field performance, interoperability with existing infrastructure, and the supplier's ability to navigate licensing and spectrum requirements are increasingly decisive factors. Organizations that build early relationships with experienced test, integration, and compliance partners will be better positioned to adopt EHF capabilities with controlled risk and predictable scaling trajectories.
Terahertz (THz) Technology Market
The EHF technology market is transitioning from specialized capability to broad strategic relevance, and the organizations that navigate this shift most effectively will be those that combine technical precision with clear go-to-market discipline. For decision-makers seeking deeper segmentation data, detailed regional demand patterns, and tailored strategic recommendations aligned to specific product portfolios or investment theses, the full PW Consulting research report provides the granular intelligence needed to convert these market-level insights into actionable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Extremely High Frequency (EHF) Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com