

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global Ceramic Core for Gas Turbine Market 2026: Why a 5.8% CAGR Reshapes the Aerospace Landscape

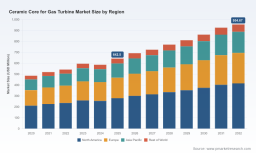
Strategic Shifts and Commercial Opportunities in the Global Ceramic Core for Gas Turbine Market
Market Landscape and Structural Challenges
The global market for ceramic cores used in gas turbine manufacturing has demonstrated steady expansion over the past half-decade, reaching approximately 642.5 million USD in 2025. The trajectory from 2020 through 2025 reflects a consistent upward curve, driven by escalating turbine production volumes and the persistent transition toward higher-performance casting methodologies. Annual growth has averaged a compound rate of 5.82 percent, a figure that underscores the sector's resilience even amid broader industrial volatility. Looking ahead, the forecast period through 2032 indicates continued momentum, with revenue projections climbing toward the 954 million USD threshold by the final forecast year. This sustained expansion is not merely a reflection of volume growth; it signals a deeper structural shift in how turbine components are engineered, cast, and validated.
Behind these headline figures lies a market characterized by pronounced demand concentration in aerospace engine applications, where precision and thermal stability dictate strict performance thresholds. The aerospace segment continues to anchor the majority of revenue, reflecting the integral role ceramic cores play in producing single-crystal and directionally solidified turbine blades. Industrial gas turbine applications follow as a substantial secondary demand pillar, particularly as power generation and combined-cycle facilities seek incremental efficiency gains through advanced casting techniques. Regionally, North America and Europe maintain dominant share positions, anchored by established aerospace supply chains and mature manufacturing infrastructure, while Asia Pacific and other regions are steadily expanding their footprint, albeit from a smaller base.
PW Consulting
Three structural challenges currently define the market's inflection point. First, the industry faces an intensifying cost-pressure environment driven by raw material volatility and stringent processing requirements. Materials such as zircon sand and high-purity zirconia exhibit significant price fluctuations, with annual swings exceeding twenty percent in certain periods. Premium-grade formulations can command pricing multiples well above silica-based alternatives, while simultaneously requiring energy-intensive sintering processes and ultra-precise dimensional tolerances. Second, certification and quality assurance frameworks have grown increasingly rigorous, with aerospace and industrial turbine components demanding compliance to AS9100 and ISO 9001 standards that govern dimensional accuracy, leachability, and metallurgical compatibility. These requirements raise the barrier for new entrants and place a premium on manufacturers with proven production track records. Third, the market is undergoing a technological bifurcation: traditional silica and alumina cores remain widely deployed, but additive manufacturing and novel ceramic compositions are introducing new capability sets that challenge incumbent production paradigms. Companies that fail to integrate precision molding, advanced material chemistry, or digital fabrication processes risk losing relevance in a segment where performance margins translate directly into competitive advantage.
Key Drivers Accelerating Market Evolution
Technological innovation in ceramic material science and fabrication methods stands as the primary catalyst reshaping the market. The push toward higher turbine operating temperatures has intensified the need for internal cooling architectures that are only feasible when ceramic cores can be manufactured with intricate, high-fidelity geometries. Traditional slurry casting and injection molding techniques have matured considerably, but emerging additive manufacturing approaches are unlocking multi-wall core designs and complex cooling channels that were previously impractical to produce. These manufacturing shifts are not incremental; they fundamentally alter the performance envelope of turbine blades and vanes, enabling higher thermal efficiency, improved fuel economy, and reduced emissions. Manufacturers investing in precision injection, extrusion, and 3D-printed core technologies are positioning themselves to capture demand from next-generation engine programs that prioritize extreme temperature tolerance.
Policy and regulatory dynamics serve as a second powerful driver, particularly within aerospace certification frameworks and environmental efficiency mandates. Stringent quality standards have become non-negotiable gatekeepers for market participation. Components destined for modern gas turbines must satisfy rigorous dimensional and material compatibility requirements, and certification pathways that validate leachability, thermal stability, and repeatability are increasingly embedded into procurement specifications. Simultaneously, emissions regulations and efficiency targets across aviation and power generation sectors are pushing turbine designers toward architectures that operate at higher cycle temperatures. This regulatory tailwind translates directly into demand for advanced ceramic cores that can withstand more extreme casting environments without compromising integrity. Companies aligning their production processes with certified quality systems and investing in traceability infrastructure are gaining preferential positioning in OEM supply chains.
Gas Turbine Market
Demand-side behavior is evolving as turbine OEMs and casting partners recalibrate their sourcing strategies. Rather than viewing ceramic cores as commoditized consumables, leading manufacturers increasingly treat them as critical performance enablers tied directly to blade yield, scrap reduction, and component reliability. This shift has elevated the importance of supplier collaboration, with casting operations seeking partners capable of delivering custom geometries, rapid iteration cycles, and integrated technical support. The aerospace sector, in particular, is placing greater emphasis on suppliers that can accommodate complex single-crystal and directionally solidified casting workflows while maintaining consistent dimensional accuracy across production batches. Industrial gas turbine buyers, meanwhile, are prioritizing supply reliability and scalability, especially as power generation fleets modernize and expand operating hours.
Supply chain and cost structure dynamics add further complexity to the demand picture. Raw material pricing volatility, particularly for zirconia-based inputs and processing consumables, continues to influence margin structures and procurement strategies. Fluctuations in zircon sand pricing, for example, have introduced periodic cost uncertainty that ripple through core manufacturing operations. At the same time, energy-intensive sintering processes and high-temperature processing requirements accentuate the importance of production efficiency and thermal process optimization. Manufacturers that invest in material sourcing diversification, process automation, or energy-efficient furnace technologies are better positioned to absorb input cost variability and maintain competitive pricing without sacrificing quality.
Competitive Landscape and Strategic Positioning
The competitive environment in this market reflects a blend of specialized niche players and integrated casting organizations. Several leading firms have built their positioning around deep expertise in precision ceramic core design, with capabilities spanning silica-based, alumina-based, and zircon-based compositions. These companies emphasize decades of experience in investment casting support, offering cores engineered for high-temperature stability and tailored to the intricate geometries required for turbine airfoils. Their strategic advantage typically stems from tight integration with casting workflows, including proprietary molding techniques, slurry casting expertise, and the ability to produce cores with minimal geometric constraints. Such capabilities reduce downstream casting complexity and improve yield rates, making these suppliers valuable partners for high-performance turbine programs.
A second competitive cluster is defined by firms that have embedded ceramic core production within broader superalloy casting operations. For these organizations, ceramic cores are not standalone products but integral enablers of turbine airfoil manufacturing, supporting equiaxed, directionally solidified, and single-crystal component production across aerospace and industrial applications. This vertical integration allows for tighter control over core quality, lead times, and material compatibility, while also providing leverage in long-term OEM relationships. Companies in this segment often prioritize certifications, repeatability, and technical collaboration, recognizing that core performance directly influences blade metallurgy and final component reliability.
Market dynamics also reveal a growing emphasis on additive and digitally enabled fabrication. Recent developments highlight the emergence of new production footprints and technology demonstrations focused on ceramic additive manufacturing for multi-wall cores and complex cooling architectures. Facility investments in regions with established aerospace and advanced manufacturing ecosystems signal a strategic push to scale these capabilities for serial production. At the same time, trade show showcases featuring 3D-printed ceramic casting cores for single-crystal turbine blades illustrate mounting interest in digital fabrication's ability to deliver intricate internal channel designs with production-ready throughput. These developments suggest that additive and hybrid manufacturing approaches are transitioning from experimental interest to operational consideration, particularly for programs that demand higher thermal margins and geometric complexity.
Looking at the broader competitive trajectory, the market is experiencing both consolidation and fragmentation forces. Larger integrated players continue to strengthen their positions through certification maturity, process reliability, and long-term supply relationships. At the same time, specialized niche manufacturers are differentiating through custom core design, advanced material formulations, and agile production models. New entrants with additive manufacturing expertise are introducing alternative value propositions, particularly for programs that prioritize design flexibility and rapid prototyping. As the market matures, competitive advantage will likely shift from pure volume scale toward capability depth: suppliers that combine certified quality systems, material science expertise, and digitally enabled production will capture disproportionate share in high-value aerospace and advanced industrial turbine segments.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The first major trend is the accelerating adoption of digitally enabled and additive-manufactured ceramic cores as complement to, and in some cases replacement for, traditional molding methods. As turbine designs push toward more aggressive cooling architectures and higher thermal limits, the ability to produce multi-wall cores and complex internal geometries with repeatable precision will become increasingly valuable. Companies that successfully industrialize these processes at scale will unlock new program opportunities, while those that treat additive methods as purely experimental risk falling behind in high-performance segments where geometry directly dictates efficiency outcomes.
The second trend is the ongoing premiumization of advanced material formulations. Zirconia-based and other high-performance ceramic compositions are expected to retain pricing advantages due to their superior thermal stability and compatibility with extreme casting conditions, even as raw material volatility and production costs remain elevated. Demand for these premium cores will likely grow in aerospace and select industrial applications where operating temperature margins justify higher input costs. Manufacturers that can manage material sourcing risk, optimize sintering processes, and demonstrate consistent quality will be best positioned to capture this value differentiation.
The third trend centers on supply chain resilience and certification-driven procurement. Procurement teams are increasingly prioritizing suppliers with robust quality systems, traceability, and proven compatibility with superalloy casting workflows. This shift raises the importance of long-term supplier relationships and technical alignment, particularly for programs that require tight tolerances and low scrap rates. At the same time, geographic diversification of production capacity is becoming a strategic consideration as OEMs seek to mitigate supply disruptions and support regional manufacturing mandates. The risk lies in overreliance on single-source suppliers or uncompensated material price swings, which can pressure margins and disrupt program timelines. Companies that build resilient sourcing strategies, invest in certification readiness, and maintain flexible production capabilities will be better equipped to navigate these uncertainties.
Strategic Implications for Decision Makers
For turbine component manufacturers and casting operations, the priority is to align ceramic core sourcing with long-term performance roadmaps rather than short-term cost minimization. Evaluating suppliers based on certification maturity, geometric capability, and collaboration readiness can reduce downstream casting risk and improve yield consistency across complex blade and vane programs. Investing in technical partnerships that support custom core design and iterative prototyping will pay dividends as turbine architectures become increasingly dependent on precise internal cooling features.
For investors and corporate strategy teams, the market presents attractive exposure to high-value manufacturing technologies with structural demand tailwinds. The combination of efficiency mandates, certification-driven procurement, and emerging additive capabilities suggests continued growth, but returns will likely concentrate among firms with differentiated material expertise, scalable precision processes, and strong OEM relationships. Due diligence should focus on production capability depth, certification status, and the ability to manage raw material cost variability while maintaining margin resilience.
For procurement and supply chain leaders, diversification and qualification readiness are critical. Relying heavily on a narrow supplier base or cost-driven sourcing without assessing thermal and dimensional performance alignment can introduce program risk. Establishing multi-supplier qualification pipelines, monitoring material price dynamics, and securing committed capacity for high-complexity core geometries will help safeguard production continuity as demand scales. For organizations seeking deeper segmentation data, regional demand mapping, and tailored sourcing or investment scenarios, accessing comprehensive market research can provide the granularity required to convert these directional insights into precise action plans.
Worldwide Gas Turbine Turbine Blades Market
For detailed analysis of this topic, please visit the official page: Worldwide Ceramic Core for Gas Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com