

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Industrial Grade Ammonium Pentaborate Market: Why Asia Pacific Hubs Drive 4.15% Growth

Navigating the Industrial Grade Ammonium Pentaborate Market: Strategic Trends and Commercial Opportunities Through 2032
The global industrial grade ammonium pentaborate market has demonstrated steady expansion over the past half-decade, reaching a valuation of approximately 195.5 million USD in the base year of 2025. Tracing its trajectory from 2020 through 2025 reveals a compound growth pattern that reflects both cyclical industrial demand and the material's entrenched role in high-performance applications. Looking ahead, the forecast window extending to 2032 projects continued upward momentum, with market size expected to cross the 259.86 million USD threshold by the end of the period. This translates to a compound annual growth rate of 4.15 percent, a figure that underscores moderate but reliable expansion in a sector characterized by specialized use cases, technical barriers to entry, and evolving regulatory expectations.
At a macro level, the market's resilience stems from its dual identity as both a commodity-adjacent chemical and a performance-critical additive. Manufacturers rely on ammonium pentaborate for functions ranging from thermal stabilization to surface passivation, and this functional diversity buffers the supply chain against single-sector downturns. The base year valuation of 195.5 million USD, coupled with a steady climb through the mid-2020s, indicates that end-user industries have absorbed the material into their standard operating procedures rather than treating it as a discretionary input. Even as broader chemical markets face pricing volatility and intermittent demand shocks, ammonium pentaborate has maintained a recognizable growth rhythm, with year-over-year increments reflecting incremental capacity additions, downstream application broadening, and the gradual substitution of older formulations in targeted niches.
However, the market is not insulated from structural friction. Three interconnected challenges define the current inflection point for producers, distributors, and downstream formulators. First, raw material cost dynamics and feedstock availability remain a persistent variable. Borate-based production depends on a tightly linked supply chain, and even modest fluctuations in upstream pricing or logistics constraints can cascade into margin compression for manufacturers operating on tight bid-ask spreads. Second, the regulatory environment is tightening around boron-containing compounds, with safety classifications, concentration thresholds, and regional risk management frameworks adding compliance layers that raise the cost of market participation. Third, demand-side concentration has become a double-edged sword. While reliance on established industrial applications provides stability, it also limits the pace of volume growth unless new use cases are successfully commercialized or existing applications experience meaningful specification upgrades. These factors combined create a market that rewards operational precision and penalizes complacency.
PW Consulting
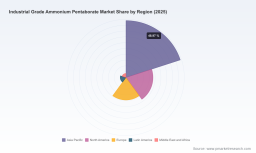
Geographic distribution further illustrates the market's structure. Asia Pacific accounts for the largest regional share, followed by North America and Europe, with Latin America and the Middle East and Africa contributing smaller but strategically relevant volumes. This footprint reflects broader industrial geography: manufacturing intensity, electronics production hubs, and mature flame retardant demand clusters shape where ammonium pentaborate is consumed most heavily. Yet the regional hierarchy is not static. Shifts in electronics supply chains, local content requirements, and regional chemical policy are gradually reshaping where capacity is located and where procurement decisions are made. For decision-makers, the key takeaway is that regional demand is both a reflection of existing industrial base and a target for future investment, making geographic positioning a strategic variable rather than a passive outcome.
Key Drivers Reshaping Market Trajectory
Technological Innovation and Application-Level Performance Gains
Advancement in downstream applications remains one of the most reliable engines of demand for industrial grade ammonium pentaborate. In electronics manufacturing, the material's role in electrolytic capacitors and related components ties its consumption directly to the health of consumer electronics, industrial automation, and power electronics supply chains. As device architectures become more demanding in terms of thermal management, longevity, and electrical stability, formulators increasingly seek chemical inputs that deliver consistent performance under tighter tolerances. Ammonium pentaborate's ability to contribute to stabilization, buffering, and flame resistance positions it within this performance-driven upgrade cycle.
Equally important is the material's expanding relevance in flame retardant formulations. Fire safety standards across multiple industries continue to evolve, and manufacturers are under pressure to meet stricter flammability requirements without compromising mechanical properties or processability. This creates incremental demand for specialized boron-based additives, particularly where formulators aim to balance cost, efficacy, and regulatory acceptability. In parallel, metal surface treatment applications continue to benefit from the material's role in passivation and corrosion mitigation, supporting demand from sectors where surface integrity directly affects product lifespan and warranty exposure.
The innovation dynamic is not limited to end-use performance. Producers are also refining manufacturing processes, grade consistency, and packaging formats to better serve batch-sensitive and quality-driven customers. As specifications become more exacting, suppliers that can demonstrate reproducibility, low impurity profiles, and reliable technical support gain a meaningful advantage. This is especially true for customers in electronics and specialty coatings, where material variability can create downstream quality issues that are costly to resolve.
Policy and Regulatory Environment as a Structural Force
Regulatory developments are increasingly shaping how ammonium pentaborate is marketed, handled, and differentiated. Classification frameworks for boron-containing substances have become more detailed, with specific concentration limits and hazard communication requirements influencing formulation choices and procurement standards. In some jurisdictions, risk management scoping for boric acid, its salts, and related precursors has prompted industry participants to reassess exposure pathways, documentation practices, and product stewardship obligations.
At the same time, trade policy and tariff structures are affecting regional competitiveness. Import duties on certain ammonium pentaborate categories can alter the economics of cross-border sourcing, particularly when tariffs differ materially by country of origin. For manufacturers and buyers alike, this means that sourcing decisions are no longer purely about price per unit. They now incorporate compliance risk, tariff exposure, and the strategic value of supply continuity. In practice, these regulatory and tariff dynamics are encouraging more deliberate sourcing strategies, including greater attention to supplier documentation, region-specific certifications, and alternative supply pathways where feasible.
For the market as a whole, regulation functions as both a constraint and a filter. It raises the bar for entry and can increase operating costs, but it also rewards established players with strong compliance capabilities and technical documentation. In a market where concentration among leading suppliers is already significant, regulatory complexity tends to reinforce the position of incumbents that can absorb compliance-related overhead more efficiently than smaller or less-resourced competitors.
Demand-Side Shifts and the Value of Reliability
End-user behavior is moving toward greater emphasis on supply reliability, specification consistency, and technical support. In sectors where ammonium pentaborate is used in critical formulations, downtime or quality deviations are expensive, and procurement teams increasingly favor suppliers that can offer predictable delivery, transparent lot traceability, and responsive service. This preference is especially pronounced where downstream customers operate just-in-time production models or where chemical inputs feed into high-value finished goods.
There is also a gradual shift in how buyers evaluate cost. Rather than focusing solely on unit price, many industrial purchasers are weighing total cost of ownership, including handling requirements, compliance documentation, formulation compatibility, and risk of supply interruption. This trend favors suppliers that can position ammonium pentaborate not merely as a commodity chemical but as a supported component within the customer's broader process. In practice, the winners in this environment are those that combine competitive pricing with dependable quality and clear communication around product characteristics and handling requirements.
Industrial Ammonium Sulfate Market
Supply Chain and Cost Structure Dynamics
Cost structures across the value chain remain sensitive to upstream borate feedstock conditions. Boric acid, a primary input for ammonium pentaborate production, has experienced periodic price softness in certain recent intervals as supply conditions stabilized and downstream demand remained cautious. At the same time, broader borax pricing in key markets has reflected a mix of month-to-month declines and year-over-year increases, illustrating the uneven rhythm of commodity-driven inputs. These fluctuations matter because they affect manufacturing margins and can influence the timing of price adjustments downstream.
Supply chain resilience has therefore become a central concern. Producers and buyers are both paying closer attention to logistics reliability, inventory planning, and the geographic distribution of production assets. In a market where lead times, shipping constraints, and regional demand spikes can quickly alter availability, the ability to manage working capital and maintain buffer inventory can be as important as the base production cost itself. This environment encourages longer-term supplier relationships and, in some cases, more structured agreements that reduce uncertainty for both sides.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated competitive structure, with a core group of established suppliers holding a substantial share of global activity. This concentration reflects the technical and operational requirements of producing industrial grade ammonium pentaborate at scale, as well as the importance of reliability in serving demanding downstream sectors. Several companies have built recognizable positions by combining feedstock access, application-specific product knowledge, and steadily expanded production capability.
U.S. Borax, operating from California and leveraging world-class borate mine operations, stands out as a major global producer with a broad portfolio of borate products. Its positioning emphasizes scale, supply security, and the ability to serve multiple industrial end uses, including stabilization, fire retardant applications, and specialty industrial formulations. For customers, this translates into a supply partner with deep resource backing and the capacity to support large-volume or long-term requirements.
Larderello Group, based in Italy, has built its profile around the Larderel® ammonium pentaborate line, with emphasis on flame retardant and buffering applications. Its strategy reflects a focus on performance-oriented product branding and application-specific value proposition, appealing to customers that prioritize consistent chemical behavior and established formulation compatibility.
In India, DMCC Specialty Chemicals and Shravan Chemicals both operate as manufacturers and exporters of ammonium pentaborate for industrial use, with attention to specialty applications and international supply. Chemical Bull Pvt. Ltd. serves as a bulk supplier for manufacturing requirements, emphasizing volume availability and broad customer access. Together, these players illustrate the importance of India as a production and export base, where cost-competitive manufacturing and export orientation can support both regional and overseas demand.
Addenda Chemicals, based in Israel, and Spectrum Chemical Manufacturing Corporation, located in New Jersey, round out the landscape with supplier and manufacturer profiles that target industrial applications and, in Spectrum's case, expanded capacity for flame retardant and other industrial sectors. Spectrum's offering of both industrial and tetrahydrate grades highlights the market's sensitivity to product format, where different grades can serve distinct handling, formulation, or performance requirements.
The strategic differentiation among these companies often comes down to a few recurring themes. Some compete primarily on scale and supply assurance, leveraging resource integration or large production footprints. Others compete on product specification, grade variety, and application support, aiming to capture customers who value reproducibility and technical service. A third group competes on accessibility and responsiveness, positioning as flexible suppliers for buyers who need reliable availability in measured quantities or shorter timeframes.
Market evolution is increasingly shaped by these differing strategic postures. Consolidation dynamics are visible where scale, compliance capability, and supply chain control provide advantages that are difficult for smaller players to replicate quickly. At the same time, fragmentation persists in segments where regional demand, specialty grades, and export opportunities allow smaller manufacturers to remain relevant. New entrants face real barriers, not only from established supply relationships but also from the need to demonstrate consistent quality, regulatory readiness, and dependable logistics. As a result, the landscape is likely to continue favoring players that can combine operational reliability with clear application value, while incremental consolidation may occur around suppliers that can capture broader service relationships and multi-grade portfolios.
Future Trends and Commercial Implications
Over the next three to five years, one of the most important trends will be the continued alignment of ammonium pentaborate demand with performance-driven industrial applications. Electronics-related usage and flame retardant requirements are expected to remain central, but growth will likely be strongest where end users upgrade specifications or where formulation changes create new demand for boron-based functionality. In practical terms, this means that commercial opportunity will increasingly belong to suppliers and buyers who can anticipate specification shifts rather than simply respond to them.
A second trend is the growing importance of regulatory and trade-aware sourcing. As classification standards, regional risk management frameworks, and tariff structures continue to influence procurement economics, companies will place greater weight on documentation, traceability, and supply chain design. This creates opportunities for suppliers with strong compliance infrastructure and for buyers who diversify sourcing strategies to reduce exposure to single-region dependencies or tariff-sensitive pathways. The commercial implication is that procurement agility will become a competitive advantage, especially for organizations that must balance cost control with continuity risk.
A third trend is the gradual shift from purely transactional purchasing toward more relationship-based supply arrangements. As customers prioritize lot consistency, technical support, and delivery predictability, suppliers that can provide reliable service and application-relevant information will be better positioned to retain business and defend margin. For producers, this suggests value in strengthening technical communication, quality assurance processes, and customer-facing support. For buyers, it suggests value in building longer-term partner relationships rather than relying solely on spot-market comparisons.
These trends carry both opportunity and uncertainty. Demand growth is likely to remain moderate rather than explosive, which means that outsized gains will depend on execution quality, regional positioning, and the ability to capture higher-value segments. Regulatory evolution could raise compliance costs or alter formulation preferences in ways that reshape demand patterns. Feedstock pricing and logistics conditions will continue to introduce variability, and trade policy changes could shift the relative attractiveness of different sourcing routes. Companies that prepare for this environment by strengthening supply resilience, clarifying application value, and maintaining compliance readiness will be better placed to convert moderate market growth into durable commercial returns.
Strategic Actions for Decision-Makers
For manufacturers and producers, the priority is to reinforce operational reliability while sharpening product differentiation. This means investing in grade consistency, quality documentation, and application support that helps customers integrate the material with confidence. Where possible, expanding capacity in targeted grades or formats can create room to serve higher-specification demand and reduce exposure to purely price-based competition. Equally important is maintaining visibility into upstream feedstock conditions and logistics risk, since margin protection in this market often depends on anticipating cost movements before they become acute.
For investors and strategic buyers, the market's moderate growth profile calls for disciplined evaluation of competitive positioning rather than assumptions of rapid volume expansion. Value creation is likely to come from suppliers with strong compliance capability, dependable supply chains, and clear relationships with downstream application sectors. Due diligence should therefore focus on production reliability, regulatory readiness, customer concentration, and the ability to serve performance-sensitive segments. Opportunities may also arise in regions where industrial demand is expanding or where trade and sourcing dynamics create relative advantages for locally positioned producers.
For procurement and supply chain leaders, the most effective approach is to treat ammonium pentaborate as a strategically managed input rather than a routine purchase. This includes evaluating suppliers on total cost, specification reliability, and continuity risk, as well as building contractual or relational buffers where supply interruption would be costly. Diversifying sourcing pathways, monitoring regional tariff and regulatory changes, and maintaining clear internal specifications can reduce exposure to sudden market shifts. In a market where consistency and support increasingly matter, procurement decisions should reflect not only price but also the probability of uninterrupted, specification-compliant supply.
Industrial Grade Borated Polyethylene Materials Market
Detailed segment data, regional breakdowns, and company-level competitive benchmarks can further sharpen these decisions. Organizations seeking a fuller picture of volume trajectories, application-specific demand patterns, and sourcing trade-offs will benefit from a more comprehensive review of the market's structure and forward indicators. For those evaluating capacity investments, supplier selection, or long-range procurement strategy, deeper intelligence provides the context needed to move from general market awareness to precise, actionable planning.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Grade Ammonium Pentaborate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com