

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Waterproofing Membrane Market: How Asia Pacific's 4.94% CAGR Growth Pathway Redefines 2032 Outlook

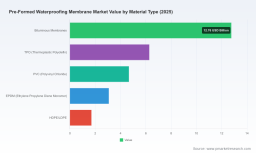
Strategic Trends and Commercial Opportunities in the Global Pre-Formed Waterproofing Membrane Market
Market Overview and Core Challenges
The global pre-formed waterproofing membrane market has demonstrated steady expansion over the past half-decade, growing from approximately USD 22.8 billion in 2020 to an estimated USD 28.5 billion in 2025. This trajectory reflects a compound annual growth rate of 4.94 percent through the forecast horizon extending to 2032. While the expansion appears linear at first glance, the underlying dynamics reveal a maturing industry navigating structural shifts in construction practices, material science, and regulatory expectations. Understanding these nuances is essential for executives positioning their organizations within this competitive space.
One of the most pressing challenges facing the industry is the persistent volatility in raw material costs. Ethylene and propylene feedstock prices have remained unstable, directly affecting the production economics of polymer-based membranes such as TPO, PVC, and EPDM. In April 2026, EPDM rubber prices reached USD 3.08 per kilogram in Northeast Asia, marking a 19.4 percent increase, while European and North American markets faced rises of 12.8 percent and 21.1 percent respectively. Such fluctuations compress margins for manufacturers who lack hedging mechanisms or diversified supply chains, forcing difficult trade-offs between pricing competitiveness and profitability.
A second critical inflection point lies in the regulatory environment. Increasing emphasis on sustainable construction standards and green building certifications is reshaping procurement criteria across commercial and infrastructure projects. Developers and general contractors are prioritizing materials with lower environmental footprints, reduced volatile organic compound emissions, and longer service lives. This shift pressures traditional bituminous membrane producers to accelerate innovation while creating openings for advanced polymer and hybrid systems. Companies that fail to align their portfolios with these evolving standards risk marginalization in premium segments.
The third challenge involves the fragmentation of supply and the uneven pace of technological adoption. While the market remains moderately concentrated, with the top three players accounting for roughly 28.5 percent of revenue and the top five reaching 42.3 percent, regional disparities persist. Emerging markets demand cost-effective solutions that balance performance with affordability, while developed economies emphasize technical specifications and compliance. Bridging this gap requires localized manufacturing strategies, customized product development, and agile distribution networks that many mid-tier players struggle to maintain.
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Performance
Advancements in polymer chemistry and membrane engineering are fundamentally altering the value proposition of pre-formed waterproofing solutions. Next-generation polymer-modified bituminous systems and fully bonded TPO/FPO sheet membranes now offer improved tensile strength, superior adhesion under demanding substrate conditions, and enhanced resistance to chemical exposure. Manufacturers such as Sika AG have expanded advanced polymer-modified production capacity in Europe and North America to meet growing demand from infrastructure and commercial construction, signaling the strategic importance of performance differentiation. Similarly, SOPREMA Group recently strengthened its product portfolio with next-generation polymer-modified membranes designed for both roofing and underground applications, underscoring how material science directly translates into competitive advantage.
These innovations are not merely incremental upgrades. They enable builders to address complex waterproofing challenges in blindside applications, high-humidity environments, and structures with stringent durability requirements. For decision-makers, this means evaluating membranes based on lifecycle performance rather than initial installed cost. The ability of a membrane to maintain integrity over decades of exposure reduces maintenance expenditures, minimizes liability risks, and supports asset valuation—a narrative that resonates strongly with property developers and infrastructure investors.
Policy and Regulatory Environment
Regulatory frameworks worldwide are increasingly mandating higher performance thresholds for building envelopes and below-grade structures. Green building certification programs, energy efficiency codes, and environmental compliance standards are pushing specifiers toward membranes that deliver consistent waterproofing protection while aligning with sustainability objectives. The growing focus on environmentally friendly pre-formed sheet membranes with reduced environmental impact is reshaping product roadmaps and procurement guidelines. Manufacturers that proactively certify their products against recognized standards and provide transparent environmental product declarations gain a tangible edge in competitive bidding processes.
Policy-driven demand is particularly pronounced in public infrastructure projects, where lifecycle costing and long-term maintenance considerations carry significant weight. Regulations that require extended warranty periods or stricter waterproofing performance criteria for tunnels, bridges, and reservoir structures create structural demand for high-reliability membranes. This environment favors established players with robust quality assurance systems and documented installation protocols, while simultaneously encouraging new entrants that bring specialized formulations to niche applications.
Demand-Side Shifts in Construction and Infrastructure
The demand landscape is being reshaped by concurrent growth in urban densification, aging infrastructure rehabilitation, and large-scale water management projects. Roofing remains the dominant application segment, reflecting ongoing commercial and residential construction activity across multiple regions. However, underground structures and basements represent a substantial and growing share of demand, driven by below-grade expansion in metropolitan areas, subway system upgrades, and storage facility construction. Water management and reservoir applications further contribute to demand stability, particularly in regions facing water scarcity or requiring upgraded containment infrastructure.
PW Consulting
Behavioral shifts among developers and general contractors also influence purchasing patterns. There is increasing preference for systems that reduce on-site labor complexity, accelerate installation timelines, and minimize the risk of application errors. Pre-formed membranes that offer peel-and-stick or fully bonded installation methods address these priorities by reducing reliance on hot-applied adhesives or on-site torch application. This trend favors suppliers who provide comprehensive technical support, installer training programs, and integrated system solutions rather than standalone product sales.
Supply Chain and Cost Structure Evolution
Supply chain dynamics have emerged as a decisive factor in market competitiveness. The volatility in ethylene and propylene feedstocks continues to influence production economics and pricing stability for polymer-based membranes. Manufacturers are responding by diversifying raw material sourcing, investing in backward integration, or adopting formulations that optimize material efficiency without compromising performance. Facility enhancements, such as those recently executed by Carlisle Construction Materials to strengthen TPO and EPDM membrane manufacturing capacity, illustrate how companies are aligning production infrastructure with demand signals and material availability considerations.
Logistics and regional manufacturing footprints also matter. Transporting heavy rolled membranes across long distances introduces cost penalties and carbon footprint concerns, particularly in markets with stringent emissions accounting. Localized production reduces lead times, improves responsiveness to regional specification requirements, and mitigates tariff or trade disruption risks. Companies that strategically position manufacturing assets near high-growth demand centers gain advantages in both cost structure and customer intimacy.
Competitive Landscape and Leading Strategies
The competitive environment in the pre-formed waterproofing membrane market is characterized by a mix of global specialty chemical and construction materials companies, regional manufacturers, and niche technology providers. Sika AG maintains a strong position through its SikaProof pre-applied fully bonded TPO/FPO sheet membranes and Sikaplan loose-laid systems for below-grade applications, supported by broad technical service capabilities and a global distribution network. SOPREMA Group differentiates through SBS-modified bitumen pre-applied and self-adhered sheet waterproofing membranes, including Colphene and other pre-formed systems that address both roofing and below-grade requirements. Carlisle Companies Inc., through its Carlisle Coatings & Waterproofing division, competes with MiraPLY and MiraDRI self-adhering sheet membranes designed for horizontal and vertical below-grade applications, emphasizing ease of installation and consistent performance.
Other notable participants bring complementary strengths. Polyglass U.S.A. offers Mapeproof FBH NA pre-applied fully bonded multi-layer membranes alongside other pre- and post-applied sheet systems for below-grade use. Siplast focuses on TeraPROOF pre-applied V-SBS and H-SBS modified-bitumen heat-weldable membranes, catering to applications where thermal bonding provides installation advantages. MAPEI S.p.A. combines polymer-modified bituminous pre-formed sheet membranes with cementitious systems, enabling integrated waterproofing strategies for concrete structures. BASF SE provides MasterSeal pre-applied HDPE sheet membranes for below-grade and foundation applications, leveraging advanced polymer engineering. GCP Applied Technologies, operating under brands such as CertainTeed and Saint-Gobain, specializes in PREPRUFE pre-applied and post-applied fully bonded HDPE membranes for concrete structures. Tremco, as part of RPM International Inc., supplies TREMproof sheet-applied membranes including Amphibia and 560A self-adhesive pre-formed sheets for below-grade and blindside applications. W. R. Meadows, Inc. offers MEL-ROL self-adhering rolled pre-formed bituminous membranes for foundations, walls, and slabs. AVM Industries produces below-grade and between-slab peel-and-stick membranes as part of high-performance systems targeting specialized installation scenarios.
Strategic Positioning and Differentiation
Leading players are pursuing differentiation along several axes. Performance reliability remains foundational, with manufacturers investing in formulation improvements that enhance adhesion, elongation, and resistance to puncture or chemical degradation. Service integration is another critical lever. Companies that bundle membranes with installation guidance, quality control protocols, and warranty support create stickier customer relationships and reduce specification risk for contractors. Geographic strategy also matters; firms that balance global reach with regional manufacturing presence can respond more effectively to local code requirements, climate conditions, and cost expectations.
Product portfolio breadth versus specialization presents a strategic choice. Larger conglomerates leverage cross-selling opportunities across construction chemicals, adhesives, and protective systems, offering specifiers a single-source advantage. Specialized manufacturers, by contrast, often compete on deep application expertise, tailored formulations, and agility in serving niche segments such as tunnel lining or reservoir containment. Both models can succeed, but sustained performance depends on aligning portfolio strategy with the priorities of target customers and the technical demands of end-use applications.
Market Structure Evolution
The market structure is likely to evolve through a combination of consolidation, portfolio rationalization, and selective entry by players with complementary technologies. M&A activity may accelerate as larger companies seek to acquire specialized formulations, regional manufacturing footprints, or installation service capabilities that strengthen their competitive position. At the same time, regional fragmentation will persist where local cost structures, building practices, and regulatory environments create distinct demand profiles. New entrants with innovative material technologies or digitally enabled quality assurance systems could disrupt segments that have historically been dominated by established incumbents, particularly where installation efficiency and lifecycle performance become decisive evaluation criteria.
Worldwide APP Waterproofing Membrane Market
Future Trends and Commercial Implications
Over the next three to five years, several trends will shape the trajectory of the pre-formed waterproofing membrane market. First, sustainability-driven specification will intensify. Developers and public agencies will increasingly require membranes that demonstrate reduced environmental impact, lower embodied carbon, and compatibility with recycling or reuse initiatives. This trend creates commercial opportunities for manufacturers that can substantiate environmental claims with verified data and offer products aligned with green building certification requirements. It also introduces risk for companies that rely heavily on traditional bituminous formulations without a clear pathway to compliance.
Second, installation efficiency and system integration will gain prominence. As labor availability constraints and project schedule pressures continue, specifiers will favor membranes and associated systems that reduce on-site complexity, accelerate application, and minimize rework. Pre-applied fully bonded and self-adhering solutions that perform reliably across a range of substrates and weather conditions will see growing adoption, particularly in below-grade and blindside applications where failure consequences are severe. Suppliers that provide training, technical support, and quality assurance tools will capture disproportionate value in this environment.
Third, regional demand divergence will continue to influence strategy. Asia Pacific remains the largest market region, reflecting ongoing urbanization, infrastructure investment, and commercial construction activity. Europe and North America will be shaped more by renovation, regulatory compliance, and performance-driven specifications. Middle East and Africa, as well as Latin America, present growth opportunities but require localized pricing strategies and supply chain configurations that account for cost sensitivity and logistical constraints. Companies that tailor their go-to-market approach to these regional realities will outperform those applying a uniform global strategy.
Potential risks include continued raw material price volatility, which can erode margins and destabilize pricing agreements; regulatory shifts that alter specification requirements faster than product development cycles can accommodate; and competitive intensity that compresses returns in commoditized segments. Organizations that build flexibility into their supply chains, invest in application-specific innovation, and develop transparent performance data will be better positioned to navigate these uncertainties.
Worldwide Preformed Firestop Devices Market
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align product development with the dual imperatives of performance reliability and sustainability compliance. Investing in polymer formulations that balance durability with environmental considerations, expanding localized production to reduce cost and lead-time exposure, and strengthening technical support ecosystems will differentiate offerings in a crowded field. Close monitoring of raw material price trends and feedstock availability is essential for proactive pricing and inventory strategies.
For investors, the market offers attractive structural growth supported by infrastructure spending, urban development, and regulatory tailwinds, but returns will increasingly accrue to companies with clear technological differentiation and disciplined cost management. Evaluating targets or partners should involve scrutiny of formulation capabilities, regional manufacturing footprints, installation service integration, and exposure to commoditized segments where pricing pressure is acute. Diversification across application types and geographies can mitigate concentration risk.
For procurement teams and project developers, specifying pre-formed waterproofing membranes should extend beyond initial unit cost to encompass lifecycle performance, installation complexity, warranty terms, and environmental compliance. Engaging suppliers with documented quality assurance processes, installer training programs, and transparent product data reduces project risk and supports long-term asset performance. Requesting detailed technical specifications, third-party test results, and region-specific performance data will lead to more informed sourcing decisions.
Accessing granular segmentation data, regional demand forecasts, competitive benchmarking, and customized scenario analysis can materially improve strategic planning and investment timing. Detailed quantitative breakdowns, company-level competitive assessments, and segment-specific pricing dynamics are available in specialized research resources for teams seeking to validate assumptions and sharpen execution plans.
For detailed analysis of this topic, please visit the official page: Worldwide Pre-Formed Waterproofing Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com