

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide High Speed Nail Making Machine Market: What 6.25% CAGR Really Means

Global High-Speed Nail Making Machine Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Overview and Core Challenges
The global high-speed nail making machine market has demonstrated consistent expansion over the past half-decade, transitioning from a mature industrial equipment segment into a technology-driven growth cycle. Revenue for 2025 reached approximately USD 518.8 million, building on a compound trajectory that extends back to 2020. Forward projections through 2032 indicate the market will approach USD 793 million, supported by a forecasted compound annual growth rate of 6.25 percent. This growth trajectory reflects more than incremental demand for fasteners; it signals a structural shift in manufacturing capability, automation adoption, and regional production reallocation. The market remains moderately concentrated, with the top three players capturing roughly 38 percent of global revenue and the top five exceeding half, leaving substantial room for specialized suppliers, regional champions, and technology-driven newcomers to compete on performance, service, and total cost of ownership.
Despite the positive momentum, manufacturers and capital allocators face three interconnected challenges that will shape strategic decisions over the next several years. First, raw material price volatility, particularly in steel wire rod, introduces unpredictable input cost swings that compress margins for both equipment buyers and machine builders. Price divergence across major sourcing regions has widened, forcing procurement teams to balance proximity, logistics, and hedging strategies rather than relying on a single global benchmark. Second, the industry is navigating a labor efficiency inflection point. Factories in high-wage or labor-constrained environments are no longer evaluating automation as a cost-reduction afterthought; they are adopting high-speed machines precisely because modern units require fewer operators, integrate programmable logic controllers, and include optical wire-disorder shutdown systems that reduce downtime and manual intervention. Third, regulatory and sustainability expectations are quietly raising the bar for equipment standards. Energy efficiency, noise reduction, safety enclosures, and compatibility with circular material streams are becoming differentiators rather than optional features, especially in markets where construction and automotive demand cycles intersect with stricter environmental compliance.
For decision-makers, the implications are clear. Growth is real, but it is uneven across technology tiers and geographies. Companies that treat equipment purchases as pure capital expenditure will likely face margin pressure and operational friction. Those that evaluate machines through a lifecycle lens—considering throughput consistency, software-enabled maintenance, material handling compatibility, and operator scalability—will be better positioned to absorb volatility and capture demand surges when construction or packaging activity accelerates.
Key Drivers Shaping Market Dynamics
Technology innovation is the primary engine behind the segment's growth trajectory. Recent product introductions have pushed output capabilities into new ranges, with some rotary platforms now claiming speeds approaching 2,500 nails per minute, while compact linear and rotary variants continue to optimize handling for shorter nail lengths and specialized fastener profiles. The significance of these advances is not merely headline throughput; it lies in the integration of control architectures that stabilize production, reduce setup time, and enable one operator to supervise multiple units. Machines equipped with optical sensing and automatic wire-disorder shutdown, for example, reduce waste and unplanned stoppages, which directly improves overall equipment effectiveness in high-volume environments. This technological layer is reshaping the investment case for manufacturers who previously hesitated to upgrade from semi-manual or lower-speed lines.
Policy and regulatory environments are acting as a secondary but increasingly influential driver. Construction-linked procurement frameworks, industrial safety expectations, and energy-efficiency considerations are nudging buyers toward equipment that offers enclosed-frame designs, reduced occupational exposure, and more predictable power consumption. In regions where labor availability is tightening, governments and industry clusters are also indirectly encouraging automation through skills-gap pressures, making high-speed machines a practical response to operating constraints. Although regulatory mandates differ by market, the broader direction favors machines that combine compliance-friendly design with flexibility across fastener sizes and lengths, from small-diameter products to longer construction-grade nails.
Nail Gun Market
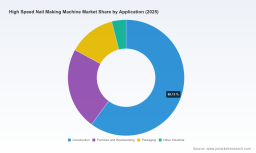
Demand-side behavior continues to evolve along two parallel tracks. On the construction front, sustained infrastructure activity, residential repair cycles, and modular building practices keep demand for standardized and specialty nails elevated, particularly in developing industrial corridors and fast-urbanizing markets. On the commercial side, furniture, woodworking, and packaging applications are driving demand for consistent, high-volume output with tight dimensional tolerances. Buyers in these segments increasingly prioritize line integration, including collating, wire drawing, and thread-rolling capabilities, because they seek to reduce handling steps and improve downstream throughput. This end-use mix matters because it influences the type of machine and production line configuration that will deliver the best return, rather than pushing all buyers toward a single universal solution.
Supply chain and cost structure dynamics complete the driver set. Steel wire rod pricing remains a critical variable, with notable regional dispersion observed in early 2026: prices in major exporting hubs in East Asia have hovered near the lower end of the spectrum, while Indian and U.S. benchmarks have been materially higher. This dispersion affects where new capacity is economically justified, how manufacturers plan procurement, and which machine configurations offer the best yield per ton of input material. At the same time, labor cost pressures—especially the documented efficiency gains and reduced staffing requirements seen in Chinese factory upgrades—have accelerated adoption of high-speed platforms. The combined effect is a market in which procurement is becoming more regionalized and more strategic, with buyers treating machine selection as a way to manage material yield, labor intensity, and changeover flexibility simultaneously.
Competitive Landscape and Leading Strategies
The competitive field blends established multinational specialists with agile regional manufacturers that have built reputation on throughput, line integration, and export reach. European and Danish providers have strengthened their position by emphasizing high-performance rotary platforms, automated production lines, and software-enabled process control, positioning these capabilities as tools for stability and precision rather than raw speed alone. Their launch activity—such as the introduction of next-generation rotary models and integrated software platforms—signals a focus on total manufacturing performance, including setup efficiency, monitoring, and operator-assisted supervision. These players typically compete on reliability, engineering support, and the ability to deliver consistent output across demanding volume cycles.
Chinese manufacturers, meanwhile, have expanded by combining speed upgrades with broader equipment ecosystems. Several firms now offer complete lines that span wire drawing, high-speed forming, collating, and thread rolling, enabling buyers to consolidate sourcing and reduce integration risk. Exhibit presence and product demonstrations continue to serve as important commercial channels, with recent expo activity highlighting rotary platforms in the 700–800 nails-per-minute range alongside automated coil nail production lines. The strategic emphasis among these suppliers is often on modular scalability, customization for specific fastener lengths and diameters, and the ability to serve diverse export markets with practical, cost-competitive configurations. Indian and Taiwanese producers add further variation, with some emphasizing rugged cast-iron construction and others focusing on closed-frame designs that address occupational safety and operator protection.
The market structure is evolving along three observable trends. First, differentiation is shifting from headline speed to system-level performance: software dashboards, optical safety shutdowns, changeover ergonomics, and collating integration are becoming core purchase criteria. Second, consolidation pressure is emerging at the higher end, where buyers prefer suppliers that can provide line-wide support and predictable uptime, while fragmentation persists at the mid-tier and regional level, where customization and price remain decisive. Third, new entrants and repositioned incumbents are finding space by serving niche requirements—such as specialized nail lengths, specific material grades, or compact footprints for space-constrained factories—rather than competing head-on in commodity volume segments.
For buyers and investors, the landscape suggests a need to assess suppliers against operating context rather than generic specifications. A manufacturer running long production runs with tight tolerances may value software control and optical error handling more than marginal speed gains, while a factory focused on export diversification may prioritize full-line integration and after-sales support. Suppliers that can articulate total cost of ownership, not just unit price or nominal output, are gaining advantage in evaluation cycles.
High Speed Packaging Machine Market
Future Trends and Commercial Opportunities
Over the next three to five years, the market is likely to reward three intersecting trends. The first is the continued elevation of automation intelligence. Expect broader adoption of control systems that do more than start and stop machines: platforms will increasingly offer production monitoring, predictive maintenance cues, and easier changeover workflows that reduce idle time when switching between nail lengths or diameters. Machines that can be supervised by a single operator across multiple units will remain attractive in environments where skilled labor is scarce or expensive, and suppliers that package these capabilities with clear training and service support will gain differentiation.
The second trend is regional capacity realignment driven by material economics and demand geography. Because steel wire rod pricing has diverged significantly across regions, some manufacturers will favor equipment and sourcing strategies that reduce exposure to long-haul logistics and currency swings, while others will invest where local demand and construction cycles provide stronger revenue visibility. This realignment creates opportunities for machine builders that can offer flexible configurations suited to local material availability and for service providers that can support distributed fleets of equipment across multiple markets.
The third trend is the growing importance of line integration and end-use specialization. Buyers in construction, packaging, furniture, and woodworking are increasingly evaluating fastener production as part of a broader workflow, not as an isolated machine purchase. This favors suppliers that can deliver collating, wire drawing, and length-specific forming in coordinated setups, and it opens commercial opportunities for companies that can advise on line architecture rather than simply sell hardware. At the same time, uncertainty persists. Demand cycles in construction and automotive-linked sectors can shift faster than capital deployment plans, input prices can disrupt payback calculations, and technology upgrades can strand older assets if integration standards evolve. Businesses that build scenario flexibility into their equipment strategy—choosing platforms with reversible or modular features, serviceable components, and clear upgrade paths—will be better insulated against these swings.
Strategic Recommendations for Decision-Makers
For equipment manufacturers and production leaders, the priority is to align machine selection with operating realities rather than headline specifications. Evaluate throughput in the context of material yield, changeover time, and labor deployment, and favor configurations that integrate collating, wire handling, and control systems if the business relies on downstream line continuity. Where labor costs are high or availability is constrained, prioritize platforms designed for multi-unit supervision and reduced manual intervention, and treat service and software capability as part of the purchase decision.
PW Consulting
For investors, the opportunity lies in identifying players that are transitioning from commodity equipment sales to performance-based value propositions. Companies with credible automation features, full-line integration options, and export-ready service networks are better positioned to defend margins in a moderately concentrated market. Monitor regional supply dynamics and raw material dispersion as leading indicators of where demand will concentrate, and assess whether target businesses have the flexibility to serve multiple end-use segments without compromising quality or uptime.
For procurement and operations leaders, the most effective approach is to model total cost of ownership across multiple scenarios. Test assumptions around wire rod pricing exposure, operator staffing, and production mix before committing to a configuration, and request evidence of reliability under changeover conditions rather than optimized single-product runs. Detailed segmentation data, regional pricing benchmarks, and supplier-by-supplier capability comparisons can materially improve procurement timing and negotiation leverage. For organizations that require deeper segmentation, scenario modeling, and tailored supplier evaluation frameworks, the full market research report provides the granular data and customizable analysis needed to support capital planning and procurement strategy.
For detailed analysis of this topic, please visit the official page: Worldwide High Speed Nail Making Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com