

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Anti Radiation Clothing Market: 7.03% CAGR and the Real Growth Drivers

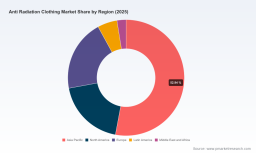
Navigating the Worldwide Anti Radiation Clothing Market: Strategic Trends and Commercial Opportunities
The global anti radiation clothing market stands at a pivotal juncture where medical necessity, technological advancement, and growing environmental awareness converge to reshape industry dynamics. Valued at approximately USD 788.58 million in 2025, the market has demonstrated steady expansion from a base of USD 585.40 million in 2020, reflecting a compound annual growth rate of 7.03 percent through the forecast period extending to 2032. This trajectory points toward a market size of USD 1,266.28 million by the end of the forecast window, representing a fundamental shift in how radiation protection is conceptualized, manufactured, and deployed across multiple end-use sectors.
The growth trajectory reflects more than incremental expansion. It signals structural changes in radiation protection requirements, material science capabilities, and user expectations. Healthcare facilities, industrial operations, and specialized professional environments continue to drive-volume demand, while emerging applications in maternity wear and consumer-adjacent categories introduce new growth vectors. The market's resilience through recent supply chain disruptions and material cost fluctuations suggests underlying demand strength that extends beyond cyclical factors.
Despite this positive momentum, several critical challenges shape the competitive landscape and influence strategic decision-making. Material performance optimization remains a central concern, particularly as end-users increasingly prioritize comfort, flexibility, and ergonomics alongside protection efficacy. Lead-based shielding materials face mounting regulatory and environmental scrutiny, compelling manufacturers to develop lead-free alternatives that match or exceed traditional performance benchmarks. Simultaneously, the industry operates within a rigorous certification framework—standards such as IEC 61331-1:2014 specify protective clothing performance requirements for X-ray and gamma radiation attenuation, establishing baseline expectations that vary across application domains. The FDA's classification of radiation-attenuating medical gloves and aprons as Class I devices under 21 CFR 892.6500 further reinforces the importance of compliance in market access and customer confidence.
Supply chain resilience presents another strategic consideration. Raw material availability, particularly for specialized metal fibers and composite blends, introduces cost variability that affects both production planning and pricing strategies. Lead-free composites utilizing tungsten, bismuth, and antimony have demonstrated the ability to reduce apron weight by 30 to 50 percent compared to pure lead equivalents, yet scaling these materials while maintaining consistent shielding performance requires sophisticated manufacturing processes and quality control protocols. The World Health Organization's radiation safety guidelines emphasize that no clothing provides complete protection against ionizing radiation, with effectiveness limited to specific energy levels and exposure types. This technical reality underscores the importance of application-specific product design and informed user education—a dimension that separates market leaders from commodity suppliers.
Key Drivers Shaping Market Evolution
Technological Innovation and Material Science Breakthroughs
The most transformative force reshaping the anti radiation clothing landscape is the continuous advancement in material science and textile engineering. Traditional lead-based shielding, while effective, carries inherent limitations in weight, flexibility, and environmental impact. The industry response has been a deliberate shift toward engineered composites and specialty fibers that balance protection performance with wearability. Metal fiber fabrics currently represent the dominant material segment, leveraging conductive and shielding properties that suit a range of professional applications. Silver fiber fabrics constitute a substantial secondary segment, valued for their antimicrobial characteristics and compatibility with garments requiring frequent laundering or extended wear cycles.
Recent product development activity illustrates the pace of innovation. In June 2024, Radiation Protection Products introduced a new line of lightweight lead-free X-ray aprons with enhanced flexibility, directly addressing healthcare professionals' longstanding concerns about fatigue and mobility restrictions during extended procedures. This launch reflects a broader industry trend where ergonomic improvement is no longer secondary to shielding efficacy—it is a competitive differentiator. The move toward lead-free formulations using tungsten, bismuth, and antimony composites has enabled manufacturers to achieve meaningful weight reductions without compromising attenuation performance for standard diagnostic energy ranges. These material advancements unlock new use cases, from prolonged surgical procedures to mobile imaging units where portability directly affects workflow efficiency.
Beyond material composition, manufacturing precision and quality assurance frameworks are maturing. The classification of radiation-attenuating gloves and aprons as Class I devices under FDA regulations establishes a baseline for general controls that manufacturers must integrate into product development cycles. International standards such as IEC 61331-1:2014 provide structured performance benchmarks for X-ray and gamma radiation attenuation, creating a common language for specification, testing, and compliance verification. Companies that invest in robust testing infrastructure and transparent certification documentation position themselves favorably as procurement teams increasingly scrutinize not just protection claims but verifiable performance data.
Protective Clothing Market
Regulatory Environment and Compliance Dynamics
Regulatory frameworks continue to exert significant influence over product design, market entry, and competitive positioning. The convergence of international standards and regional regulatory requirements creates both compliance complexity and market segmentation opportunities. In medical applications, the distinction between diagnostic X-ray protection and higher-energy gamma or neutron radiation scenarios demands differentiated product architectures and certification pathways. The Artemis II mission validation for the AstroRad vest, announced in October 2024, exemplifies how high-profile certification events can validate advanced protective technologies while opening new application domains beyond terrestrial healthcare.
Regulatory momentum also shapes procurement behavior. Healthcare institutions and occupational safety programs increasingly require documented compliance with recognized standards as a prerequisite for vendor qualification. This dynamic elevates the importance of regulatory readiness and creates barriers that favor established players with mature quality management systems. At the same time, it opens opportunities for niche manufacturers that achieve certification for specialized applications or emerging use cases where incumbents have limited presence. The regulatory environment, therefore, functions as both a constraint and a strategic filter, rewarding companies that treat compliance as a core capability rather than a post-development checkbox.
Demand-Side Shifts and End-User Expectations
End-user expectations are evolving in ways that directly influence product requirements and purchasing criteria. Healthcare workers who spend extended periods wearing radiation protection garments have become more vocal about comfort, breathability, and fit. This feedback loop has accelerated the development of garments that reduce physical strain while maintaining protection integrity. The introduction of Zero-Gravity 2.0 aprons, showcased at the RSNA 2023 radiology conference by Barrier Technologies, illustrates how concept evolution in professional wear translates into tangible product iterations that address real-world workflow constraints.
Beyond occupational wear, demand patterns are expanding into adjacent categories. Maternity wear applications have emerged as a significant end-use segment, reflecting growing awareness of radiation exposure considerations during pregnancy and the need for protective garments that accommodate changing body shapes without sacrificing comfort or style. This segment's prominence in market composition underscores how protective apparel is increasingly intersecting with lifestyle and consumer considerations. Professional occupational wear remains the second-largest application category, driven by continuous demand from radiology departments, catheterization labs, dental practices, and industrial facilities where radiation sources are integral to operations.
PW Consulting
Procurement decision-making is also shifting. Hospital purchasing committees and industrial safety officers increasingly evaluate total cost of ownership rather than unit price alone. Factors such as garment lifespan, laundering durability, replacement frequency, and ergonomic impact on worker productivity influence purchasing recommendations. This broader evaluation framework rewards manufacturers that can demonstrate product durability, consistent performance across use cycles, and design features that reduce user fatigue. It also encourages suppliers to develop service-oriented offerings, including fitting programs, replacement schedules, and performance documentation that supports compliance audits.
Supply Chain and Cost Structure Considerations
The supply chain for anti radiation clothing materials operates within a specialized ecosystem where raw material sourcing, textile processing, and finished garment manufacturing require aligned capabilities. Metal fiber production, silver-based textile integration, and composite material formulation each present distinct supply chain characteristics. Lead-free composite materials, while offering performance and environmental advantages, depend on the availability of tungsten, bismuth, and antimony inputs that can experience price volatility and supply interruptions. Manufacturers that secure diversified sourcing strategies or develop proprietary material formulations gain resilience against input cost fluctuations.
Cost structures are further influenced by the customization requirements that differentiate premium products from standardized offerings. Custom lead-free composite materials and garments for nuclear, medical, and industrial applications—as produced by companies such as MarShield—require flexible manufacturing setups and close collaboration with end-users to achieve specification fit. This customization premium can support higher margin profiles but demands operational agility and strong technical sales capabilities. Conversely, standardized product lines targeting broad medical applications benefit from scale efficiencies but face more direct price competition. The balance between customization and standardization remains a strategic choice that shapes cost structures, customer relationships, and market positioning.
Competitive Landscape and Strategic Positioning
The anti radiation clothing market exhibits moderate concentration, with the top three competitors holding a combined market share of 31.2 percent and the top five collectively accounting for 42.55 percent. This structure indicates a market where established players maintain meaningful presence without dominating to the extent of creating insurmountable barriers for focused challengers. The competitive field includes companies with diverse geographic footprints and application portfolios, ranging from medical-focused manufacturers to firms serving nuclear and industrial sectors with specialized shielding solutions.
StemRad, headquartered in Israel, has carved a distinctive position by developing selective shielding technologies such as the AstroRad vest for astronauts and the 360 Gamma suit for first responders. These products target protection of bone marrow from gamma and neutron radiation, representing a highly specialized application domain where performance differentiation is pronounced. The October 2024 validation of the AstroRad vest for the Artemis II mission demonstrates how certification milestones in demanding environments can enhance brand credibility and open pathways to adjacent professional and emergency response markets. StemRad's strategy illustrates the value of focusing on technologically differentiated products that address specific protection gaps rather than competing broadly on general-purpose shielding apparel.
Radiation Shielding Textile Market
North American manufacturers dominate several segments of the competitive landscape, reflecting the region's established medical imaging infrastructure and radiation safety regulations. Radiation Protection Products, based in the United States, manufactures lead-free and lead-composite anti-radiation aprons, thyroid collars, and gloves for medical X-ray protection. Its June 2024 product launch of lightweight lead-free X-ray aprons with enhanced flexibility signals a strategic emphasis on comfort-driven innovation within the medical professional wear category. Barrier Technologies, also U.S.-based, produces lightweight Zero-Gravity lead-free radiation protection aprons and accessories for healthcare professionals. The company's showcase of Zero-Gravity 2.0 at the RSNA 2023 radiology conference highlights a commitment to continuous product iteration informed by professional user feedback.
Infab Corporation and Ray-Bar Engineering round out the competitive field with offerings that span lead-free and lead-composite X-ray aprons, vests, shields, and lead acrylic barriers for X-ray and gamma applications. Infab's portfolio addresses both medical and industrial radiation protection, while Ray-Bar Engineering supplies lead acrylic and lead-free shielding clothing and barriers, positioning the company at the intersection of protective garments and facility-based shielding solutions. MarShield, based in Canada, provides custom lead-free composite materials and garments for nuclear, medical, and industrial radiation shielding, emphasizing bespoke solutions that cater to specialized requirements.
The strategic differentiators among leading companies cluster around several dimensions. Material innovation and weight reduction capabilities distinguish products in segments where user comfort directly affects adoption and satisfaction. Certification breadth and regulatory compliance documentation influence procurement eligibility, particularly in medical and government-adjacent applications. Product range depth—spanning aprons, gloves, thyroid collars, and specialized vests—enables companies to serve as consolidated suppliers for institutional buyers seeking single-vendor efficiency. Geographic reach and local support infrastructure matter for customers who require rapid replacement, fitting services, and region-specific regulatory alignment.
Market evolution trends suggest both consolidation pressure and differentiation opportunities. Larger players with diversified portfolios can leverage scale in raw material procurement and manufacturing while cross-selling across medical, industrial, and occupational segments. At the same time, specialized manufacturers that achieve strong positioning in high-value niches—such as selective shielding for emergency response, customized garments for nuclear facilities, or premium ergonomic solutions for healthcare—can sustain competitive advantage without needing to compete across the full market spectrum. New entrants face meaningful hurdles in certification, brand trust, and established supplier relationships, but opportunities exist where incumbents under-serve emerging applications or where technological shifts create openings for novel material approaches.
Future Trends and Commercial Implications
Looking ahead to the 2026 through 2032 period, several interconnected trends are likely to shape market direction and create distinct commercial opportunities. The first and most consequential trend is the deepening integration of ergonomic design with shielding performance. As healthcare workforce challenges intensify and occupational safety standards evolve, garments that reduce physical burden while maintaining protection integrity will gain preference in procurement decisions. Companies that invest in user-centric design processes, conduct field testing with professional end-users, and translate feedback into measurable improvements in weight distribution, flexibility, and breathability will strengthen their competitive position. The commercial implication is clear: ergonomic advancement becomes a growth lever, not merely a feature enhancement.
A second trend involves the expansion of application boundaries. While medical professional wear and maternity applications currently anchor significant demand, the underlying technology platform—flexible, lightweight, radiation-attenuating textiles—has potential relevance in additional professional and consumer contexts. Growth in this direction will depend on how effectively manufacturers can adapt product specifications to new use cases while navigating certification requirements and building awareness among target buyers. The presence of metal fiber fabrics and silver fiber fabrics as established material categories provides a foundation for product extension, but success will hinge on application-specific validation and clear communication of protection scope and limitations.
A third trend relates to sustainability and material lifecycle considerations. The shift away from lead-based materials is already underway, driven by regulatory pressure, environmental preference, and user comfort benefits. This transition is likely to accelerate as procurement organizations incorporate environmental criteria into supplier evaluations and as lead-free composite technologies mature further. Manufacturers that develop clear sustainability narratives—whether through material selection, manufacturing efficiency, garment longevity, or end-of-life handling—can differentiate in segments where buyers increasingly weigh environmental impact alongside performance and cost. The uncertainty here lies in the pace and uniformity of sustainability-driven procurement shifts across regions and customer segments.
Potential risks and uncertainties warrant attention. Regulatory frameworks may evolve in ways that alter certification pathways or introduce new performance expectations, affecting product development timelines and compliance costs. Raw material markets for specialized components can experience volatility that disrupts cost structures or limits production capacity. Additionally, the technical limitation that no clothing provides complete protection against ionizing radiation—only effectiveness limited to specific energy levels and exposure types—means that market growth depends on informed application and realistic user expectations. Overstatement of protection capabilities can create liability exposure and undermine trust, making transparent communication and accurate product specification essential for sustainable positioning.
Strategic Recommendations for Decision-Makers
For manufacturers operating in or considering entry into the anti radiation clothing market, the strategic priority is to align product development with the convergence of protection performance and user experience. Investing in lead-free composite formulations, ergonomic design capabilities, and application-specific testing infrastructure creates defensible differentiation. Companies should also evaluate whether their portfolio strategy favors broad coverage across medical and industrial applications or deep specialization in high-value niches where certification and technical expertise create stronger barriers. Building transparent compliance documentation and maintaining rigorous quality control processes strengthens customer trust and supports premium positioning.
Investors evaluating opportunities in this space should focus on companies with demonstrated material innovation capabilities, clear certification readiness, and product lines that address the ergonomic demands reshaping procurement preferences. The moderate market concentration suggests that well-positioned mid-tier players can achieve meaningful growth without requiring market-leading scale. Due diligence should examine raw material sourcing resilience, the strength of regulatory documentation, and the extent to which product roadmaps reflect real end-user feedback. Companies that rely solely on commodity shielding products without innovation pipelines face greater exposure to price competition and substitution risk.
For procurement leaders and institutional buyers, the priority is to move beyond unit-price comparisons and evaluate total cost of ownership, including garment durability, replacement cycles, ergonomic impact on staff, and compliance verification. Engaging suppliers early in the specification process—particularly for facilities with unique workflow requirements or specialized radiation sources—can yield products better aligned with operational realities. Documentation that supports audit readiness and demonstrates alignment with recognized standards such as IEC 61331-1:2014 and relevant FDA classifications strengthens procurement defensibility. Maintaining awareness of evolving material technologies and certification developments enables buyers to make informed decisions as the market continues to mature.
The anti radiation clothing market offers substantive opportunities for organizations that approach it with strategic clarity, technical rigor, and a clear understanding of how protection requirements, user expectations, and regulatory dynamics interact. For decision-makers seeking detailed segmentation data, regional breakdowns, competitive profiles, and customized strategic recommendations, the full research report provides comprehensive analysis to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Anti Radiation Clothing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com