

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Pharmaceutical Grade Bentonite Powder Market: Why 5.35% CAGR Drives Multibillion Scale

Strategic Horizons: The Worldwide Pharmaceutical Grade Bentonite Powder Market
Market Overview and Core Challenges
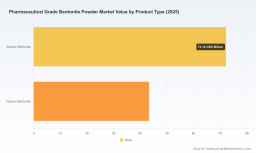
The global market for pharmaceutical grade bentonite powder has demonstrated consistent expansion over the past five years, establishing itself as a critical component within the broader pharmaceutical excipients landscape. Valued at approximately 88.5 million USD in 2020, the market has grown steadily to reach 115.42 million USD in 2025, reflecting a compound annual growth rate of 5.35% over the historical period. This growth trajectory underscores the material's indispensable role in drug formulation, ranging from suspension stabilization to tablet binding. Looking ahead, the forecast period from 2026 to 2032 projects continued momentum, with revenues expected to approach 166.24 million USD by the end of the forecast horizon.
This expansion is not merely a function of volume but also reflects increasing sophistication in pharmaceutical manufacturing. As drug delivery systems become more complex, the demand for high-purity, consistent excipients like bentonite intensifies. The market's resilience is evident in its ability to grow even amidst broader economic volatility, driven by the non-discretionary nature of pharmaceutical production. However, the path forward is not without turbulence. The industry stands at a inflection point where raw material cost volatility and stringent regulatory compliance intersect to create significant operational headwinds.
One of the primary challenges facing market participants is the fluctuation in raw material pricing across key regions. Recent data indicates divergence in cost structures; for instance, bentonite prices in Europe reached 189.77 USD/MT in March 2026, reflecting a 9.1% increase from December 2025 levels driven by demand in industrial sectors and rising production costs. Conversely, North America bentonite prices stood at 209.41 USD/MT in March 2026, experiencing a 3.2% decrease from December 2025 levels amid softer oil & gas drilling demand. This regional disparity complicates procurement strategies for global pharmaceutical companies that rely on consistent input costs to manage their own pricing structures.
Furthermore, the regulatory environment remains a formidable barrier to entry and a ongoing compliance burden for existing manufacturers. Pharmaceutical-grade bentonite must comply with USP, EP, and other pharmacopeial standards, including limits on heavy metals, typically below 10 ppm, and microbial contaminants with impurity levels generally below 2%. Meeting these specifications requires over 70% montmorillonite content and high purity processing, often water-washed, to meet NF/USP standards for excipient use. Maintaining this level of purity while managing costs amidst rising energy and processing expenses creates a delicate balancing act for producers. These factors collectively define the current market tension, where growth is evident but profitability and supply security are increasingly scrutinized.
Key Growth Drivers and Market Dynamics
Several core factors are propelling the demand for pharmaceutical grade bentonite, transforming it from a commodity filler to a value-added formulation component. The interplay between technological innovation, regulatory shifts, demand-side evolution, and supply chain restructuring creates a multifaceted growth environment.
Technological Innovation and Quality Standards
Advancements in processing technology are central to meeting the rigorous demands of modern drug formulation. The requirement for high-purity bentonite typically necessitates over 70% montmorillonite content and high purity processing, often water-washed, to meet NF/USP standards for excipient use. Manufacturers investing in advanced purification and washing technologies are gaining a competitive edge. This technological push is not just about meeting minimums; it is about consistency. In suspensions and emulsions, where bentonite acts as a stabilizer, slight variations in particle size or purity can affect drug stability and bioavailability. Companies utilizing advanced characterization tools to ensure batch-to-batch consistency are finding greater traction with top-tier pharmaceutical clients who prioritize risk mitigation in their supply chains.
Regulatory Environment and Compliance
The regulatory landscape acts as both a gatekeeper and a driver of quality. Pharmaceutical-grade bentonite must comply with USP, EP, and other pharmacopeial standards, including limits on heavy metals, typically below 10 ppm, and microbial contaminants with impurity levels generally below 2%. As global harmonization efforts continue, manufacturers must adhere to multiple standards simultaneously, particularly when exporting across regions. This regulatory stringency favors established players with robust quality assurance systems but also opens opportunities for niche suppliers who can certify specific high-purity grades. Compliance is no longer just a checkbox; it is a market differentiator that influences procurement decisions among quality-conscious pharmaceutical formulators.
PW Consulting
Demand-Side Shifts in Pharmaceutical Formulation
On the demand side, the shift towards complex drug delivery systems is a significant catalyst. The market is segmented by application, with a substantial portion dedicated to suspensions and emulsions, followed by tablet and capsule excipients and topical preparations. As biologic drugs and specialized formulations grow in prominence, the need for reliable suspending agents and binding excipients increases. Bentonite's ability to improve stability and bioavailability in oral medications makes it particularly valuable. Furthermore, the detoxification and others segment, while smaller, represents a niche area where specific clay properties are leveraged for adsorption purposes. Consumer health trends, including the rise in over-the-counter medications and personal care products incorporating pharmaceutical-grade ingredients, also contribute to broadening the application base beyond traditional prescription drugs.
Worldwide Pharmaceutical Grade Calcium Hydroxide Market
Supply Chain and Cost Structure Evolution
Supply chain dynamics are reshaping the cost structure of the market. Regional pricing disparities highlight the impact of local industrial demand and production costs. In Europe, prices reached 189.77 USD/MT in March 2026, reflecting a 9.1% increase from December 2025 driven by demand in industrial sectors and rising production costs. This suggests that competition for bentonite from non-pharmaceutical industrial sectors, such as drilling or construction, can squeeze availability and drive up costs for pharmaceutical grades. In contrast, North America saw a 3.2% decrease from December 2025 levels amid softer oil & gas drilling demand, indicating that when industrial pressure eases, pharmaceutical buyers may find more favorable pricing. Logistics, energy costs, and the geopolitical stability of mining regions also play crucial roles in determining the landed cost of raw materials, influencing where manufacturers choose to source their bentonite.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of specialized producers and large industrial minerals companies, with a notable concentration of supply among key players. The competitive landscape is defined by the ability to guarantee purity, manage supply continuity, and navigate regulatory requirements across different jurisdictions. Market concentration metrics indicate a moderately consolidated environment, with the top three companies holding approximately 42.15% of the market share and the top five controlling around 58.4%. This concentration suggests that while there is room for specialized entrants, scale and established relationships remain significant advantages.
Geographically, the competitive field is diverse. In North America, which accounts for a significant portion of the market, players like Minerals Technologies Inc. (Bentonite Performance Minerals) and Wyo-Ben, Inc. leverage access to Wyoming sodium bentonite deposits. Minerals Technologies Inc. operates through its BPM subsidiary with operations in Wyoming sodium bentonite deposits, positioning itself as a major producer of high-purity bentonite grades, including pharmaceutical applications. Wyo-Ben, Inc. similarly supplies high-quality bentonite suitable for pharmaceutical-grade applications from Wyoming deposits. Their proximity to raw materials provides a cost and logistics advantage in the North American region.
In Europe, Imerys stands out as a global industrial minerals company supplying consistent high-quality bentonite grades, including those suitable for pharmaceutical formulations. Their scale allows for consistent supply across multiple regions, which is critical for large pharmaceutical clients with global manufacturing footprints. Meanwhile, the Asia Pacific region, representing a large share of market activity, hosts a robust cohort of manufacturers based in India and Japan. Kutch Bentoclay and Ashapura Minechem Ltd are large Indian bentonite producers with pharmaceutical-grade offerings meeting international standards. CMS Industries, an ISO 9001:2015 certified manufacturer, supplies pharmaceutical-grade bentonite adhering to international standards with high monthly production capacity. Seema Minerals & Metals and Pratham Minechem also contribute significantly, with Pratham Minechem producing BENTO PHARMA natural calcium bentonite (IP grade) through selective mining and impurity removal for pharmaceutical use.
J&H Minerals adds to the competitive pool by supplying bentonite powder for pharmaceutical, cosmetics, and related industries with exports to multiple regions. In Japan, Kunimine Industries produces specialized bentonite for pharmaceutical applications meeting strict purity requirements. The strategic differentiation among these companies often lies in their certification capabilities and specific grade specializations. For instance, some focus heavily on sodium bentonite for suspensions, while others excel in calcium bentonite for specific topical or detox applications. The market is evolving through a combination of consolidation among larger players seeking to secure raw material sources and the continued emergence of specialized suppliers who can offer certified high-purity grades at competitive prices. New entrants are likely to find success by focusing on niche purity standards or specific regional supply chain reliability rather than competing directly on volume with the largest incumbents.
Future Outlook and Emerging Trends
Looking toward the 2026-2032 period, the market is poised for specific structural shifts that will define investment and operational strategies. The projected growth from 115.42 million USD in 2025 to 166.24 million USD by 2032 suggests a maturing market where quality and reliability become paramount.
One key trend is the increasing premium on certified purity and traceability. As regulatory scrutiny intensifies, the ability to provide documented proof of compliance with USP, EP, and other pharmacopeial standards, including limits on heavy metals, typically below 10 ppm, will become a baseline expectation rather than a differentiator. Manufacturers who can integrate blockchain or other traceability technologies to verify the origin and processing history of their bentonite may gain additional trust from procurement teams. This trend connects directly to commercial opportunity for suppliers who can streamline the vendor qualification process for pharmaceutical clients.
Another significant trend is the regionalization of supply chains. Given the volatility observed in raw material pricing, such as the 9.1% increase in Europe versus the 3.2% decrease in North America over recent months, pharmaceutical companies may seek to diversify their supplier base to mitigate risk. This could lead to increased demand for regionally sourced bentonite, benefiting local producers who can guarantee supply security. However, this trend also carries the risk of fragmentation, potentially increasing costs if economies of scale are lost in favor of regional redundancy.
Pharmaceutical Grade Sodium Chloride Market
Finally, innovation in drug formulation will continue to drive demand for specialized grades. The growth in suspensions and emulsions, as well as tablet and capsule excipients, implies a need for bentonite with specific rheological properties. Suppliers who invest in R&D to tailor bentonite properties for new drug delivery mechanisms will capture higher value segments. The risk here lies in the pace of pharmaceutical innovation; if formulation trends shift away from traditional excipients towards synthetic alternatives, demand could face headwinds. Nevertheless, the natural origin and cost-effectiveness of bentonite provide a strong buffer against such substitution risks in the near to medium term.
Strategic Recommendations for Stakeholders
For manufacturers, the priority should be investment in purification technology and certification capabilities. Given the strict requirements for heavy metals and microbial contaminants, upgrading processing lines to ensure consistent compliance with USP and EP standards is essential. Expanding capacity while maintaining high purity levels, particularly achieving over 70% montmorillonite content, will position companies to capture growth in the 2026-2032 forecast period. Forming strategic partnerships with pharmaceutical formulators early in the drug development process can also secure long-term supply agreements.
Investors should look for companies with diversified regional footprints and robust quality management systems. The disparity in regional pricing and the concentration of market share among the top five players suggest that scale and geographic flexibility are key value drivers. Monitoring raw material cost trends, such as the recent fluctuations in Europe and North America, will be crucial for assessing margin sustainability. Companies that can hedge against input cost volatility or pass these costs through efficiently will offer better investment stability.
For procurement managers and pharmaceutical companies, securing a multi-sourcing strategy is advisable to mitigate supply risk. Relying on a single region exposes the supply chain to local price shocks and logistical disruptions. Evaluating suppliers not just on price but on their ability to demonstrate consistent impurity levels generally below 2% and heavy metal compliance is critical. Engaging with detailed market intelligence reports can provide the granular data needed to negotiate contracts effectively and understand the broader supply dynamics affecting specific grades and regions.
For those seeking to navigate these complexities with greater precision, deeper segmentation data and customized strategic advice are available through comprehensive industry analysis. Understanding the specific dynamics of each region and product type allows for more informed decision-making in a market that rewards quality and reliability above all.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade Bentonite Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com