

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Carbon-14 Market Crosses $372M by 2032: Which Segments Drive the 6.51% CAGR

Global Carbon-14 Market: Strategic Trends, Competitive Dynamics, and the Road to 2032
Market Snapshot: Scale, Growth Trajectory, and Structural Challenges
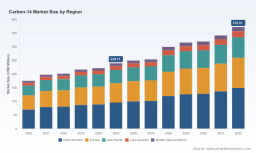
The global Carbon-14 market has entered a phase of steady, structurally sound expansion, driven by sustained demand from life sciences, pharmaceutical development, and specialized industrial applications. Valued at approximately 175.4 million USD in 2020, the market has progressed to an estimated 239.71 million USD by 2025, reflecting consistent year-over-year growth underpinned by both scientific necessity and commercial scaling. Over the historical period from 2020 through 2025, the sector demonstrated resilience against macroeconomic fluctuations, with growth accelerating notably as regulatory frameworks matured and production methodologies diversified. Looking ahead, the market is projected to expand from 249.76 million USD in 2026 to 372.51 million USD by 2032, translating to a compound annual growth rate of 6.51 percent. This trajectory signals a shift from niche scientific supply chains toward more formalized, commercially integrated isotope markets, with long-term planning cycles increasingly aligning with capital-intensive production timelines.
Despite this favorable growth outlook, the sector faces several structural challenges that will define strategic decision-making over the next decade. First, the supply chain for high-specific-activity Carbon-14 remains tightly coupled to specialized nuclear infrastructure, creating geographic and operational dependencies that can constrain scalability. Historically, the industry has navigated periodic shortages, particularly when reactor maintenance cycles or geopolitical factors disrupted traditional barium carbonate sourcing routes. Second, the market exhibits pronounced concentration dynamics. The top three players command a combined market share exceeding 62 percent, while the top five collectively control over 78 percent of total revenue. This concentration reflects high technical barriers, stringent regulatory compliance requirements, and the capital intensity of isotope production, but it also raises questions about supply resilience and competitive pricing power as new entrants scale operations. Third, the dual pressure of maintaining research-grade supply reliability while simultaneously meeting Good Manufacturing Practice standards for clinical and commercial drug development creates operational complexity. Companies must simultaneously manage isotopic purity, specific activity benchmarks, documentation for regulatory submissions, and evolving environmental and safety protocols, all of which strain traditional production models optimized for research-only output.
Core Drivers Reshaping the Carbon-14 Landscape
The acceleration of the Carbon-14 market is not merely a function of incremental demand growth; it is being reshaped by convergent technological, regulatory, and supply-side dynamics that are redefining how isotopes are sourced, enriched, and deployed across industries. Understanding these drivers is essential for mapping where value will accrue and which capabilities will separate market leaders from marginal participants.
Technological Innovation and Production Method Diversification
The most transformative shift in the sector revolves around the diversification of production pathways. For decades, Carbon-14 supply relied heavily on legacy reactor configurations and conventional chemical separation processes. Recent developments have introduced commercially viable alternatives that expand throughput, improve specific activity, and reduce dependency on single-source facilities. One notable advancement is the deployment of heavy water reactor technology adapted for isotope production, which has enabled continuous commercial dispatch and marked a structural break in regional supply constraints. Simultaneously, aerodynamic separation processes have moved from pilot validation to full commercial operation, offering a scalable enrichment route that can be integrated with existing chemical processing infrastructure. These technological alternatives are not merely incremental improvements; they are shifting the supply architecture from bottleneck-dependent models to multi-route production ecosystems, thereby enhancing resilience and opening new capacity thresholds for high-purity and high-specific-activity compounds.
Regulatory Maturation and Compliance as a Competitive Moat
Regulatory expectations across pharmaceutical development, clinical trial material production, and environmental tracing have grown substantially more rigorous. Sponsors and contract development organizations increasingly require Carbon-14 labeled active pharmaceutical ingredients and intermediate compounds that meet defined quality frameworks, including traceability, batch documentation, and compliance with internationally recognized manufacturing guidance. This regulatory maturation has transformed quality systems from operational overhead into strategic differentiators. Facilities that have invested in GMP-aligned synthesis, analytical validation, and formal licensing structures are positioned to command premium engagements in early-phase clinical supply and regulatory submission support. Conversely, organizations still operating primarily within research-grade paradigms face mounting pressure to upgrade documentation, quality control infrastructure, and audit readiness, particularly as drug developers consolidate their radiolabeling partners to reduce compliance risk across development programs.
PW Consulting
Demand-Side Evolution: From Academic Tracing to Commercial Development Pipelines
Demand patterns are shifting as Carbon-14 applications expand beyond classical radiocarbon dating and academic research into structured commercial pipelines. Drug development and ADME research continue to represent the largest application segment, reflecting the enduring role of isotopic labeling in pharmacokinetic profiling, metabolic pathway mapping, and safety evaluation. However, the growth narrative is increasingly tied to the broader expansion of diagnostic applications and specialized industrial tracing, where consistent isotope availability and predictable lead times influence procurement decisions. Enterprise buyers are no longer evaluating suppliers solely on price; they are assessing supply continuity, specific activity consistency, customization capability, and the ability to support both research and GMP-aligned requirements within integrated service models. This behavior shift favors suppliers that can offer end-to-end radiolabeling support, from custom synthesis to stability studies and regulatory documentation, rather than discrete commodity transactions.
Supply Chain Reconfiguration and Cost Structure Implications
The historical reliance on limited raw material sources, particularly barium carbonate derived from select reactor streams, has prompted supply chain reconfiguration. New harvesting approaches that extract Carbon-14 from reactor waste streams, combined with expanded enrichment capacity, are gradually broadening the raw material base and reducing exposure to single-source disruptions. This reconfiguration carries meaningful cost structure implications. While capital investment in new production and enrichment facilities remains substantial, the long-term effect is expected to improve capacity utilization, reduce margin volatility associated with supply shocks, and enable more predictable pricing frameworks. Organizations that secure multi-source supply agreements, verticalize key synthesis steps, or establish long-term offtake arrangements will be better positioned to manage cost variability and maintain competitive positioning as the market scales toward 2032.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The Carbon-14 market is characterized by a blend of established radiochemical specialists, vertically integrated isotope producers, and emerging capacity players leveraging new production technologies. This mix has produced a competitive environment where differentiation is increasingly defined by production flexibility, compliance readiness, and the ability to serve both research and regulated development workflows.
Strategic Positioning Across the Value Chain
Leading participants have carved out distinct strategic positions based on their production assets, service capabilities, and geographic footprint. Companies focused on custom radiosynthesis and labeled compound manufacturing have built reputation strength around analytical precision, rapid turnaround for research-scale orders, and specialized support for early-phase development programs. These players often compete on technical service quality, custom synthesis expertise, and the ability to handle complex labeling requests that require sophisticated synthetic chemistry and quality oversight. In parallel, isotope producers with access to reactor-based or enrichment-based capacity are positioning around supply reliability, specific activity performance, and the ability to support long-term contractual relationships. The recent emergence of commercial reactor-produced Carbon-14 with enhanced specific activity has reinforced the value proposition of producers who can guarantee continuity and performance benchmarks aligned with pharmaceutical and industrial requirements. Meanwhile, organizations offering integrated GMP synthesis, quality control, and stability testing are aligning their service portfolios with the compliance demands of drug developers seeking to minimize partner fragmentation during critical development stages.
Differentiation Through Capability and Compliance Integration
The most defensible competitive advantages in this market are no longer limited to isotope availability alone; they are increasingly tied to integrated capabilities. Suppliers that combine radiolabeling synthesis with analytical support, stability studies, and regulatory documentation reduce friction for procurement teams and development organizations. This integration is particularly valuable in early-phase clinical supply, where documentation rigor, batch consistency, and rapid problem resolution directly influence program timelines. Companies operating under formal manufacturing licenses and aligned quality systems benefit from a trust premium, as pharmaceutical sponsors increasingly consolidate suppliers to reduce audit burden and coordinate quality oversight across multiple development assets. In this environment, differentiation emerges from the ability to deliver reproducible specific activity, maintain documented chain-of-custody and quality records, and support custom synthesis requests without compromising turnaround or compliance standards.
Market Structure Evolution: Consolidation Pressure, New Entrants, and Regional Diversification
The current concentration profile suggests that consolidation pressures will persist, particularly as larger entities seek to expand service breadth and secure supply routes. At the same time, new entrants leveraging alternative enrichment or reactor-based production methods are introducing capacity that can redistribute market share over time, especially in segments where specific activity, cost structure, or regional proximity becomes a decisive factor. The entry of commercially scalable production capacity in new geographic contexts is gradually broadening the supplier base, reducing historical dependency on a narrow set of source facilities, and creating more negotiation leverage for procurement organizations. Over the forecast horizon, the competitive landscape is likely to evolve toward a hybrid structure: a concentrated core of integrated providers with strong compliance and service capabilities, alongside a growing set of capacity-focused producers competing on supply reliability, enrichment performance, and long-term contractual terms. This evolution will reward organizations that can balance technical service excellence with resilient production positioning, while also maintaining the flexibility to adapt as demand patterns shift across drug development, diagnostics, and specialized industrial applications.
Carbon Block Market
Forward Outlook: Key Trends Shaping the Next Three to Five Years
The next several years will be defined by the interplay between capacity expansion, compliance-driven service integration, and the gradual rebalancing of supply concentration. Three trends are particularly likely to influence strategic positioning and commercial opportunity across the Carbon-14 market.
Carbon Black Market
Compounding Capacity Addition and Supply Normalization
As multiple production and enrichment pathways reach commercial maturity, the market is likely to experience a period of capacity normalization. This does not imply oversupply; rather, it suggests a transition from intermittent shortage conditions toward more predictable availability, particularly for high-specific-activity material and standardized labeled compounds. For procurement teams and development organizations, this normalization should reduce lead-time variability and improve planning certainty. For producers, the challenge will shift from pure capacity creation to service differentiation, quality consistency, and contract structuring that aligns with buyer demand for reliability and performance guarantees. Organizations that can convert new capacity into dependable delivery, maintain specific activity benchmarks, and support scaled demand across multiple application areas will be best positioned to capture growth through 2032.
Service Integration as a Growth Multiplier
The convergence of radiolabeling synthesis, analytical support, and GMP-aligned quality systems is expected to deepen as drug developers and diagnostic organizations seek to streamline supplier relationships. Integrated service models reduce coordination overhead, improve documentation continuity, and align incentives across development milestones. This trend favors providers that can offer custom synthesis, regulatory-compliant manufacturing, and analytical validation within coordinated workflows. The commercial opportunity lies not only in expanded volume but in higher-value engagements where quality assurance, turnaround reliability, and technical problem-solving create sticky relationships and support premium pricing in regulated development segments.
Regional Rebalancing and Geopolitical Sensitivity
While the market has historically been anchored by a limited number of source regions, new production routes and export activity are gradually redistributing supply geography. This rebalancing can improve resilience, but it also introduces new considerations around logistics, regulatory acceptance, and long-term partner qualification. Procurement strategies that previously relied on familiar source relationships will need to evaluate alternative suppliers against criteria such as specific activity consistency, documentation quality, audit readiness, and regional risk exposure. At the same time, organizations that can secure diversified sourcing without compromising compliance or technical performance will gain negotiating strength and reduce vulnerability to localized disruptions.
Potential risks remain. Capacity ramp-up timelines can slip, regulatory expectations may intensify beyond current frameworks, and competition could compress margins in standardized research segments if differentiation is limited to price. Market participants should therefore treat capacity availability as necessary but insufficient; durable advantage will come from service quality, compliance readiness, and the ability to maintain technical performance at scale.
Strategic Recommendations for Decision Makers
For manufacturers and service providers, the priority is to align production and service capabilities with the dual demands of research flexibility and regulated development compliance. Investing in integrated synthesis, analytical support, and documented quality systems can convert capacity into differentiation, while long-term supply agreements and multi-source strategies can stabilize cost structures and protect against disruption. Organizations that treat quality documentation, specific activity consistency, and customer-facing technical support as core competitive assets will be better positioned to defend margins and deepen relationships with drug developers and industrial buyers.
For investors evaluating exposure to the Carbon-14 market, the focus should be on operators with defensible production routes, clear compliance positioning, and the ability to scale service complexity rather than volume alone. Capacity expansion is attractive, but durable value creation depends on whether new assets can be integrated into reliable delivery models, meet evolving regulatory expectations, and capture higher-value engagements across development and diagnostic applications. Due diligence should therefore extend beyond production metrics to include quality infrastructure, customer concentration patterns, and the operator’s ability to manage custom synthesis demand without compromising turnaround or compliance integrity.
For procurement leaders and development organizations, the strategic imperative is to build supplier portfolios that balance continuity, performance consistency, and compliance readiness. Diversifying sourcing options, qualifying partners against documented quality systems, and structuring contracts that reward reliability and specific activity performance can reduce program risk and improve planning predictability. Engaging earlier with suppliers during development planning can also align Custom synthesis requirements with production feasibility, helping to avoid delays and documentation gaps during critical milestones. For organizations seeking a deeper segmentation view, regional demand mapping, and customized supply strategy scenarios, a detailed market study can provide the structured intelligence needed to support portfolio decisions and negotiation planning. For those evaluating a tailored assessment, the complete PW Consulting market report offers expanded segmentation data and scenario-based guidance aligned to specific procurement and investment objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Carbon-14 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com