

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
4-Vinyl Guaiacol Market: Why Synthetic’s 60% Share Reshapes 2026-2032 Growth

The Global 4-Vinyl Guaiacol Market: Strategic Trends and Commercial Opportunities
The global 4-Vinyl Guaiacol (4-VG) market has entered a phase of steady structural expansion, underpinned by consistent demand from high-value consumer applications and evolving production methodologies. Over the 2020–2025 period, the market demonstrated compounding growth, scaling from approximately $30.2 million to $38.5 million. The projected compound annual growth rate of 5.15% through 2032 suggests a gradual acceleration, with total revenue expected to approach $55 million by the end of the forecast window. This trajectory reflects a mature yet dynamic specialty chemicals segment where value creation is increasingly tied to differentiation, compliance readiness, and supply chain resilience rather than sheer volume expansion. Market concentration remains moderate, with the top three players capturing roughly 48% of industry revenue and the top five controlling approximately 63%, indicating a landscape where established players maintain scale advantages but fragmented producers continue to compete on specialization and regional agility.
Despite the favorable growth trajectory, the sector faces several structural inflection points that demand strategic attention. First, feedstock volatility and raw material dependency continue to shape margin dynamics. Since 4-VG is predominantly produced through the decarboxylation of ferulic acid, which itself is derived from agricultural byproducts such as rice bran, wheat bran, and maize bran, pricing and availability are tightly linked to seasonal harvest cycles and competing agricultural demand. Ferulic acid spot prices in key producing regions experienced quarterly volatility of 12–18% during the recent two-year window, creating unpredictable cost structures for manufacturers that lack diversified sourcing or long-term supply agreements. Second, the regulatory and quality compliance landscape is becoming more demanding across target geographies. While the compound holds recognized status in flavor applications with characteristic clove-like, smoky, and spicy notes, manufacturers must navigate varying certification requirements, including food-grade, Kosher, and Halal standards, alongside stringent documentation expectations for pharmaceutical intermediates. Third, the market is experiencing a gradual shift in consumer and industrial preferences toward cleaner-label, bio-based, and naturally derived ingredients. This transition is not merely a marketing trend but a structural demand signal that is reshaping product positioning, pricing power, and supplier selection criteria across flavor, fragrance, and specialty chemical applications. Companies that fail to adapt their production architectures or certification portfolios risk marginalization as downstream buyers increasingly prioritize traceability and natural origin claims.
Several interconnected drivers are shaping the next phase of market evolution, each carrying distinct implications for operational strategy and competitive positioning.
Technological Innovation and Production Method Advancement
The shift toward fermentation-based extraction and optimized decarboxylation pathways represents a meaningful technological inflection point. Traditional synthetic routes remain prevalent, but bio-based production from corn ethanol fermentation volatiles has gained traction as a commercially viable alternative for flavor and fragrance applications. This approach offers a dual advantage: it aligns with the growing preference for natural-origin ingredients while providing manufacturers with a more predictable and potentially lower-cost feedstock pathway compared to plant-derived ferulic acid extraction. Companies that have invested in process optimization, yield improvement, and purification technologies are better positioned to deliver consistent purity levels across multiple grades, including pure forms and diluted preparations tailored for specific application matrices. The ability to maintain batch-to-batch consistency while offering flexible dilution formats in carriers such as propylene glycol, ethanol, ethyl acetate, or triacetin has become a key differentiator, particularly for customers requiring customized integration into complex formulation workflows.
PW Consulting
Policy and Regulatory Environment
Regulatory frameworks continue to act as both a barrier to entry and a catalyst for market consolidation. The compound’s recognized status in food flavoring applications provides a solid baseline for commercial use, but the operational burden associated with certification maintenance, documentation rigor, and regional compliance varies significantly across markets. Manufacturers serving pharmaceutical intermediate applications face additional layers of quality assurance and traceability requirements, which elevate the cost of compliance but also create higher switching costs for customers. In this environment, suppliers that can provide certified documentation, standardized analytical certificates, and consistent regulatory readiness across multiple jurisdictions gain a structural advantage. The trend toward stricter oversight on ingredient sourcing and labeling accuracy further benefits producers with transparent supply chains and clearly defined origin claims, while increasing the risk profile for operators that cannot substantiate product specifications or maintain audit-ready quality systems.
Demand-Side Evolution in Consumer and Industrial Behavior
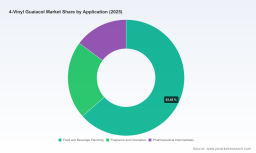
Downstream demand is being reshaped by a combination of consumer preference shifts and industrial reformulation activity. In the food and beverage sector, the pursuit of cleaner labels and authentic sensory profiles has reinforced the value of 4-VG’s characteristic aroma profile, which delivers clove-like, smoky, and spicy notes that are difficult to replicate with alternative compounds. Fragrance and cosmetic applications continue to leverage its olfactory properties, though volume growth in this segment remains more modest compared to flavor applications. Meanwhile, the pharmaceutical intermediates segment represents a specialized but high-value pathway, where demand is driven by formulation requirements and the need for high-purity intermediates rather than consumer-facing trends. Across these applications, buyers are increasingly favoring suppliers that can offer grade flexibility, application-specific dilutions, and reliable delivery performance, reflecting a broader shift from price-centric procurement to value-centric supplier evaluation.
Supply Chain and Cost Structure Dynamics
The cost structure of 4-VG production remains sensitive to agricultural commodity cycles, processing efficiency, and logistics complexity. Feedstock availability is inherently seasonal, and competing demand for bran-derived materials can create periods of constrained supply and elevated pricing. Manufacturers that rely on single-source or regionally concentrated feedstock inputs face higher exposure to price swings and supply interruptions, whereas those with diversified agricultural sourcing, strategic inventory management, or integrated fermentation-based production can smooth cost variability and improve margin predictability. Logistics and distribution also play a critical role, particularly for global customers requiring consistent supply across multiple regions. Suppliers with established distribution networks and the ability to maintain quality integrity across transport and storage conditions are better equipped to serve international demand without compromising specification compliance or delivery reliability.
The competitive landscape is characterized by a mix of specialized producers, global distributors, and research-grade suppliers, each occupying distinct strategic niches. Foreverest Resources Ltd. has positioned itself around naturally extracted, bio-based 4-VG derived from corn ethanol fermentation volatiles, targeting flavor and fragrance applications with fermented, sweet, clove-like profiles. This natural-origin positioning provides a clear differentiation angle in markets where clean-label demand and ingredient transparency are increasingly valued. Penta International operates across multiple grades, offering pure, natural, and synthetic versions with diluted formulations in various carriers, enabling it to serve a broad spectrum of flavor and fragrance customer requirements with application-specific flexibility. Simson Pharma Limited emphasizes custom synthesis and high-quality manufacturing with formal analytical documentation, aligning with customers that require tailored specifications and compliance-ready supply for pharmaceutical and specialty chemical use. Parchem Fine & Specialty Chemicals functions as a global distributor and supplier, leveraging broad chemical distribution capabilities to serve specialty chemical applications across international markets. United Aromatics and Gogia Chemical Industries focus on food-grade, certified production and aroma chemical applications, with emphasis on Kosher and Halal certifications and characteristic odor profiles suited for flavoring use. Aroma Aromatics & Flavours and R C Treatt & Co Ltd contribute additional regional and specialized supply capabilities, with the latter emphasizing high-impact aroma chemical positioning. Sigma-Aldrich (MilliporeSigma) serves the research, analytical, and flavor/fragrance segments with certified quality documentation, supporting laboratory-scale and specification-driven demand that underpins broader market development.
The strategic positioning of these players highlights several recurring advantages. Natural-origin and bio-based production pathways are becoming increasingly important for differentiation, particularly where downstream customers seek to substantiate clean-label claims. Grade flexibility and dilution capability allow suppliers to address diverse formulation needs without requiring customers to manage additional processing steps. Certification readiness and documentation rigor reduce friction for buyers operating in regulated environments, effectively raising switching costs for competitors that lack equivalent compliance infrastructure. Geographic diversification and distribution reach also matter, as global customers increasingly prefer suppliers that can deliver consistent quality across multiple markets without relying on fragmented local sourcing.
Market evolution is moving toward a hybrid pattern of consolidation and specialization. The moderate concentration among top players indicates that scale and distribution advantages continue to matter, but the presence of multiple regional and application-focused producers suggests that niche differentiation remains viable. New entrants and smaller manufacturers can compete by targeting specific grade requirements, certification profiles, or regional demand pockets, while larger or more diversified suppliers may pursue consolidation to strengthen supply chain control and broaden application coverage. The likely trajectory is not a uniform shakeout but a continued layering of specialized offerings within a broader market structure, where success depends on aligning production capabilities with the most valuable demand segments and maintaining compliance and quality systems that meet evolving buyer expectations.
4 Bromoanisole Market
Future Trends and Commercial Implications (2026–2030)
Looking ahead, several trends are likely to shape the market’s direction and create actionable opportunities for well-positioned participants.
- Bio-based and natural-origin production will become a stronger commercial differentiator. As downstream buyers increasingly prioritize traceable, naturally derived ingredients, fermentation-based and bio-extracted pathways are expected to gain share relative to purely synthetic routes. This trend favors producers that can reliably deliver natural-origin claims alongside consistent purity and application-ready formats. Commercial opportunities will emerge for suppliers that can bundle origin transparency with grade flexibility and documentation support, particularly in flavor and fragrance segments where sensory authenticity and labeling integrity are closely linked.
- Regulatory and certification requirements will continue to raise the bar for market access. The operational expectation for certified quality documentation, food-grade compliance, and region-specific certifications is likely to intensify rather than stabilize. Suppliers that proactively invest in compliance infrastructure and maintain audit-ready systems will benefit from higher customer retention and the ability to serve regulated application areas with less friction. This trend also creates entry barriers for smaller operators that cannot sustain the documentation and quality system requirements, potentially reinforcing the position of established producers with robust compliance capabilities.
- Supply chain resilience and feedstock diversification will become strategic priorities. Given the sensitivity of ferulic acid-derived production to agricultural cycles and regional pricing volatility, manufacturers that diversify feedstock sources, secure longer-term supply agreements, or integrate alternative bio-based pathways will be better equipped to manage cost variability and maintain delivery reliability. Commercial value will shift toward suppliers that can offer predictable timing, consistent specification integrity, and reduced exposure to seasonal feedstock disruptions, especially for customers operating just-in-time formulation schedules or multi-region production footprints.
These trends are not without uncertainty. Feedstock pricing remains subject to agricultural production cycles and competing demand, which can compress margins if not managed through sourcing strategy or product mix optimization. Regulatory frameworks may evolve unevenly across regions, creating compliance complexity for global suppliers and requiring continuous monitoring of certification and labeling expectations. Demand growth in fragrance and cosmetic applications, while steady, may lag behind flavor-driven expansion, meaning that overconcentration in slower-growth segments could limit overall portfolio performance. Additionally, the entry of new producers and the expansion of bio-based alternatives could intensify competition in specific grade categories, putting pressure on pricing for undifferentiated offerings. Companies that treat these uncertainties as strategic variables rather than static background conditions will be better positioned to adapt product portfolios, supply contracts, and customer engagement models as the market evolves.
Strategic Recommendations for Decision-Makers
For manufacturers, the most effective path forward is to align production capabilities with the segments where differentiation commands the strongest commercial return. Investing in fermentation-based or diversified bio-based production, expanding grade and dilution flexibility, and strengthening certification documentation can improve positioning in flavor, fragrance, and specialty chemical applications while reducing vulnerability to feedstock price swings. For investors, the market’s moderate concentration and ongoing demand shift toward natural-origin ingredients suggest that value creation will accrue to operators with clear application focus, compliance readiness, and supply chain resilience rather than to undifferentiated volume players. Evaluating target companies against feedstock diversification, certification breadth, and grade flexibility provides a more reliable indicator of long-term competitiveness than revenue scale alone. For procurement and sourcing teams, supplier selection should increasingly weigh origin transparency, documentation reliability, and delivery consistency alongside price. Building partnerships with suppliers that can offer application-specific grades, certified quality support, and predictable supply performance can reduce reformulation risk and improve downstream product consistency.
4-Cumylphenol Market
Given the interplay of feedstock volatility, evolving regulatory expectations, and shifting demand preferences, market participants benefit from access to detailed segment-level data, regional demand patterns, and company-specific capability profiles. More granular visibility into grade-level pricing dynamics, certification coverage, and application growth rates can support more precise sourcing decisions, investment prioritization, and product roadmap planning. For those seeking a deeper competitive mapping and customized scenario analysis, the full research report provides expanded segmentation detail, company benchmarking, and forward-looking market modeling to support strategic planning across manufacturing, investment, and procurement functions.
For detailed analysis of this topic, please visit the official page: Worldwide 4-Vinyl Guaiacol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com