

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global Car-Sharing Market: Why 13.45% CAGR Reshapes Competition by 2032

Global Car-Sharing Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The worldwide car-sharing market has transitioned from a novelty service to a structural component of urban mobility. Revenue expanded from approximately $7.5 billion in 2020 to an estimated $14.7 billion in 2025, reflecting a compound annual growth rate of 13.45% through the forecast horizon ending in 2032. By the close of the projection period, market revenue is expected to approach $35.6 billion, driven by fleet expansion, rising membership volumes, and deeper integration with multimodal transport networks. The sector's trajectory is not uniform, however. Growth is concentrated among established operators, with the top three firms accounting for roughly 42% of global revenue and the top five capturing nearly 59%, signaling a landscape where scale, technology adoption, and regional density determine competitive advantage.
Despite robust top-line momentum, the industry confronts three interconnected challenges that will shape strategic decisions over the next several years. First, cost pressures and regulatory friction are forcing operational restructuring. Operators in dense urban markets are grappling with congestion pricing, parking scarcity, and rising insurance and maintenance expenses. Recent closures of international operations by station-based players highlight how localized cost structures and policy environments can quickly erode margins, even for brands with strong brand recognition. Second, technology dependency is shifting from a competitive differentiator to a baseline requirement. Fleet management, keyless access, and dynamic pricing now rely heavily on specialized telematics and software platforms, creating a new layer of vendor concentration and integration complexity. Third, fleet connectivity standards are undergoing a forced upgrade cycle. As telecommunications networks retire legacy 2G and 3G infrastructure, operators must modernize vehicle connectivity to maintain remote access, telemetry, and operational control, triggering capital expenditure timing mismatches and potential service disruptions if migration is poorly sequenced.
These pressures are not purely defensive. They are accelerating a structural re-sorting of the market, where operators that can align fleet composition, connectivity, and local policy conditions are gaining ground, while those locked into rigid models or aging technology stacks face narrowing margins. For decision-makers, the immediate implication is that market size alone no longer signals opportunity; the value lies in identifying which operational models, vehicle types, and regional contexts can sustain unit economics as the sector matures.
Key Drivers Shaping the Market
Several forces are converging to redefine how car-sharing scales, where profitability emerges, and which players can sustain long-term relevance. The first is technology adoption that extends beyond the smartphone app. Modern operations increasingly depend on integrated telematics, automated vehicle access, and fleet orchestration software supplied by specialized platform providers. These systems enable real-time utilization tracking, dynamic pricing, remote diagnostics, and seamless keyless entry, reducing manual overhead and improving asset utilization. As fleets grow toward projected volumes exceeding 750,000 shared vehicles by 2029 and membership approaches 138 million, the operational complexity of managing distributed assets becomes a decisive factor. Operators that standardize on robust software stacks can scale more efficiently, while those piecing together fragmented tools face higher integration risk and slower reaction times to demand fluctuations.
PW Consulting
The second driver is the evolving regulatory and policy environment, which is creating both constraints and tailwinds. Urban authorities continue to shape car-sharing through parking policy, congestion pricing, low-emission zones, and incentives for cleaner fleets. In parallel, broader vehicle emission standards are shifting in certain markets, altering the compliance calculus for fleet procurement. While some jurisdictions have eased certain emission requirements for new vehicles, the practical direction for shared mobility still favors lower operating costs, reduced maintenance exposure, and alignment with municipal sustainability goals. Operators that can navigate local policy variability while maintaining flexible fleet strategies are better positioned to retain access to high-density urban zones where utilization rates are highest.
The third driver is demand-side behavior, which is bifurcating rather than simply expanding. Urban consumers continue to value short-duration access for occasional trips, but they increasingly expect seamless booking, transparent pricing, and reliable vehicle availability. Meanwhile, corporate and institutional buyers are adopting car-sharing as part of broader mobility and fleet management strategies, seeking to reduce idle assets, simplify administration, and support sustainability targets. This dual demand profile is expanding the addressable market beyond individual members to include business accounts, tourism segments, and integrated travel packages. Recent partnerships that connect self-drive rental options with international visitors and local inspection and tracking services illustrate how operators are broadening their reach by embedding car-sharing into adjacent travel and quality-assurance workflows.
The fourth driver is the shifting cost and supply structure of fleet procurement and maintenance. Vehicle availability, residual values, and total cost of ownership vary significantly by powertrain type and region, influencing which assets are economically viable for shared use. Electrified vehicles are gaining share in the global fleet mix, where lower fuel and maintenance costs can support utilization economics, but charging infrastructure, range expectations, and upfront acquisition costs still vary by market readiness. Hybrid and internal combustion assets remain relevant where charging density is limited or trip patterns demand longer range flexibility. The result is a more deliberate fleet composition strategy, where operators match vehicle type to local utilization patterns, charging access, and policy incentives rather than pursuing uniform electrification across all markets.
Competitive Landscape and Leading Strategies
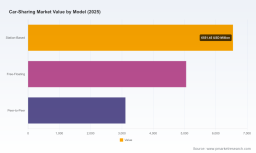
The competitive field spans global platforms, regional specialists, rental-adjacent brands, and cooperative models, each pursuing a distinct path to sustainable unit economics. One clear divide is between station-based and free-floating operations. Station-based services benefit from predictable parking locations, easier fleet rebalancing, and stronger integration with membership-oriented users, making them attractive in markets where parking control and operational discipline support margin stability. Free-floating models offer greater convenience and spontaneous access, but they require sophisticated telemetry, dense city coverage, and robust rebalancing logic to manage one-way trips and vehicle distribution. Peer-to-peer platforms occupy a different position, leveraging private vehicle owners to expand supply without direct fleet ownership, which lowers capital intensity but introduces quality control, insurance, and trust management challenges.
Carpooling Market
Leading operators are differentiating through ecosystem integration rather than pure vehicle access. Some have embedded car-sharing within broader rental networks, allowing them to cross-sell short-term access, transfer fleet assets across use cases, and leverage established maintenance and customer service infrastructure. Others have built mobility platforms that combine free-floating and station-based options under a single brand, aiming to capture both planned and spontaneous trips while smoothing utilization across day-parts. Premium and electric-focused fleets are being used as a positioning lever in markets where brand perception, corporate account demand, and policy incentives support higher-value vehicles. Cooperative and community-oriented models continue to play a role in specific regions, emphasizing sustainable mobility and public transport integration rather than pure scale.
Recent developments illustrate how the landscape is evolving through partnerships, operational consolidation, and technology dependence. Rental and mobility brands are extending into adjacent vectors, including fleet partnerships that bridge driver-led and autonomous operations, signaling a longer-term ambition to control more of the on-demand mobility value chain. In emerging and tourism-oriented markets, operators are forming alliances to improve vehicle inspection quality, tracking reliability, and access to international travelers, addressing two persistent barriers to trust and utilization. At the same time, the exit from certain international markets by established station-based players underscores that brand presence alone does not guarantee viability; cost structures, local policy exposure, and operational density must align. Across the board, reliance on third-party telematics and fleet software is becoming a structural feature of the industry, meaning competitive advantage increasingly depends on how well operators integrate these platforms, manage upgrade cycles, and maintain service continuity during connectivity transitions.
The market is moving toward a more segmented and partnership-dependent structure. Scale players are consolidating operational control where they can, while regional specialists are pursuing depth in specific cities or vehicle segments. New entrants face a higher barrier to traction because operational maturity, software integration, and local policy navigation now matter as much as capital. For investors and corporate strategists, the relevant question is less about who has the most vehicles today and more about which operators can sustain utilization, manage connectivity upgrades, and adapt fleet composition to local conditions without eroding margins.
Forward-Looking Trends for the Next Three to Five Years
One major trend is the acceleration of fleet modernization and connectivity migration. As legacy network shutdowns progress, operators will need to sequence hardware upgrades, software updates, and back-end integration to preserve keyless access and telemetry. Companies that plan this transition as a structured program, rather than a reactive swap, will reduce downtime risk and maintain service reliability while improving data quality for pricing and maintenance decisions. This creates an opportunity for technology vendors and operators that can offer migration pathways with minimal disruption and clear total-cost-of-ownership benefits.
A second trend is the continued segmentation of business models by city type and demand profile. High-density urban centers will keep favoring free-floating and station-based services where utilization can be sustained, but secondary cities, tourist corridors, and corporate accounts may offer more predictable economics through membership-driven, station-based, or managed P2P arrangements. Operators that can modularize their offering by market type, rather than applying a single template globally, are more likely to protect unit economics. This also opens doors for localized partnerships with tourism providers, corporate mobility programs, and public transport integration initiatives.
A third trend is the deepening link between fleet composition and local infrastructure readiness. Electrified shared vehicles will continue to grow where charging access, maintenance capacity, and policy support are aligned, while hybrid and internal combustion assets will remain practical in markets with range or charging constraints. The commercial opportunity lies in matching vehicle mix to real utilization patterns and operating conditions, then using telematics to optimize deployment, charging schedules, and maintenance windows. The primary risk is over-indexing on a single powertrain strategy before local infrastructure and user behavior support it, which can increase idle time, reduce availability, and pressure margins.
Strategic Actions for Decision-Makers
For vehicle manufacturers and supply-side players, the priority is to align product planning with shared-use operating realities. Shared fleets impose different wear patterns, availability expectations, and connectivity requirements than personal ownership, so durability, serviceability, and integrated telematics are increasingly relevant selling points. Engaging operators early on fleet composition, upgrade cycles, and connectivity migration can create longer-term supply relationships and reduce time-to-value for new vehicle programs.
For investors, the most useful lens is operational resilience rather than headline fleet size. Evaluate how well a platform manages software dependence, vehicle connectivity transitions, local regulatory exposure, and rebalancing logic. Business models that can shift between station-based, free-floating, and managed peer-to-peer formats by market, while maintaining disciplined cost structures, are better positioned to survive operational shocks and capture demand from both individual and corporate users.
For corporate mobility buyers and procurement teams, car-sharing should be assessed as part of a broader access-and-utilization strategy. The strongest value comes from combining short-term shared access with existing rental, fleet, and public transport options, then using data on utilization and trip patterns to right-size owned assets. Selecting partners with reliable vehicle availability, clear insurance and maintenance frameworks, and integration capabilities will determine whether car-sharing delivers efficiency gains or simply adds another vendor layer.
Ride Sharing Market
For organizations seeking a detailed view of regional segmentation, fleet-size trajectories, model-level dynamics, and company-specific positioning, a fuller research briefing can provide the granularity needed to translate these market-level trends into targeted entry, investment, or procurement decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Car-Sharing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com