

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Tuberculosis Therapeutics Market: Why 5.82% CAGR Reshapes Strategy

Beyond the Headlines: Strategic Shifts and Commercial Opportunities in the Global Tuberculosis Therapeutics Market
Market Landscape and Core Challenges
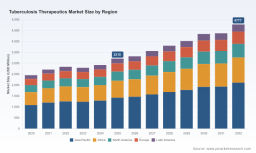
The global market for tuberculosis therapeutics continues its steady climb, moving from approximately $2.45 billion in 2020 to an estimated $3.22 billion in 2025. Over the 2026-2032 horizon, the sector is projected to expand at a compound annual growth rate of 5.82 percent, reaching roughly $4.78 billion by 2032. This growth trajectory reflects a market in transition, where incremental demand expansion converges with structural shifts in treatment paradigms, drug accessibility, and funding dynamics. The numbers alone, however, mask the uneven distribution of need and the operational friction that defines commercial execution across diverse epidemiological settings.
One defining characteristic of the current landscape is the persistent gap between treatment access and actual disease burden. Treatment success rates for drug-susceptible cases have stabilized near 88 percent, and outcomes for drug-resistant forms have improved to around 71 percent based on recent reporting cycles. Yet only a fraction of estimated rifampicin-resistant cases are initiating therapy in any given year. This treatment cascade gap creates a paradox for manufacturers and procurement organizations: demand exists in clinical terms, but conversion into sustained market volume depends on diagnostic reach, care delivery capacity, and reimbursement structures that remain underdeveloped in high-burden regions.
A second challenge lies in the funding architecture supporting tuberculosis programs. Global spending on prevention, diagnosis, and treatment remains well below the annual target required to meet international control goals. This financing shortfall influences procurement behavior, pricing negotiations, and the willingness of national programs to adopt newer, higher-cost regimens. Companies operating in this space must navigate a demand environment where clinical value does not automatically translate into immediate purchasing power, particularly in settings dependent on pooled procurement and donor-supported supply channels.
The third pivot point is the rapidly evolving therapeutic standard itself. Health authorities have increasingly endorsed shorter, all-oral regimens for drug-resistant forms, shifting the competitive center of gravity away from prolonged injectable-based protocols toward regimens that are easier to deliver and more tolerable for patients. This change is reshaping volume forecasts, pricing expectations, and manufacturing priorities. At the same time, important patent milestones are unfolding for cornerstone products, opening the door to broader generic participation and potential price compression. The combined effect is a market where clinical innovation, intellectual property dynamics, and procurement strategy are becoming tightly entangled.
Key Drivers Reshaping the Market
Therapeutic Innovation and Regimen Simplification
One of the most consequential drivers is the push toward shorter, more tolerable treatment regimens. Newer molecules and novel combinations are being positioned not merely as alternatives, but as potential replacements for multi-month protocols that have historically challenged patient adherence and program logistics. Recent Phase 3 activity around next-generation candidates for drug-resistant pulmonary tuberculosis signals that pipeline momentum is shifting from incremental improvements to potentially transformative regimens. At the same time, mid-stage readouts suggesting the possibility of further duration reduction reinforce a strategic direction favored by both clinicians and public health programs: fewer pills, shorter courses, and all-oral delivery whenever feasible.
For commercial stakeholders, this innovation wave alters the value proposition of existing products. Shorter treatment durations can improve completion rates and reduce follow-up burden, but they may also compress per-patient revenue unless offset by higher uptake, broader indications, or differentiated positioning. Manufacturers with late-stage candidates are therefore balancing clinical differentiation against the operational reality that procurement agencies prioritize simplicity and predictability. The alignment between clinical benefit and programmatic feasibility is becoming a key determinant of adoption speed.
PW Consulting
Regulatory Endorsements and Access-Focused Policy Shifts
Regulatory and guideline developments are actively reshaping the competitive landscape. Recent full regulatory approval of a key bedaquiline-based use for pulmonary multidrug-resistant tuberculosis as part of combination therapy exemplifies how expanded labeling can widen the addressable patient population for newer agents. Equally important are guideline recommendations favoring shorter all-oral regimens for drug-resistant forms, which effectively raise the standard of care and influence procurement specifications across multiple markets.
Policy engagement around access is also intensifying. Recent patent-related opposition actions in key markets illustrate the growing intersection of intellectual property strategy and public health access goals. These activities are not merely legal events; they influence market entry timing, generic availability, and pricing expectations. In an environment where access-oriented advocacy and regulatory clarity are both advancing, companies that anticipate scrutiny on exclusivity windows and price levels may be better positioned to negotiate supply arrangements before competitive pressure intensifies.
Demand-Side Changes and Procurement Realities
Demand is evolving not only through epidemiology but also through programmatic priorities. National tuberculosis programs and global procurement mechanisms increasingly favor regimens that reduce logistical complexity, minimize monitoring requirements, and fit within constrained health system capacity. This preference is particularly pronounced in high-burden settings where workforce constraints and patient retention challenges make treatment simplicity a strategic priority rather than a convenience.
At the same time, demand conversion remains sensitive to funding. The persistent gap between actual global spending and the level needed for comprehensive control means that procurement decisions often depend on tiered pricing, donor participation, and multilateral supply platforms. For suppliers, this translates into a need to design commercial models that can accommodate volume variability, price sensitivity, and the timing of replenishment cycles. Products that can demonstrate both clinical superiority and cost-effective delivery are more likely to secure sustained placement in national formularies and pooled procurement arrangements.
Cost Structure and Supply-Side Dynamics
The cost environment is being reshaped by both pricing actions and manufacturing accessibility. In recent years, originator pricing on an important drug-resistant tuberculosis therapy has been adjusted downward in select markets, while generic pathways have expanded in countries with high disease burden. These developments have introduced meaningful price differentiation between branded and generic offerings, especially where pooled procurement and humanitarian supply channels are active. Lower per-course pricing can expand access, but it also pressures margins and forces manufacturers to think carefully about volume commitments, capacity allocation, and market segmentation.
On the supply side, the role of generics and active pharmaceutical ingredient providers is becoming more central. Large generic manufacturers already supply a wide range of first-line and second-line therapies globally, and their continued expansion into newer molecules will influence both availability and price trajectories as exclusivity recedes. For the broader market, this suggests a future in which access is increasingly determined by supply chain reliability, regulatory speed in multiple jurisdictions, and the ability to maintain consistent quality at scale.
Competitive Landscape and Leading Strategies
The market features a blend of specialty innovators, large diversified pharmaceutical companies, and generic manufacturers with strong public health supply roles. The competitive logic is not uniform across these groups. Innovators focused on drug-resistant tuberculosis are competing on regimen differentiation, trial momentum, and positioning within evolving guideline recommendations. Generic suppliers are competing on volume reliability, price, and integration with global procurement networks. The most strategically interesting dynamics emerge where these streams intersect, especially as newer molecules approach broader availability.
Positioning Among Innovators
Among the companies leading in drug-resistant tuberculosis, one distinctive strategy is building around a core molecule that has become embedded in combination therapy. By expanding regulatory support, engaging in collaborative regimen development efforts, and navigating access questions through selective pricing and production flexibility, this player has reinforced its role in multidrug-resistant treatment pathways. The strategic value lies in maintaining relevance as regimens evolve while managing the tension between exclusivity benefits and access pressures.
Another innovator is pursuing a pipeline-oriented approach, advancing a next-generation candidate into pivotal testing for drug-resistant pulmonary disease while maintaining its established therapy for resistant forms. This dual posture creates optionality: current revenue and credibility from an approved product support continued investment in a candidate that could reposition the company if shorter or more effective regimens become standard. The strategic emphasis here is on staying ahead of guideline shifts rather than merely responding to them.
Tuberculin Market
A non-profit developer has carved out a different kind of advantage by focusing on highly drug-resistant populations and shorter all-oral cures. Its regimen development model, combined with a broad pipeline and a public-interest orientation, gives it influence in guideline discussions and procurement conversations where difficult-to-treat cases create urgency for new options. In this space, differentiation comes from clinical outcomes in the hardest populations and from the ability to shape multi-stakeholder adoption.
The Generic Manufacturing Layer and Access Channels
Generic manufacturers in India and other production hubs play an increasingly important role because they connect supply capacity with global access programs. Many of these firms produce first-line and second-line therapies at scale, and several have expanded into competitive offerings of newer molecules through public health supply channels. Their strategic strength lies in manufacturing efficiency, regulatory breadth, and established relationships with procurement platforms that distribute medicines to national programs.
Large diversified pharmaceutical companies contribute a different value: established anti-tuberculosis agents, global supply capabilities, and participation in access-oriented initiatives. Their presence reinforces the stability of core treatment components and provides procurement systems with reliable sourcing options. Meanwhile, companies specializing in active pharmaceutical ingredients and formulations add further depth to the supply base, which becomes critical as demand for newer regimens expands and as multiple manufacturers prepare for wider generic participation.
Market Structure Trajectory
The competitive landscape is moving toward greater differentiation between innovation-led and volume-led business models, even as the boundary between them becomes more porous. Patent expirations and access-driven pricing adjustments are expected to widen the field for generic entrants in specific product categories, which could intensify price competition and compress margins in mature segments. At the same time, the emphasis on shorter, all-oral regimens may reward companies that can deliver clinically differentiated combinations or that can secure early placement in national guidelines and pooled procurement frameworks. Consolidation dynamics are less about immediate merger activity and more about the gradual concentration of influence among players that can combine clinical credibility, supply reliability, and access strategy in a single portfolio.
Future Trends and Commercial Implications
Over the next three to five years, one of the clearest trends will be the wider adoption of shorter all-oral regimens as the operational norm for drug-resistant tuberculosis in an increasing number of markets. As guidelines and procurement specifications align around these regimens, volume patterns will shift away from older, longer protocols and toward combination-based treatments that demand more coordinated sourcing and more precise forecasting. Companies that can support this transition with reliable supply, clear pricing structures, and regulatory readiness across multiple jurisdictions will be better positioned to capture adoption-led growth.
A second trend will be the gradual broad basing of the competitive field as exclusivity windows narrow for important products. Generic entry, where enabled by patent timelines and local regulatory pathways, can increase availability and reduce per-patient cost, but it may also fragment demand among more suppliers and place greater emphasis on differentiation through service, logistics, and procurement partnerships. In this environment, commercial advantage may depend less on product uniqueness alone and more on the ability to integrate into access programs, maintain consistent availability, and manage price expectations without undermining supply commitments.
A third trend is the growing importance of funding alignment. Even as clinical options improve, scale-up will remain tied to the willingness and ability of national programs and global funders to close the financing gap. This creates a structural uncertainty for forecast-driven planning: innovative products may be clinically ready long before procurement systems can absorb them at volume. Firms that anticipate funding cycles, build flexible pricing tiers, and invest in access-oriented distribution models will be more resilient than those relying on a single commercial pathway. The principal risk is that clinical progress outpaces budgetary capacity, leading to slow uptake in settings where the need is greatest.
Strategic Actions for Decision-Makers
For manufacturers and developers, the priority is to align product strategy with the direction of care delivery rather than with legacy volume assumptions. That means preparing for regimen-centric demand, evaluating how pricing and supply models will hold up if access pressure increases, and ensuring that late-stage programs are supported by clear positioning in guideline and procurement conversations. Companies should also map the likely impact of patent milestones and generic entry on their portfolio mix so that they can adjust capacity, partnering, and market focus before competitive dynamics shift abruptly.
Peptide Therapeutics Market
For investors, the most useful lens is to assess not only clinical differentiation but also commercial durability under access-constrained conditions. Assets that demonstrate shorter treatment potential, all-oral feasibility, and compatibility with pooled procurement and tiered pricing models may offer more defensible growth than products that depend on premium pricing in funding-limited environments. Equally important is monitoring how quickly markets respond once regulatory and guideline thresholds are crossed, because adoption timing often determines whether therapeutic advantage translates into sustainable revenue.
For procurement organizations and program leaders, the strategic imperative is to balance cost containment with regimen quality. Short-term savings from older therapies can be undermined by adherence challenges, longer treatment durations, and higher downstream system costs. Prioritizing supply security, forecasting accuracy, and supplier diversification will reduce exposure to disruptions as procurement volumes shift toward newer regimens. In parallel, maintaining space for evidence-based adoption of shorter, all-oral options can improve programmatic outcomes while helping stabilize long-term demand patterns.
As the market continues to evolve, the difference between tactical participation and strategic advantage will come down to how well organizations can read the interaction among clinical change, access policy, and procurement economics. Detailed segmentation data, country-level procurement signals, and scenario-based forecasts can help decision-makers convert these broad trends into specific plans that fit their portfolios and operating models.
For detailed analysis of this topic, please visit the official page: Worldwide Tuberculosis Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com