

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Defense Big Data Market Hits $28.5B in 2025, Projected $67.7B by 2032 at 13.15% CAGR

Strategic Intelligence in the Age of Autonomous Defense: Inside the Global Big Data Analytics Market
The defense and aerospace sectors are undergoing a foundational transformation. The shift from platform-centric operations to data-centric decision-making is no longer a conceptual roadmap—it is an operational imperative. As sensor networks expand, multi-domain operations become standard, and artificial intelligence moves from experimental pilots to deployed mission systems, the ability to capture, process, and act upon massive data streams has become a decisive competitive advantage. Our latest Worldwide Big Data Analytics In Defense and Aerospace Market research study provides a comprehensive, forward-looking assessment of this rapidly consolidating landscape, offering enterprise leaders and government stakeholders the analytical framework needed to navigate the next phase of strategic investment.
This report is not a static snapshot. It is a strategically calibrated intelligence instrument designed to support capital allocation, partnership strategy, supply chain positioning, and technology roadmapping through 2032. Built on a rigorous historical baseline spanning 2020 through 2025, the analysis extends into a detailed forecast period that captures compounding adoption cycles, procurement acceleration, and the maturation of enterprise-grade analytics architectures. The resulting dataset reveals a market that has already crossed the threshold from emerging capability to mission-critical infrastructure, with momentum that shows no signs of plateauing.
The Scale and Trajectory of a Compounding Market
Readers familiar with traditional aerospace and defense procurement cycles often expect linear growth patterns driven by multi-year acquisition calendars and platform lifecycles. Big data analytics has disrupted that assumption. Over the historical observation window, the market expanded from a base of approximately $15.48 billion in 2020 to a projected $28.52 billion by 2025, reflecting sustained double-digit expansion across both commercial technology integration and sovereign defense modernization programs. This trajectory is not merely the result of incremental IT spending; it represents a structural reallocation of budgets toward data fusion, predictive analytics, and automated decision-support systems that directly impact mission readiness and operational throughput.
The forecast horizon reinforces the acceleration thesis. From 2026 onward, the market is projected to maintain a robust compound annual growth rate of 13.15 percent, reaching substantial scale by the close of the decade and continuing to climb through 2032. This growth reflects several converging forces: the urgent need to extract actionable intelligence from proliferating sensor and telemetry data, the operationalization of cloud-native analytics platforms across secure environments, and the integration of predictive maintenance and logistics optimization into core aerospace manufacturing and fleet management workflows. Critically, the expansion is not uniform. Adoption intensity varies by mission domain, regional procurement posture, and the maturity of underlying technology ecosystems, creating differentiated opportunities for firms that understand where value is actually being captured on the ground and in the field.
For executives and investors, the strategic implication is clear. This is a market where timing matters, but positioning matters more. Organizations that delay analytics integration in favor of legacy data architectures will find themselves structurally disadvantaged as peer programs demonstrate faster cycle times, higher asset utilization, and more resilient supply chains. The data tells a consistent story: the cost of inaction is compounding.
Defense Asset Management Software Market
Decoding the Report: What Decision-Makers Will Find Inside
A market report only earns its place on an executive dashboard if it translates macro trends into actionable intelligence. This study was engineered with that principle at its core. Rather than presenting high-level narratives disconnected from procurement reality, the analysis is structured around the operational dimensions that actually shape investment decisions in defense and aerospace.
Market Architecture and Segmentation Logic
The report breaks down the market along three foundational axes that matter to buyers, suppliers, and technology integrators. First, it examines the component landscape, distinguishing between software-driven analytics platforms and the services ecosystem that surrounds deployment, integration, customization, and ongoing mission support. Understanding the split between these two layers is essential for assessing total cost of ownership, vendor dependency, and the pace at which analytical capabilities can be scaled across enterprise environments.
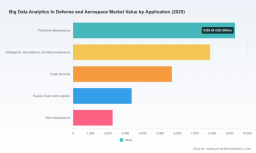
Second, the analysis maps the application landscape across the mission domains where data intensity is highest. Predictive maintenance stands out as a primary value driver, reflecting the aerospace industry's relentless focus on asset availability, lifecycle cost reduction, and operational safety. Intelligence, surveillance, and reconnaissance applications represent another major demand center, where multi-source data fusion and real-time analytics directly influence situational awareness and decision velocity. Cyber security, supply chain and logistics, and a range of other specialized applications complete the mission portfolio, each with distinct adoption triggers, procurement pathways, and technology requirements.
Third, the geographic architecture of the market is examined with an eye toward procurement dynamics, partnership ecosystems, and regional modernization priorities. Rather than treating geography as a simple revenue breakdown, the report contextualizes regional demand within the framework of sovereign capability development, alliance interoperability requirements, and the localization expectations that increasingly shape cross-border technology deployments.
Competitive Positioning and Strategic Benchmarking
No market analysis is complete without a granular view of the competitive field. This report profiles the organizations that are defining the standard for big data analytics in defense and aerospace, combining corporate capabilities, technological positioning, and recent strategic moves into a cohesive competitive landscape assessment. The profiled ecosystem includes both incumbent defense prime contractors and specialized technology providers, each pursuing distinct routes to market.
Among the defense and systems integrators, the analysis examines how organizations such as Boeing Defense, Space & Security, Lockheed Martin, Northrop Grumman, RTX Corporation, BAE Systems, General Dynamics, L3Harris Technologies, Thales Group, and Honeywell are embedding analytics into production environments, platform architectures, ISR systems, and mission support workflows. The report also assesses the role of enterprise technology and AI-focused firms—including Palantir Technologies, IBM, Microsoft, Oracle, C3 AI, and Booz Allen Hamilton—in providing the foundational platforms, cloud infrastructure, and mission-aligned analytics capabilities that enable scaled deployment across secure and classified environments.
The competitive assessment goes beyond static capability mappings. It draws on recent developments that signal how the market is actually evolving. For example, the September 2025 partnership between Boeing Defense, Space & Security and Palantir Technologies to integrate AI-driven analytics using the Foundry platform across defense factories and classified programs illustrates the accelerating convergence of production optimization and mission analytics. Similarly, the US Space Force's March 2025 Data and AI FY2025 Strategic Action Plan underscores the institutional prioritization of enterprise-wide data governance, analytics adoption, and partnership-driven capability development. The July 2025 contract awards by the DoD Chief Digital and Artificial Intelligence Office—worth up to $200 million each to frontier AI companies including Anthropic, Google, OpenAI, and xAI to develop agentic AI workflows for national security and warfighting missions—further demonstrates the speed at which advanced analytics and AI are being institutionalized at the highest levels of defense procurement.
Regulatory and Technical Realities Shaping Deployment
Market growth does not occur in a vacuum. This report integrates the regulatory, technical, and certification dynamics that determine how quickly analytics capabilities can be deployed, scaled, and sustained in defense and aerospace environments. Cybersecurity compliance remains a persistent gating factor. Contractors managing sensitive analytics systems must navigate CMMC requirements and NIST 800-171 standards, and these obligations shape everything from architecture design to vendor selection and cross-organizational data sharing.
Export controls add another layer of complexity. ITAR and EAR regulations govern the transfer of analytics technologies and associated technical data, requiring rigorous licensing frameworks for international cooperation and commercial teaming. Simultaneously, the technical reality of big data analytics in this sector demands high-performance computing infrastructure, secure cloud platforms, and edge computing capabilities capable of supporting real-time sensor fusion and large-scale multi-source data processing. Emerging AI trustworthiness frameworks, building on established certification precedents such as RTCA DO-178C for software, are also being developed to address safety and certification requirements for AI-enabled analytics in aerospace systems. The report provides decision-makers with the contextual understanding needed to anticipate compliance friction, plan architecture accordingly, and align go-to-market strategies with the regulatory environment in which their customers operate.
Worldwide Big Data Analytics In Defense and Aerospace Market
Why This Research Matters for 2026 Strategy
The strategic value of a market study is measured by its ability to reduce uncertainty in high-stakes decisions. As organizations enter 2026, several priorities make this analysis particularly timely. First, capital allocation ROI for analytics investments is increasingly scrutinized. Leaders need evidence-based insight into which components, applications, and deployment models are generating measurable mission and operational value, and where the market is still maturing. Second, partnership strategy is being redefined. The convergence of defense primes, enterprise technology platforms, and specialized analytics providers is creating new teaming architectures that can either accelerate or constrain market access. Understanding where each competitor and partner sits within this ecosystem is essential for negotiating positioning, avoiding redundancy, and identifying white space.
Third, procurement cycles and regulatory calendars are aligning in ways that reward early, well-informed positioning. Organizations that understand the interplay between CMMC compliance, data governance frameworks, export control constraints, and emerging AI certification pathways will be better equipped to structure programs that move through approval gates efficiently. Finally, the pace of technological change—especially around agentic AI workflows, sensor fusion, and predictive logistics—means that strategic plans built on outdated market assumptions will quickly lose relevance. This report provides the updated baseline and forward trajectory needed to stress-test assumptions, calibrate roadmaps, and align investment with where demand is actually heading.
Conclusion: From Intelligence to Action
The worldwide market for big data analytics in defense and aerospace has crossed a critical threshold. It is no longer a peripheral technology initiative; it is a core enabler of mission readiness, operational efficiency, and strategic competitiveness. The growth trajectory, competitive dynamics, and regulatory-technical environment documented in this study reveal a market that is expanding rapidly while becoming more structurally complex. For executives, program leaders, and investment decision-makers, the imperative is to move beyond surface-level awareness and develop a precise understanding of where value is being created, how competitors are positioning, and which operational domains offer the strongest return on analytics investment.
The full report delivers the depth, segmentation logic, competitive profiling, and forward forecast required to make those decisions with confidence. It provides the structured intelligence needed to convert market visibility into strategic action, without exposing organizations to the cost of fragmented data or outdated assumptions. For leaders who recognize that the next phase of defense and aerospace advantage will be determined by data, the time to align strategy with market reality is now.
For detailed analysis of this topic, please visit the official page: Worldwide Big Data Analytics In Defense and Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com