

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chatbot Builders Market To Surge 26% CAGR, Hits $42.6B by 2032

Charting the Future of Conversational Intelligence: A Strategic Overview of the Global Chatbot Builders Market (2026–2032)
The enterprise landscape is undergoing a fundamental shift in how organizations interact with customers, employees, and systems. No longer viewed as novelty widgets, conversational AI agents are becoming the central nervous system of digital transformation. As we move through 2026, the decision to invest in a chatbot builder platform is no longer about whether to automate, but about how to architect autonomy, scale, and compliance into every interaction. PW Consulting's latest Worldwide Chatbot Builders Market research provides the definitive intelligence framework needed to navigate this complex, high-growth environment.
This article serves as a strategic preview of our comprehensive study. It outlines the macroeconomic trajectory, the evolving technology landscape, and the competitive dynamics that will define the next seven years. Our aim is to equip C-suite executives, product leaders, and investment strategists with the contextual depth required to make informed decisions. While we share high-level market evolution here, the granular segmentation, precise regional valuations, and detailed competitive benchmarking are reserved for the full report. Those who require actionable precision are invited to access the complete intelligence via our source page.
The Macro Trajectory: Sustained Acceleration Toward 2032
The market for chatbot builders is experiencing a compounding growth curve that reflects the rapid maturation of underlying AI technologies. Drawing on historical data from 2020 through our base year of 2025, the industry has demonstrated consistent expansion driven by the migration from static, rule-based scripts to dynamic, generative models. The inflection point is particularly pronounced as we look toward the forecast period spanning 2026 to 2032.
Our analysis indicates a robust compound annual growth rate of 26.0 percent over the forecast horizon. This velocity is not merely a reflection of technological capability, but of tangible business necessity. Enterprises are under increasing pressure to deliver hyper-personalized, instant resolutions across omnichannel touchpoints, while simultaneously managing operational costs. The revenue trajectory suggests that the market will expand from a substantial 2025 baseline of approximately 8.45 billion USD to a projected scale exceeding 42.6 billion USD by 2032. Such growth underscores the transition of conversational AI from a supportive function to a core revenue and retention engine across multiple verticals.
Importantly, this expansion is multifaceted. While overall market sizing provides a high-level view of opportunity, the distribution of value across technologies, applications, and geographies reveals where competitive advantages are likely to be forged. Our report dissects these dimensions to highlight which segments are capturing disproportionate value and why. However, to maintain the strategic focus of this preview, we refrain from listing specific regional revenue breakdowns or application-level percentages. Those details are critical for nuanced budgeting and market entry strategies, and they are fully elaborated in the complete dataset.
Website Builders Market
Technology Evolution: The Generative AI Paradigm Shift
The archetype of the chatbot builder has been rewritten by the advent of generative AI and advanced natural language processing. In earlier market cycles, value was concentrated in platforms that could reliably map user intents to predefined responses. Today, the value proposition has shifted toward platforms that can generate contextually aware, unbounded responses, orchestrate multi-step workflows, and integrate seamlessly with enterprise knowledge bases.
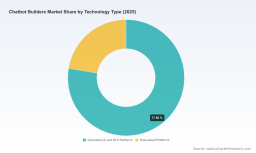
Our segmentation analysis distinguishes between platforms anchored in generative AI and NLP capabilities and those still reliant on rule-based architectures. The data indicates a clear gravitational pull toward generative solutions, which are capturing the majority of market attention and investment. These platforms enable businesses to deploy agents that can reason, adapt, and learn from interactions in real time. Conversely, rule-based platforms continue to serve specific niches where predictability, regulatory compliance, and deterministic outputs are paramount. The coexistence of these two paradigms creates a layered ecosystem where enterprises must decide not only which platform to adopt, but how to blend autonomy with control based on their risk profiles and use-case complexity.
Beyond the technology type, the application layer is equally transformative. Chatbot builders are no longer siloed in customer service; they are permeating marketing and sales automation, human resources, internal operations, and IT service management. The research explores how conversational interfaces are being embedded into CRM workflows, employee onboarding processes, and technical support tickets. Each application domain carries distinct performance metrics, integration requirements, and expectations for seamless human handoff. Detailed breakdowns of these application segments, including their relative contribution to market revenue, are provided in the full report for leaders who need to align platform selection with specific operational priorities.
Competitive Dynamics: Hyperscalers, Specialists, and the Rise of Agentic AI
The competitive landscape of the chatbot builders market is characterized by a diverse array of players, ranging from technology giants with vast cloud ecosystems to agile specialists focused on vertical-specific automation. Our report profiles over a dozen key companies, each bringing distinct strategic advantages to the table.
Among the hyperscalers, the integration of chatbot capabilities into broader cloud and productivity ecosystems remains a dominant strategy. Google offers Dialogflow, a natural language understanding platform that enables developers to build conversational interfaces across web, mobile, and voice channels with extensive multi-language support and enterprise integration options. Microsoft provides the Azure Bot Service alongside Microsoft Copilot Studio, allowing organizations to build and manage intelligent chatbots that are deeply woven into the Microsoft ecosystem and Power Platform. Amazon delivers Amazon Lex, which facilitates the creation of voice and text conversational interfaces with tight coupling to AWS services, ensuring scalability for high-volume applications. IBM rounds out this cohort with watsonx Assistant, which emphasizes agentic AI capabilities for enterprise-scale deployments, supporting complex workflows, mainframe integration, and compliance-oriented environments.
Parallel to these infrastructure-heavy players, a vibrant tier of specialized vendors is pushing the boundaries of what conversational AI can achieve. Infobip provides an AI-first cloud communications platform that connects chatbot experiences across messaging, voice, and digital channels with enterprise-grade security. Yellow.ai delivers an agentic AI platform focused on dynamic, multilingual conversations and omnichannel automation for both customer and employee experiences. Kore.ai offers an enterprise conversational AI platform with strong governance, analytics, and pre-built agents tailored for customer service and productivity. LivePerson brings a focus on high-volume contact centers and conversational commerce through agent assist and messaging infrastructure, while HubSpot integrates chatbot building directly into its CRM, enabling personalized interactions across marketing, sales, and service. Intercom's Fin AI Agent represents a shift toward AI-powered automation for support and engagement, and Zoho's Zobot extends conversational capabilities within its broader business application suite.
Worldwide Chatbot Builders Market
On the development and deployment frontier, platforms like Botpress offer open-source flexibility with visual flow builders and integration options, appealing to developers and enterprises seeking customization. Landbot provides a no-code conversational platform that emphasizes engaging website and messaging experiences through visual design. Ada specializes in autonomous resolution for customer support, particularly in telecom, banking, and e-commerce, while Cognigy delivers an enterprise-grade platform for building voice and text virtual agents with robust NLU, integrations, and analytics for complex business processes.
Recent developments underscore the pace of innovation. In October 2025, IBM introduced an updated version of watsonx Assistant for Z, embedding an agentic AI framework designed to enhance contextual understanding and multi-step workflow automation within enterprise environments. In September 2025, Botsify launched an AI-powered agentic platform for building and deploying intelligent conversational agents. Earlier in February 2025, OpenAI released its Deep Research capability within ChatGPT, enabling autonomous web browsing and the generation of detailed, cited reports, a move that signals the broader potential for LLMs to power sophisticated conversational research agents. Furthermore, in December 2024, Yellow.ai secured 75 million USD in funding to scale generative AI customer-service automation across new geographies. These milestones illustrate a market where product iteration, funding, and strategic capability expansion are tightly interlinked.
Regulatory and Infrastructure Currents Shaping Deployment Decisions
Strategic planning for chatbot builders cannot occur in a vacuum. The infrastructure costs and regulatory pressures surrounding AI workloads are becoming material factors in deployment economics. As of early 2026, data center energy consumption is emerging as a critical consideration for enterprises scaling generative AI chatbots. U.S. data centers' total energy demand is projected to nearly double from approximately 80 GW in 2025 to 150 GW by 2028, significantly impacting the electricity infrastructure that supports AI workloads including conversational agents. This surge aligns with broader global trends, where data center electricity consumption reached roughly 415 TWh in 2024, representing about 1.5 percent of world total electricity use, and growing at a 12 percent CAGR since 2017. AI inference workloads are expected to drive nearly half of the net increases through 2030.
At the policy level, the White House Ratepayer Protection Pledge, signed on March 4, 2026, by major hyperscalers and AI companies, commits signatories to cover the full cost of new electric generation resources for data centers, ensuring that household electricity bills are not burdened by AI infrastructure expansion. Concurrently, twenty-seven U.S. states are advancing legislation that requires data center developers to cover energy infrastructure costs and report usage, with California, Ohio, and Utah enacting specific laws addressing facilities as small as 10 MW. These regulatory dynamics, alongside U.S. data centers' projected share of total electricity consumption rising from about 4.4 percent in 2023 to between 6.7 and 12.0 percent by 2028, create a complex backdrop for chatbot builders that rely on cloud-hosted, compute-intensive models.
For enterprise decision-makers, these factors translate into considerations around vendor selection, total cost of ownership, and sustainability commitments. Platforms that optimize inference efficiency, offer flexible deployment models, or integrate with energy-conscious cloud regions may gain a competitive edge. Our full report examines how such macro-level dynamics intersect with market segmentation and vendor capabilities, but the core takeaway for 2026 strategists is clear: infrastructure and policy are no longer peripheral concerns; they are integral to the viability and scalability of conversational AI investments.
Market Structure and the Strategic Playbook for 2026
The chatbot builders market is not a monolith; it is a competitive arena defined by varying degrees of concentration and rapid technological disruption. Our market concentration analysis reveals that the top three players command a combined share of approximately 32.4 percent, while the top five account for 46.85 percent of the market. This structure indicates a landscape where established giants hold significant sway, yet there remains ample room for specialized players to differentiate through niche capabilities, superior user experience, or industry-specific verticals.
For leaders navigating this environment, the strategic playbook involves several critical moves. First, alignment between technology choice and enterprise architecture is essential. The platform must integrate smoothly with existing CRM, ERP, and knowledge management systems, while supporting the desired level of autonomy. Second, the shift toward agentic AI requires a reevaluation of governance frameworks. Enterprises must define boundaries for agent actions, ensure compliance with data privacy and industry regulations, and establish escalation protocols for complex or sensitive interactions. Third, metrics for success are evolving. Beyond deflection rates and resolution times, organizations are beginning to measure the impact of conversational agents on customer lifetime value, employee productivity, and operational resilience.
Our research provides a granular view of how these strategic dimensions play out across different technology types, application areas, and regional markets. We also explore the implications of recent funding rounds, product launches, and feature releases for competitive positioning. Detailed segmentation splits, including specific revenue contributions by region, technology, and end-user application, are available in the complete report. These data points are vital for sizing opportunities, benchmarking performance, and identifying where the next waves of growth will emerge.
Engage with the Full Intelligence
The Worldwide Chatbot Builders Market research is designed for decision-makers who refuse to rely on surface-level trends. It offers a rigorous synthesis of historical performance, forward-looking projections, competitive profiling, and context-aware analysis of the regulatory and infrastructure forces shaping the industry. The 26.0 percent CAGR to 2032, the dominance of generative AI and NLP platforms, and the expanding footprint of conversational agents across customer service, marketing, HR, and IT operations all point to a market that is both promising and demanding of sophisticated strategy.
To access the complete set of insights, including precise market sizing across all segments, detailed regional and application breakdowns, comprehensive company profiles, and actionable recommendations tailored to your strategic objectives, we invite you to visit the source page for this report. The full intelligence will empower your team to make data-driven choices, anticipate competitive shifts, and capitalize on the rapidly evolving landscape of conversational AI.
For detailed analysis of this topic, please visit the official page: Worldwide Chatbot Builders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com