

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Projects Arthroscope Market to Surpass $8.79 Billion by 2032, Growing at 6.12% CAGR

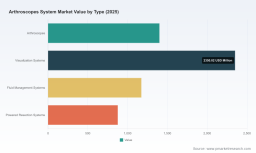
Navigating the Next Wave: Strategic Intelligence for the Worldwide Arthroscopes System Market (2026–2032)
The global landscape for minimally invasive orthopedic surgery is entering a decisive phase. As health systems balance clinical efficiency, cost containment, and technological adoption, arthroscopic systems have moved from a procedural convenience to a strategic purchasing priority. Our latest Worldwide Arthroscopes System Market research distills more than a decade of historical performance and seven years of forward-looking modeling into a single, decision-ready intelligence platform. For executives, commercial leaders, and investment committees operating in 2026, this study is not a static market snapshot—it is a navigational tool for capital allocation, product portfolio prioritization, and competitive positioning.
Built on a rigorous base year of 2025 and extending through 2032, the analysis captures a market that has demonstrated consistent expansion across economic cycles. Total industry revenue has progressed from approximately 4.33 billion USD in 2020 to an estimated 5.80 billion USD in 2025, with the trajectory continuing upward to approach 6.0 billion USD in 2026. Over the full forecast horizon, the market is projected to compound at a 6.12 percent CAGR, reaching nearly 8.8 billion USD by 2032. These figures establish the macro foundation, but the real strategic value lies beneath the headline numbers: in the shifting dynamics of procurement, regulatory pathways, reimbursement architecture, and the evolving battleground among established incumbents and agile innovators.
Why This Research Matters for 2026 Decision-Making
The 2026 operating environment demands more than top-line growth assumptions. Hospital capital expenditure patterns are showing selective recovery, with sampled health networks reporting median equipment budgets around 15 million USD per system. That context directly shapes demand for arthroscopic visualization platforms and capital-intensive instrument portfolios. Procurement committees are no longer evaluating products in isolation; they are weighing total cost of ownership, integration with existing OR ecosystems, single-use conversion economics, and the procedural throughput gains promised by next-generation optics and fluid management technologies.
At the same time, reimbursement frameworks are being refined. Medicare NCCI 2026 coding policy details bundling rules for knee arthroscopic synovectomy, loose body removal, and debridement procedures tied to parent arthroscopy codes. CMS prepayment review and prior authorization considerations for certain knee arthroscopic debridement services remain active in 2026, influencing procedure mix and facility scheduling. In parallel, dedicated 2026 Medicare National Average Payment Rates now provide explicit guidance for physician, hospital outpatient, and ambulatory surgery center settings covering diagnostic and surgical knee, shoulder, and elbow arthroscopy procedures. For manufacturers, distributors, and service providers, these dynamics alter volume forecasts, pricing elasticity, and the value proposition of specific system configurations.
Regulatory oversight continues to anchor product strategy. Arthroscopes remain classified under 21 CFR 888.1100 as Class II devices with product code HRX, and the 2025–2026 510(k) clearance cadence demonstrates an active pipeline of new entrants and iterative upgrades. This regulatory environment rewards companies that can move efficiently through submission, clinical evidence generation, and market access planning, while creating friction for those relying on legacy portfolios without a clear innovation or compliance roadmap.
What the Study Delivers: A Practical Toolkit for Commercial and Operational Leaders
This research is engineered to translate market structure into executable strategy. Rather than offering abstract commentary, the report is organized around operational questions that executives face in 2026 and beyond:
- Market sizing and trajectory modeling across the full forecast period, enabling scenario planning for capacity expansion, R&D investment, and regional entry timing.
- Segment-level architectural analysis covering device typologies, procedural applications, and geographic demand patterns, with an emphasis on relative positioning rather than static share tables.
- Competitive profiling of the principal players shaping product standards, pricing norms, and channel dynamics, including capabilities, system-level offerings, and recent strategic moves.
- Regulatory and reimbursement mapping that connects FDA classification, 510(k) clearance activity, Medicare payment guidance, and NCCI bundling rules to commercial implications.
- Capital equipment and procurement trend insights drawn from health system spending behavior, supporting realistic assumptions about replacement cycles, upgrade paths, and single-use conversion economics.
- Strategic scenario frameworks for evaluating disruption from cordless visualization, single-use arthroscopes, advanced fluid management, and powered resection platforms.
The objective is to give leadership teams a common operating picture. When the board asks where to allocate growth capital, when product management debates which visualization platform to prioritize, or when market access teams prepare for payer negotiations, this study provides the connective tissue between macro trends and tactical execution.
Competitive Landscape: Incumbents, Specialists, and Emerging Entrants
The arthroscopy market remains structurally concentrated, with the top three participants collectively accounting for more than half of industry revenue and the top five approaching three-quarters. That concentration reflects the advantages of integrated system portfolios, established surgeon relationships, global service networks, and the economic moats created by visualization platforms that anchor procedural workflows. Yet concentration also masks a dynamic undercurrent: targeted innovation, regulatory clearances, and niche differentiation are reshaping competitive pressure points.
Stryker Corporation continues to offer a comprehensive arthroscopic ecosystem spanning visualization systems, resection tools, fluid management, and integrated sports medicine solutions for knee, shoulder, hip, and small joint procedures. Smith & Nephew plc maintains a broad footprint across major joint applications with advanced arthroscopes, visualization platforms, RF probes, shaver blades, and full arthroscopy systems. Arthrex, Inc. has sharpened its specialization through the NanoScope operative arthroscopy system, 1–2 mm chip-on-tip arthroscopes, hand instruments, fluid management, and a comprehensive sports medicine portfolio, supported by updated 2026 coding and reimbursement guidance. KARL STORZ SE & Co. KG reinforces optical excellence with rigid and flexible arthroscopes, HOPKINS optics, ENDOCAMELEON variable view endoscopes, and full instrumentation sets. CONMED Corporation delivers visualization systems, shavers, fluid management, RF ablation devices, and complete instrument portfolios, while Johnson & Johnson, through DePuy Synthes, supplies Mitek arthroscopes, visualization equipment, resection tools, and integrated systems for orthopedic arthroscopic procedures. Olympus Corporation contributes high-definition arthroscopes, visualization systems, and endoscopic instrumentation tailored to arthroscopic surgery, and Richard Wolf GmbH provides precision arthroscopes, fluid control systems, and specialized instrumentation for orthopedic and sports medicine applications. Zimmer Biomet extends its sports medicine and orthopedic portfolio with arthroscopic instruments, visualization solutions, and supporting technologies, and Medtronic plc contributes arthroscopy-related devices and visualization components through its surgical technologies offerings.
What makes the current landscape especially consequential for 2026 is the emergence of single-use and cordless architectures alongside established reusable platforms. Medimaging Integrated Solution Inc. (MiiS) recently received FDA 510(k) clearance for its Horus single-use arthroscope and associated endoscope display system, building on its development focus in single-use endoscopy and display integration. Integrated Endoscopy continues to pioneer single-use 4K cordless wireless arthroscope systems designed to improve efficiency and first-time quality in arthroscopic procedures. These innovations are not merely product variations; they challenge traditional reprocessing economics, OR turnover assumptions, and infection control narratives. For incumbents, the strategic question is whether to absorb, partner, or differentiate around disposable and wireless form factors. For newer entrants, the opportunity lies in demonstrating measurable workflow gains, total cost advantages, and clinical consistency that justify conversion in procurement environments where capital budgets are selective rather than expansive.
Recent regulatory activity reinforces the pace of change. FDA 510(k) clearances in late 2025 and early 2026 spanned single-use arthroscope platforms, arthroscope-related device submissions, an arthroscopic bur classification under arthroscope regulations, and an electrosurgical device used in arthroscopic procedures. Combined with Arthrex’s updated hand instrument catalog and 2026 coding guidelines, these developments indicate an active pipeline in which device classification, procedural coding, and product iteration remain tightly interlocked. Companies that can align product roadmaps with reimbursement clarity and regulatory efficiency will be better positioned to convert innovation into share gains.
Market Dynamics: The Forces Shaping Demand, Pricing, and Access
Demand for arthroscopic systems is being pulled by several converging forces. Minimally invasive procedures continue to be favored for their potential to reduce recovery time, limit soft tissue disruption, and support ambulatory settings. Visualization quality, fluid management precision, and resection efficiency increasingly define procedural success and OR throughput, making system-level performance a procurement priority rather than a line-item commodity. At the same time, health systems are scrutinizing capital outlays more closely, which elevates the importance of demonstrable clinical value, service reliability, and lifecycle cost.
Worldwide Arthroscopes System Market
Reimbursement architecture is a second critical driver. The 2026 Medicare National Average Payment Rates provide explicit guidance for arthroscopic procedures across physician, hospital outpatient, and ASC settings, helping stabilize planning assumptions for diagnostic and surgical knee, shoulder, and elbow arthroscopy. However, CMS NCCI bundling rules for synovectomy, loose body removal, and debridement procedures tied to parent arthroscopy codes require careful procedural coding and documentation. In parallel, certain knee arthroscopic debridement services remain subject to prepayment review and prior authorization considerations, which can influence case scheduling, facility selection, and the relative attractiveness of ambulatory versus inpatient pathways. For manufacturers, these reimbursement nuances affect the value proposition of system configurations that support efficiency, documentation, and coding accuracy.
Regulatory continuity provides both predictability and pressure. Arthroscopes remain Class II devices under 21 CFR 888.1100 with product code HRX, and the recurring 510(k) clearances across 2025 and 2026 confirm an active innovation cycle. This environment rewards companies that maintain disciplined quality systems, evidence packages, and submission readiness. It also creates a barrier for organizations that rely on incremental updates without clear differentiation or regulatory strategy. The implication for 2026 is clear: regulatory and reimbursement alignment should be treated as a commercial capability, not a compliance afterthought.
Capital spending behavior adds another layer of realism. Hospital equipment budgets are recovering selectively, with median system-level spending around 15 million USD in sampled networks. That pattern supports continued investment in visualization and capital equipment, but it also means purchase decisions are increasingly comparative, evidence-driven, and sensitive to total cost of ownership. Single-use options may gain traction where they reduce reprocessing burden, lower infection control risk, and simplify turnover, while reusable platforms remain compelling where durability, optics, and integrated system economics deliver long-term value. Understanding where each model wins is essential for both suppliers and buyers.
Strategic Implications for 2026 and Beyond
The Worldwide Arthroscopes System Market is not simply expanding; it is reconfiguring around workflow efficiency, procedural precision, and access economics. For executives, the strategic priorities that emerge from this research can be summarized as follows:
- Portfolio alignment with procedure mix and setting trends. As ambulatory surgery and outpatient pathways continue to gain importance, system configurations that support efficiency, mobility, and reimbursement clarity will be increasingly valued. Companies should map product capabilities to the procedural applications and care settings where demand is most resilient.
- Total cost of ownership as a competitive differentiator. Procurement committees are weighing capital, service, reprocessing, and turnover costs together. Articulating a credible TCO narrative—supported by utilization data, service economics, and workflow gains—can shift evaluation outcomes even in concentrated markets.
- Innovation sequencing around visualization, fluid management, and powered resection. These segments anchor procedural performance and system lock-in. Strategic investments should prioritize the capabilities that most directly influence surgeon preference, OR efficiency, and clinical consistency.
- Regulatory and reimbursement readiness as a growth lever. With ongoing 510(k) activity and evolving Medicare coding policy, companies that integrate regulatory planning, evidence generation, and reimbursement strategy into product development will move faster and with less friction.
- Positioning against single-use and cordless disruption. Disposable and wireless architectures are reshaping procurement logic. Incumbents must decide where to defend, where to adapt, and where to collaborate, while new entrants must prove durable clinical and economic advantages beyond initial novelty.
Concentration remains high, but high concentration does not mean static competition. Share movement will likely occur through system-level differentiation, service quality, procurement economics, and the ability to match product innovation with reimbursement and regulatory realities. The companies that treat these elements as an integrated strategy—not as separate functions—will be best placed to convert market growth into durable advantage.
What to Expect Inside the Full Report
This article is an introduction to the strategic narrative; the complete Worldwide Arthroscopes System Market study provides the supporting architecture. Inside, readers will find detailed market sizing and forecast modeling, segment-level analysis across device types, applications, and regions, and a comprehensive competitive review that maps capabilities, positioning, and recent developments for the principal participants. The report integrates regulatory and reimbursement context, capital expenditure trends, and scenario-based guidance to help leadership teams evaluate entry timing, portfolio priorities, pricing strategy, and partnership opportunities.
Handheld Arthroscopic Instrument Market
To protect the analytical rigor of the study, certain granular breakdowns are reserved for the full deliverable. This is intentional. The precision that matters for board-level decisions—relative segment momentum, regional demand patterns, and application-specific dynamics—is most useful when evaluated alongside the complete methodology, competitive benchmarks, and scenario frameworks presented in the report.
Closing Perspective
The worldwide arthroscopes system market is poised for steady, structurally supported growth through 2032, but the winners of the next cycle will be determined by more than macro tailwinds. They will be defined by how effectively organizations align product strategy with procurement economics, reimbursement clarity, regulatory efficiency, and the evolving expectations of surgeons and health systems. For decision-makers operating in 2026, the Window for proactive positioning is open now. The full study provides the depth, structure, and strategic context needed to turn that opportunity into informed action.
For detailed analysis of this topic, please visit the official page: Worldwide Arthroscopes System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com