

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting 2025 Optical Composite Film Market Hits $4.12B with 6.4% CAGR Through 2032

Strategic Intelligence Unveiled: The 2026 Outlook for the Worldwide Optical Composite Film Market
The global display industry stands at a critical inflection point. As consumer electronics manufacturers strive for thinner profiles, higher brightness, and improved energy efficiency, the underlying optical components have become just as strategic as the display panels themselves. For executives navigating the landscape in 2026, understanding the trajectory of optical composite films is no longer optional; it is a prerequisite for informed capital allocation and product roadmap planning. PW Consulting is pleased to introduce our latest comprehensive market research study, designed to provide the depth of analysis required to thrive in this evolving sector.
The Macro Trajectory: Growth Amidst Complexity
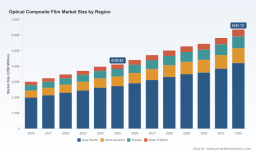
Our analysis covers a robust historical window from 2020 through 2025, extending into a detailed forecast period through 2032. This longitudinal view allows stakeholders to contextualize recent volatility against long-term secular trends. The data indicates a consistent upward trajectory for the worldwide optical composite film market. Valued at approximately 3.0 billion USD in 2020, the market has demonstrated steady resilience and expansion, reaching an estimated 4.1 billion USD by 2025.
This growth story is expected to accelerate, with the market projected to surpass 5.4 billion USD by 2030 and approach 6.4 billion USD by the end of the forecast period in 2032. Driving this expansion is a compound annual growth rate (CAGR) estimated at 6.4 percent over the forecast horizon. Such sustained growth underscores the increasing integration of advanced optical structures in next-generation devices. However, growth rates alone do not tell the whole story. The strategic value of this research lies in understanding the underlying drivers, constraints, and competitive forces that will shape this expansion.
Technological Foundations and Raw Material Dynamics
Optical composite films are engineered by combining two to three optical films using sophisticated structural design and composite resins. These materials are typically based on polymers such as PET, TAC, or polycarbonate, each offering distinct optical properties concerning brightness enhancement, diffusion, and polarization. The production process is material-intensive. Key upstream feedstocks, including purified terephthalic acid (PTA) and monoethylene glycol (MEG) for polyester-based films, along with polypropylene resin for related processes, represent a significant portion of production costs. In similar composite film segments, these raw materials can account for 60 to 70 percent of total production costs.
This cost structure makes the industry highly sensitive to petrochemical pricing fluctuations and supply chain stability. Our research delves into how manufacturers are mitigating these risks through vertical integration and strategic sourcing. Furthermore, regulatory pressures are mounting. Stricter environmental regulations concerning chemical usage and manufacturing emissions are increasing production costs globally. New EU regulations scheduled for 2025 have specifically restricted several key materials in reflective and brightness enhancement films, forcing suppliers to innovate compliance strategies without compromising optical performance. Our report analyzes the impact of these regulatory shifts on margin structures and regional manufacturing footprints.
Segmentation and Demand Drivers
Understanding where demand originates is vital for targeted market entry or expansion. The market is segmented by type, reflecting the diverse functional requirements of modern display systems. Product categories include Brightness Enhancement Composite Film, Dual Brightness Enhancement Composite Film, and Diffuser-Prism Composite Film. Each segment serves specific roles in enhancing contrast, uniformity, and viewing angles across different display technologies.
On the demand side, the application landscape is dominated by consumer electronics, though diversification is evident. Television sets continue to represent a significant portion of consumption, driven by the shift toward larger screens and higher resolution standards. Mobile devices, including smartphones and tablets, remain a critical application vertical, where space constraints demand highly efficient optical stacking. Monitors and laptops constitute another major pillar of demand, supporting the hybrid work era's hardware requirements. Additionally, the automotive sector is emerging as a key growth driver, with Optical Displays in vehicles requiring robust, high-brightness solutions for safer visibility in various lighting conditions.
While global averages provide a top-line view, regional nuances are critical. Asia Pacific remains the dominant production and consumption hub, reflecting the concentration of display manufacturing infrastructure in the region. North America, Europe, and the Rest of World follow, each presenting unique regulatory and demand characteristics. Our full report breaks down these regional intensities without disclosing the specific percentage splits in this preview, ensuring that clients access the granular data through our complete intelligence platform.
Competitive Landscape: Consolidation and Innovation
The optical composite film industry is characterized by moderate concentration, with the top three players holding a significant share of the global revenue. The top five manufacturers collectively command an even larger portion of the market, indicating high barriers to entry and the importance of established supply relationships with major display OEMs.
Key industry participants include global technology giants and specialized material science firms. Companies such as 3M Company in the USA, renowned for their extensive optical systems portfolio, remain pivotal. In Asia, major chemical and materials corporations dominate the supply chain. LG Chem and Kolon Industries from South Korea, alongside Samsung SDI, are integral to the regional supply network. Japanese firms such as Nitto Denko Corporation, Toray Industries, Sumitomo Chemical, Zeon Corporation, Mitsubishi Chemical Corporation, and Teijin Limited contribute critical materials ranging from polarizing films to polycarbonate optical films like PURE-ACE®.
China remains a focal point for manufacturing capacity, exemplified by entities like Nanjing Bready Advanced Materials Technology (Group) Co., Ltd., which specializes in functional polymer film materials including quantum dot enhanced films and Mini LED/LCD optical films. Similarly, Hyosung Chemical provides advanced materials supporting composite film assemblies. The competitive dynamic is not static; it is driven by capacity expansions and product launches.
Recent industry developments highlight this active landscape. In May 2025, Mitsubishi Chemical Group Corporation announced a capacity increase for their Optical Film for Polarizers, known as OPL FILM, in Japan, signaling continued investment in electronics materials. More recently, in March 2026, I.S.T introduced a new class of polyimide composites at JEC World 2026, unlocking new design freedom for high-performance structures with potential optical applications. These moves illustrate the race to secure technological advantage and production scale. Our report provides detailed profiles on these key companies, analyzing their strategic positioning, recent operational shifts, and potential threats to incumbents.
Report Scope and Operational Utility
This Worldwide Optical Composite Film Market research is designed as a decision-support tool for strategy directors, procurement heads, and investors. The full document goes beyond high-level estimates to provide actionable intelligence. The scope includes a detailed examination of market size trends, utilizing a base year of 2025 to anchor current valuations before projecting forward to 2032.
Inside the report, clients will find comprehensive segmentation data that dissects the market by region, type, and application, allowing for precise TAM SAM SOM analysis tailored to specific business units. We evaluate the supply chain in depth, covering raw material dependencies and logistics considerations. The competitive landscape section offers more than just a list of players; it provides a comparative analysis of market share, strategic focus, and regional strength.
Furthermore, the study addresses critical market dynamics that influence profitability. This includes an assessment of the regulatory environment, particularly regarding environmental compliance and material restrictions. We also address common operational questions, such as reimbursement policies or recalls, confirming the current absence of specific recalls in the display and industrial applications sector as of 2026, which stabilizes risk assessments for investors.
Optical Films Market
Strategic Implications for 2026 and Beyond
For organizations planning their 2026 roadmap, this research offers several strategic takeaways. First, the growth rate suggests that demand will outpace general manufacturing output in certain high-specification segments, creating opportunities for suppliers who can guarantee quality and consistency. Second, the concentration of market share among top players suggests that partnership or acquisition strategies may be more viable than greenfield entry for newcomers. Third, the regulatory landscape requires proactive compliance planning, particularly for suppliers targeting the European market where restrictions on materials in brightness enhancement films are tightening.
The automotive display segment, while currently smaller in total value compared to consumer electronics, represents a high-growth area where optical performance directly correlates with safety and brand premium. Suppliers capable of meeting automotive-grade reliability standards for composite optical films may find favorable margin opportunities. Similarly, the evolution of AR/VR and Mini LED technologies, as pursued by companies like Nanjing Bready, points toward future diversification beyond traditional LCD and OLED panels.
Worldwide Optical Composite Film Market
Accessing the Full Intelligence
While this overview establishes the market's direction and key players, the precise numerical breakdowns, specific share percentages, and detailed regional valuations are reserved for our full subscription clients. The complexity of the optical composite film market requires a granular dataset to validate assumptions regarding capacity utilization, pricing power, and regional competitiveness.
PW Consulting's Worldwide Optical Composite Film Market report provides the comprehensive data structure needed to validate these strategic hypotheses. By securing access to the full study, organizations can move from general awareness to precise planning, aligning their investments with the verified growth pockets of the industry. The convergence of material science innovation, regulatory pressure, and demand growth creates a complex environment where high-quality intelligence is the ultimate competitive advantage.
We invite industry leaders to leverage this research to refine their market entry strategies, optimize supply chain negotiations, and anticipate shifts in the competitive hierarchy. The data covered herein, ranging from historical baselines to future forecasts, ensures that your decision-making is grounded in verified market reality rather than speculation. The optical composite film market is poised for significant evolution, and those equipped with the deepest insights will be best positioned to capture the value generated over the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Worldwide Optical Composite Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com