

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Thermal Printer Market to Hit $9.19B by 2032, 5.5% CAGR

Strategic Intelligence in a Dynamic Landscape: Inside the Worldwide Thermal Printer Market Report
The global thermal printing industry stands at a critical inflection point. As enterprises navigate shifting supply chain dynamics, evolving regulatory frameworks, and accelerating digital transformation across retail, logistics, and healthcare sectors, the demand for precise, actionable market intelligence has never been more urgent. PW Consulting is pleased to introduce our comprehensive Worldwide Thermal Printer Market study, a definitive analytical resource designed to equip leadership teams, investment committees, and product strategists with the multidimensional insights required to make informed decisions throughout the 2026–2032 forecast horizon.
This report is not a passive compilation of historical figures. It is a forward-looking strategic instrument, built on rigorous primary research, cross-validated secondary datasets, and deep sector expertise. By synthesizing macroeconomic trajectories with granular technology and application analysis, the study provides a complete operating picture of where the thermal printer market has been, where it is headed, and—most importantly—how organizations can position themselves to capture value in an increasingly competitive and regulated environment.
Worldwide Thermal Printer Market
The Macro Trajectory: Growth Patterns and Structural Momentum
The worldwide thermal printer market has demonstrated consistent expansion over the past half-decade, reflecting the technology's entrenched role in automated identification, transaction processing, and industrial labeling. Our analysis tracks revenue performance from 2020 through the base year of 2025, with a detailed forward projection extending to 2032. The data reveals a market that has matured beyond early-cycle volatility and now exhibits steady, compounding growth characteristics, supported by durable demand across both developed and emerging economies.
The compound annual growth rate projected across the forecast period underscores a moderately paced but structurally sound expansion trajectory. This growth is not uniform; it is shaped by distinct regional economic conditions, divergent technology adoption curves, and application-specific purchasing behaviors. The report deconstructs these layers systematically, enabling stakeholders to understand not just the headline numbers, but the underlying drivers that will determine market performance in each phase of the outlook.
Readers will find a complete historical reconstruction alongside forward-looking scenario modeling, allowing for sensitivity analysis under varying macroeconomic and regulatory assumptions. The study deliberately avoids over-reliance on single-point estimates, instead presenting a range of plausible outcomes grounded in observable industry momentum, channel feedback, and procurement trend data collected throughout the research cycle.
Technology, Application, and Regional Dimensions: A Segmented Perspective
Thermal printing technology bifurcates into two principal modalities, each serving distinct operational requirements and end-user priorities. Direct thermal solutions continue to command significant share, favored for their simplicity, lower total cost of ownership, and suitability for high-volume receipt, ticketing, and short-life labeling applications. Thermal transfer technology maintains a strong and stable position in environments demanding durability, chemical resistance, and long-term label legibility—characteristics that are indispensable across manufacturing, asset tracking, and regulated logistics workflows.
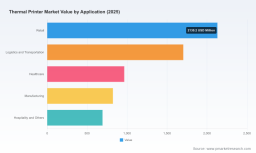
The application landscape mirrors this technological diversity. Retail and point-of-sale ecosystems remain a foundational demand pillar, propelled by continued migration toward electronic point-of-sale architectures, mobile transaction devices, and self-service kiosk deployments. Logistics and transportation represent another major consumption channel, as warehouse automation, parcel sorting, and supply chain visibility initiatives drive sustained procurement of industrial-grade label printers. Healthcare applications contribute a specialized but growing segment, where compliance, traceability, and patient safety considerations shape purchasing criteria. Manufacturing and industrial operations, alongside hospitality and ancillary use cases, round out a diversified demand base that insulates the broader market from sector-specific downturns.
Regionally, the market exhibits a multi-polar structure. Asia Pacific accounts for the largest revenue contribution, reflecting dense manufacturing activity, expanding retail infrastructure, and rapid digitization across multiple economies. North America and Europe together form a mature, regulation-influenced demand environment where procurement decisions are increasingly shaped by compliance requirements, sustainability mandates, and total-cost considerations. Latin America and the Middle East and Africa represent developing but strategically important territories, where infrastructure investment and logistics modernization are gradually accelerating adoption. Our report maps these regional dynamics with careful attention to local pricing structures, channel configurations, and competitive intensity, without reducing complexity to oversimplified rankings.
Regulatory Pressures, Supply Conditions, and Trade Realities
No contemporary market analysis is complete without a candid assessment of the external forces reshaping procurement economics and product design. The thermal paper supply chain has been meaningfully influenced by regulatory interventions targeting chemical composition. The European Union's restriction of bisphenol A in thermal paper to concentrations below 0.02% by weight, effective since 2020, has catalyzed a broad industry transition toward alternative formulations. This shift has not been merely a compliance exercise; it has altered paper sourcing strategies, influenced supplier qualification processes, and introduced new considerations around print head compatibility and media performance.
Parallel regulatory activity in the United States, including California Proposition 65 and related state-level measures, has reinforced the need for distributors and end users to maintain rigorous documentation and formulation transparency. These requirements are particularly salient for organizations operating across multiple jurisdictions, where inconsistent standards can create compliance overhead and procurement friction.
On the supply side, thermal paper and liner material availability has generally remained balanced, though longer lead times have been observed for specialty paper-based label materials amid ongoing phenol-free reformulation efforts. Semiconductor constraints and component availability issues have periodically extended lead times for thermal print head controllers and processing units, affecting manufacturing schedules and, at times, final product pricing. The report evaluates these supply chain dynamics with an emphasis on practical implications: how lead time variability affects inventory planning, how component dependencies influence vendor selection, and how material substitution trends may alter total cost of ownership calculations over the forecast period.
Trade policy developments have also introduced incremental cost pressure. U.S. import tariffs on goods originating from China, including electronic components and finished printer units, have increased landed costs by a measurable margin in affected jurisdictions. The study examines how these tariff structures influence sourcing strategies, regional distribution planning, and the competitive positioning of manufacturers with diversified production footprints.
Competitive Architecture: Incumbents, Specialists, and Strategic Positioning
The worldwide thermal printer market is characterized by a moderately concentrated competitive landscape, where a core group of established players commands a substantial share of revenue while a broader field of regional specialists, technology-focused manufacturers, and application-dedicated providers compete on specificity, pricing, and service responsiveness. The report provides detailed profiles of the principal companies shaping this environment, analyzing their product portfolios, geographic reach, technology emphasis, and recent strategic moves.
Zebra Technologies Corporation remains a defining force in enterprise thermal printing, with a comprehensive portfolio spanning direct thermal and thermal transfer barcode label printers, mobile devices, and industrial systems tailored for logistics, retail, healthcare, and manufacturing environments. Its market presence reflects a sustained emphasis on integration, durability, and software-adjacent value creation. SATO Holdings Corporation operates as a specialized leader in auto-identification and smart printing, delivering industrial thermal label printers with advanced feature sets designed for supply chain, food and beverage, and healthcare applications.
In the receipt and POS segment, Seiko Epson Corporation is a major provider of thermal receipt printers and point-of-sale solutions, emphasizing high-speed, reliable output and compatibility with evolving paper standards. Brother Industries contributes durable thermal printing options across office, industrial, and labeling use cases, valued for consistency across print widths and integration with business systems. Honeywell International rounds out the enterprise and industrial dimension with rugged thermal printers and barcode solutions suited to warehouse, manufacturing, and asset tracking operations.
A strong cohort of regional and application-focused manufacturers adds further depth to the market. BIXOLON Co., Ltd. has emphasized compact, reliable models for mobile, label, POS, and kiosk environments, with recent product activity reinforcing its presence in retail and lottery-oriented settings. Star Micronics and Citizen Systems Japan continue to serve hospitality and retail through compact, high-performance receipt and label printers. TSC Auto ID Technology provides cost-effective desktop, industrial, and mobile thermal barcode printers for labeling and supply chain workflows. Fujitsu Frontech and Toshiba TEC integrate thermal printing into retail and kiosk systems, with particular attention to high-volume transaction environments. Printronix Auto ID targets high-duty manufacturing and distribution with industrial line matrix and thermal transfer offerings, while Microcom Corporation has strengthened its footprint in kiosk and ticketing applications. Xiamen Apt Electronic Tech rounds out the field as a leading supplier of compact thermal printers for POS and mobile environments.
The report does not merely catalog these players. It evaluates their strategic posture, recent product launches, regional expansion patterns, and the operational implications of their portfolio choices. Recent industry activity illustrates this dynamism clearly. BIXOLON advanced its portfolio in early 2026 with new thermal printer and kiosk label models for retail, hospitality, and enterprise use, followed by a specialized lottery ticket printer with regional availability from April 2026. SATO introduced next-generation industrial label printers in Japan and selected markets in early 2026, signaling continued investment in high-performance labeling capacity. Microcom launched a high-duty thermal printer for kiosk, ticketing, and amusement applications, with full production commencing in early 2026. Seiko Epson expanded its receipt printer lineup with a PC-POS and mPOS-oriented model emphasizing accelerated print speed for retail and hospitality environments. These developments are analyzed not in isolation, but as indicators of broader competitive direction, technology prioritization, and end-user demand signaling.
What the Report Delivers: Operational Content for Decision-Makers
This study is structured to serve as a working reference rather than a one-time read. It combines executive-level synthesis with the depth required for functional planning across sales, procurement, product management, and investment analysis. The content is organized to support multiple decision contexts simultaneously, ensuring that readers can extract both strategic direction and tactical detail from a single source.
Key analytical components include a complete market sizing and forecast framework covering historical performance and forward projections, detailed technology segmentation with comparative assessments of direct thermal and thermal transfer demand drivers, and application-level analysis tracing procurement behavior across retail, logistics and transportation, healthcare, manufacturing, and hospitality and other end-use environments. Regional analysis provides a structured view of market size, growth momentum, channel characteristics, and regulatory influence across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
Competitive analysis sections deliver company profiling, portfolio mapping, and strategic positioning assessment, enabling readers to understand not only who the major participants are, but how their product emphasis and geographic focus shape market dynamics. The report also incorporates regulatory and supply chain evaluation, translating policy developments, material availability conditions, and trade policy effects into practical implications for sourcing, compliance, and cost planning. Recent product launches and corporate developments are integrated into the analysis to illustrate near-term market movement and signal likely areas of intensified competition.
Throughout, the study emphasizes operational relevance: how market structure affects channel strategy, how technology adoption curves influence replacement cycles, how regulatory shifts alter media procurement, and how regional cost differentials shape distribution and localization decisions. The goal is to provide a document that can be referenced repeatedly as internal scenarios are stress-tested and strategic options are weighed.
Thermal Paper Market
Translating Intelligence into Action for 2026 and Beyond
The strategic value of this report lies in its ability to connect market structure with decision architecture. For technology and product leaders, it offers a basis for portfolio planning, feature prioritization, and positioning choices in response to evolving application requirements and compliance-driven media changes. For commercial and channel teams, it provides a structured view of regional demand variation, competitive intensity, and the procurement factors that influence buying behavior across segments. For procurement and operations stakeholders, it frames the supply chain and regulatory context that shapes total cost of ownership, lead time expectations, and vendor qualification criteria. For investors and corporate development teams, it delivers a disciplined view of market scale, growth trajectory, concentration dynamics, and the competitive moves likely to define the next phase of industry evolution.
The thermal printer market is not defined by any single driver. It is shaped by the interaction of technology maturity, application diversification, regulatory direction, supply conditions, and competitive strategy. Understanding that interaction requires more than headline figures; it requires a structured, evidence-based interpretation of how these forces compound over time. That is the purpose of this study.
The complete analysis, with full segmentation detail, regional breakdowns, company assessments, and forward-looking scenario content, is available through our dedicated report page. We invite strategy, finance, product, and operations leaders to explore the full study and use its framework to strengthen planning, sharpen competitive positioning, and make more confident decisions across the 2026–2032 outlook.
For detailed analysis of this topic, please visit the official page: Worldwide Thermal Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com