

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Agricultural Surfactants Market to Reach $7.1B by 2032 at 6.12% CAGR

Navigating the Global Agricultural Surfactants Market: Strategic Imperatives for 2026 and Beyond
The agricultural surfactants market stands at a critical inflection point in 2026. As crop protection formulations evolve to meet tightening environmental standards and rising input costs, surfactants have transitioned from auxiliary additives to essential performance enhancers. Our latest Worldwide Agricultural Surfactants Market research provides a comprehensive, data-driven blueprint for executives navigating this complex landscape. This article previews the strategic insights embedded in the full report, illustrating why deep market intelligence is indispensable for decision-making in the current cycle.
The Macro Trajectory: Sustained Expansion Through 2032
The global agricultural surfactants market has demonstrated consistent upward momentum over the past five years. Revenue reached approximately 4,690 million USD in 2025, building on a trajectory that began near 3,488 million USD in 2020. Looking ahead, the forecast period from 2026 through 2032 projects continued growth, with the market expected to climb toward 7,108 million USD by the end of the decade. This expansion is underpinned by a compound annual growth rate of 6.12 percent, reflecting steady demand from crop protection manufacturers, formulators, and agricultural distributors worldwide.
Several structural drivers explain this resilience. Global food security pressures continue to push agrochemical innovation forward, while precision farming techniques demand more reliable adjuvant systems. Simultaneously, regulatory frameworks are reshaping formulation standards, compelling manufacturers to rethink ingredient selection. The market's steady compound growth signals that surfactants are no longer a commodity afterthought but a strategic input category with significant margin potential for companies that can align product portfolios with emerging compliance and performance requirements.
Segmentation Dynamics: Where Growth Converges
Within this expanding market, performance and sustainability considerations are reshaping how value is distributed across product categories, regions, and end-use applications. The research dissected the market across multiple dimensions, revealing clear patterns that executives must monitor.
Non-ionic surfactants currently represent the largest product segment, driven by their widespread use in herbicide formulations and compatibility with diverse active ingredients. Anionic surfactants maintain a strong secondary position, particularly in applications requiring enhanced wetting and soil penetration. Cationic and amphoteric variants occupy more specialized niches, often selected for their unique interfacial properties in targeted crop protection scenarios. The balance among these types is not static; formulation engineers are increasingly blending surfactant classes to achieve specific spray characteristics, tank-mix stability, and environmental profiles.
Geographically, the market reflects divergent maturity levels and growth appetites. North America and Asia Pacific hold substantial revenue shares, supported by large-scale crop production and expanding agrochemical adoption. Europe maintains a sophisticated demand profile shaped by stringent environmental directives, while Latin America and the Middle East and Africa present emerging opportunities that require localized formulation strategies and supply chain agility. The full report maps these regional nuances with granular revenue breakdowns, but the headline takeaway is clear: geographic diversification strategies must account for both regulatory divergence and feedstock availability.
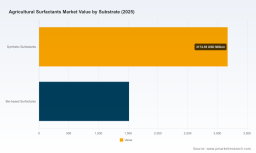
Application-wise, herbicide formulations continue to drive the highest surfactant consumption, followed by fungicides and insecticides. Additional crop protection chemicals round out the demand base, with each application category imposing distinct performance criteria on surfactant selection. Substrate composition further complicates the picture. Synthetic surfactants still command the majority of market revenue, yet bio-based alternatives are gaining traction as formulators respond to sustainability mandates and consumer-facing crop certification requirements.
Regulatory Pressures and Raw Material Volatility: The Dual Challenge
No analysis of this market would be complete without addressing the twin forces of regulatory tightening and input cost instability. Across major agricultural jurisdictions, environmental agencies are scrutinizing traditional agrochemical applications, including the contribution of surfactants to soil and water pollution. This regulatory momentum is accelerating demand for biodegradable and low-toxicity alternatives, pushing manufacturers to reformulate products that meet emerging compliance benchmarks such as EU Ecolabel criteria for agricultural adjuvant formulations.
At the same time, raw material economics are introducing significant cost volatility. Fermentation-derived fatty alcohols used in bio-based surfactant production can raise input costs by up to 40 percent compared with petroleum-based feedstocks. Palm oil prices surged by 22 percent in early 2025 after Indonesia tightened export policies, directly inflating non-ionic surfactant input costs for formulators reliant on fatty alcohol derivatives. These supply-side pressures are forcing companies to evaluate sourcing strategies, hedge commodity exposure, and invest in alternative feedstock pathways.
Government interventions are also reshaping regional demand. In Asia-Pacific markets, crop production subsidies and policy initiatives aimed at modernizing agrochemical standards are supporting increased surfactant adoption. India's push for new global-standard agrochemical molecules, for instance, creates downstream demand for advanced adjuvant systems that can enhance the efficacy of newly registered active ingredients. Understanding how policy cycles intersect with formulation pipelines is essential for forecasting regional revenue trajectories.
Corporate Strategy in a Consolidating Landscape
The competitive environment is defined by a mix of large multinational chemical producers, specialty ingredient manufacturers, and regional agribusiness distributors. Together, these players are investing in product innovation, sustainability credentials, and strategic partnerships to secure positioning in a market where concentration is gradually increasing. The top three firms account for approximately 38.45 percent of total revenue, while the top five capture around 54.12 percent, indicating a moderately consolidated landscape with room for specialized challengers.
BASF SE continues to expand its portfolio of agricultural surfactants and adjuvants, recently emphasizing biodegradable and bio-based options that support crop protection formulations, herbicide tank-mix compatibility, and environmental compliance. The company's 2025 launch of Sokalan CP 301, a plant-based biodegradable dispersant meeting EU Ecolabel criteria for biological fungicide tank-mix applications, illustrates how sustainability targets are being translated into commercial products.
Corteva Agriscience integrates surfactants and adjuvants directly with its crop protection solutions, focusing on enhanced efficacy across herbicides and insecticides while aligning with precision agriculture workflows. This integrated approach allows the company to offer formulation-ready adjuvant systems that simplify procurement for growers and distributors.
Evonik Industries AG specializes in specialty surfactants and sustainable adjuvants, with its BREAK-THRU series delivering improved wetting, spreading, and regulatory compliance. The company's positioning reflects a broader industry shift toward engineered additives that optimize spray coverage while minimizing environmental footprint.
Solvay SA supplies high-performance surfactants for agrochemical formulations, emphasizing bio-based and nano-emulsion technologies that improve active ingredient delivery and stability. Clariant AG develops agricultural surfactant lines such as Synergen products tailored for soil-applied herbicides, low-temperature spray conditions, and precision farming scenarios. Both firms highlight how formulation science is becoming more application-specific and climate-aware.
Worldwide Agricultural Surfactants Market
Croda International Plc focuses on sustainable, high-performance adjuvants with an emphasis on bio-based and eco-friendly solutions, while Stepan Company manufactures specialty surfactants used across herbicide, insecticide, and fungicide formulations. Nufarm Limited, Helena Agri-Enterprises, and CHS Inc. address the distribution and formulation layer, ensuring that surfactant and adjuvant products reach end-users through established crop protection channels, particularly in North American markets.
Huntsman Corporation and Dow Inc. contribute formulation ingredients and performance additives that support spray coverage and active ingredient delivery. Nouryon rounds out the competitive field with renewable-carbon tank-mix adjuvants designed to reduce environmental impact. The company's Adsee Flex 960, introduced in 2025, cuts greenhouse gas emissions by 35 percent compared with conventional ethoxylates, demonstrating how carbon accounting is becoming a product differentiation metric.
Recent industry engagement reinforces these corporate moves. In May 2026, the incoming chair of the Council of Producers and Distributors of Agrotechnology (CPDA) is scheduled to present a session on emerging opportunities in agricultural surfactants at the ICIS World Surfactants Conference, highlighting demand for high-performance, sustainable surfactants in crop protection, soil health, and nutrient delivery. Clariant's March 2025 expansion of its Synergen portfolio further illustrates how manufacturers are responding to precision farming and low-temperature application needs. These developments are not isolated; they signal a coordinated industry pivot toward sustainability, performance reliability, and supply chain resilience.
What the Full Report Delivers: Operational Intelligence for Decision-Makers
The full Worldwide Agricultural Surfactants Market research goes beyond high-level forecasts to provide actionable intelligence across every dimension of the value chain. The report delivers detailed historical revenue data from 2020 through 2025, paired with a forecast extending to 2032, enabling teams to construct scenario-based financial models with confidence. Segmentation analysis breaks down revenue by region, type, application, and substrate, giving strategists the granularity needed to identify high-growth pockets and assess competitive exposure.
The competitive landscape section profiles the leading companies, examining their headquarters, product positioning, and recent strategic moves. This analysis helps clients evaluate potential partnership targets, benchmark their own portfolio against market leaders, and anticipate consolidation or capacity shift scenarios. Recent developments are tracked chronologically, providing context for how product launches, conference announcements, and regulatory milestones are reshaping market expectations in real time.
Industry context sections dissect raw material cost dynamics, regulatory trends, and policy-driven demand signals, translating macro-level noise into operational implications. Executives can use these insights to stress-test pricing strategies, evaluate sourcing alternatives, and align R&D roadmaps with the regulatory curve. The report's structure is designed for cross-functional use, supporting marketing teams seeking positioning clarity, procurement groups managing feedstock risk, and finance leaders building revenue models that reflect realistic growth paths.
Strategic Takeaways for 2026 Decision-Making
As the market moves through its forecast period, several strategic priorities emerge for companies operating in or adjacent to agricultural surfactants. First, sustainability is no longer optional; it is a procurement requirement. Formulators and end-users increasingly demand biodegradable, low-impact adjuvant systems, and early movers who can validate environmental credentials through recognized certifications will gain contractual advantage.
Second, raw material volatility demands proactive supply chain design. Companies that rely heavily on petroleum-based feedstocks or palm-derived fatty alcohols face margin pressure when commodity prices spike. Diversifying feedstock sources, exploring fermentation-based pathways where economics allow, and building hedging mechanisms can protect profitability during turbulent input cycles.
Amino Acid Surfactants Market
Third, regional regulatory divergence requires localized formulation strategies. A surfactant blend that satisfies North American application standards may not meet European compliance criteria, and Asia-Pacific markets may favor different performance profiles based on crop types and spraying practices. Companies that invest in regionally tailored adjuvant portfolios will be better positioned to capture demand across divergent policy environments.
Finally, competitive positioning will increasingly depend on integration and technical support. Suppliers that can offer tank-mix compatibility data, low-temperature performance validation, and precision-farming application guidance will differentiate themselves beyond price competition. Distributors and formulators that combine technical service with reliable product availability will capture loyalty in markets where crop protection decisions are made under tight seasonal constraints.
Conclusion: Intelligence as a Competitive Advantage
The worldwide agricultural surfactants market is expanding with measurable momentum, but growth alone does not guarantee success. The companies that thrive in 2026 and beyond will be those that translate market data into operational decisions: right-sizing product portfolios, anticipating regulatory shifts, managing feedstock risk, and aligning with the sustainability expectations of formulators and growers alike. Our full research report provides the depth, granularity, and forward-looking analysis required to make those decisions with confidence. For executives seeking to move from high-level awareness to precise strategic action, the complete market intelligence is available through our official research portal, where detailed segmentation data, company profiles, and forecast models can be accessed in full.
For detailed analysis of this topic, please visit the official page: Worldwide Agricultural Surfactants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com