

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Opto-Isolators Market to Reach $4.89B by 2032 at 5.78% CAGR

Strategic Isolation: Navigating the Global Opto-Isolators Market Outlook 2026-2032
The opto-isolator market stands at a critical inflection point. As electronic systems grow increasingly complex and power densities rise across industrial, automotive, and telecommunications infrastructure, the demand for reliable galvanic isolation has transitioned from a design consideration to a strategic imperative. PW Consulting's latest Worldwide Opto-Isolators Market research delivers a comprehensive, data-driven examination of this evolving landscape, providing decision-makers with the analytical rigor required to navigate supply constraints, regulatory shifts, and intensifying competition through the 2032 forecast horizon.
This report is not merely an aggregation of historical figures. It is a forward-looking strategic instrument designed to inform capital allocation, supplier qualification, product roadmap planning, and geographic expansion decisions. By synthesizing granular segmentation analysis with real-time industry dynamics, the study equips engineering leaders, procurement directors, and corporate strategists with actionable intelligence that transcends surface-level market summaries.
Executive Market Trajectory: From Recovery to Sustained Expansion
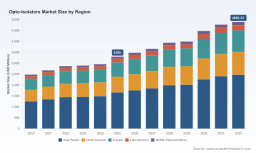
The global opto-isolator market has demonstrated resilient growth over the past half-decade, recovering from early-pandemic supply disruptions and capitalizing on structural demand drivers across multiple end-use sectors. Historical revenue data from 2020 through 2025 reveals a clear upward trajectory, with total market valuation climbing from approximately 2.48 billion USD to 3.30 billion USD. This foundational growth sets the stage for an accelerating forecast period, during which the compound annual growth rate is projected at 5.78 percent through 2032.
By the close of the forecast window, the market is expected to surpass the 4.89 billion USD threshold, reflecting sustained investment in high-voltage power conversion, electric vehicle charging infrastructure, industrial automation networks, and next-generation telecommunications equipment. The pace of expansion will not be uniform across all segments. Certain application verticals and product categories will outpace the broader average, driven by technological substitution, regulatory mandates, and geographic supply chain realignment. Identifying these pockets of disproportionate growth is essential for companies seeking to optimize portfolio exposure and capture margin-enhancing opportunities.
Understanding the magnitude of this expansion requires more than top-line figures. The interplay between substrate availability, component qualification cycles, pricing elasticity, and regional manufacturing capacity will determine which organizations can execute aggressively and which will face margin compression. Our research dissects these variables with precision, enabling stakeholders to model scenario-based outcomes rather than rely on static projections.
Segmentation Dynamics: Where Growth Concentrates and Why
The opto-isolator market is inherently multidimensional. Product architectures, application requirements, and regional manufacturing ecosystems create a complex matrix of demand signals that cannot be adequately captured through aggregated reporting. This study undertakes a rigorous examination of the three primary segmentation axes: type, application, and region.
Type-Level Architecture and Performance Optimization
Across the product taxonomy, distinct performance profiles dictate adoption patterns. High-speed logic gate devices continue to serve as the backbone of digital communication isolation in microcontroller interfaces and factory automation controllers. Transistor output configurations remain heavily utilized in power supply feedback loops, motor drive gating, and inverter control circuits where cost-efficiency and proven reliability intersect. Triac and SCR output variants maintain relevance in AC switching applications, particularly within smart grid infrastructure and appliance-level power management. Linear optocouplers, meanwhile, address precision analog signal transmission requirements in medical instrumentation and sensitive measurement equipment where non-linear distortion must be minimized.
The competitive positioning within each type category is shaped by factors including switching speed, isolation voltage ratings, common-mode transient immunity, package footprint, and long-term thermal stability. Our analysis maps these technical differentiators against volume demand trajectories, revealing where product evolution is outpacing legacy designs and where incremental improvements yield meaningful competitive advantage.
Application Verticals: Driving Structural Demand
End-use application segmentation provides the clearest window into forward demand elasticity. Industrial automation represents a foundational pillar, fueled by the proliferation of programmable logic controllers, robotics integration, and high-density power conversion in manufacturing environments. Automotive and electric vehicle applications are experiencing a structural acceleration, driven by the electrification of powertrains, onboard charger architectures, battery management system isolation requirements, and the gradual adoption of high-voltage traction platforms.
Telecommunications infrastructure continues to demand robust isolation solutions for base station power modules, optical network equipment, and power factor correction circuits. Consumer electronics applications, while more price-sensitive, remain volume-significant, particularly where regulatory standards mandate reinforced insulation for equipment operating above specific voltage thresholds. Medical device applications, though smaller in absolute revenue contribution, exhibit high barriers to entry and stringent qualification requirements that create durable customer relationships and premium pricing environments.
Each application vertical carries distinct qualification timelines, volume volatility profiles, and supply chain dependencies. The report isolates these characteristics to help organizations align production planning, inventory strategies, and engineering resource allocation with the realities of their target markets.
Regional Distribution and Supply Chain Realignment
Geographic demand patterns reflect both historical manufacturing footprints and emerging investment flows. Asia Pacific continues to command the largest share of aggregate revenue, supported by extensive electronics manufacturing capacity, growing domestic automotive production, and expanding industrial infrastructure investment. North America and Europe maintain substantial market presence, driven by high-reliability industrial controls, specialized medical device manufacturing, and advanced telecommunications deployments.
Latin America and the Middle East and Africa represent smaller but evolving demand centers, where infrastructure modernization programs and selective electronics manufacturing initiatives are gradually expanding addressable markets. The regional landscape is further complicated by export control frameworks, localized content requirements, and shifting semiconductor supply chain strategies that influence where components are designed, fabricated, and distributed.
Our geographic analysis moves beyond revenue distribution to examine lead time differentials, regional pricing variances, logistics bottlenecks, and the strategic implications of near-shoring and friend-shoring initiatives. These insights are critical for organizations evaluating warehouse positioning, dual-sourcing strategies, and long-term supplier partnerships.
Competitive Landscape: Ten Key Players Shaping the Market
The opto-isolator market is characterized by a concentrated group of established manufacturers alongside specialized firms that compete on niche performance attributes, qualification depth, and regional service capabilities. Our competitive assessment evaluates the strategic positioning, product portfolio breadth, and recent operational developments of ten companies that collectively exert significant influence over pricing, innovation cadence, and supply availability.
-
Toshiba Electronic Devices & Storage Corporation maintains a broad optocoupler lineup spanning high-speed digital, power, and industrial isolation devices. Its TLP series supports power supply, motor drive, and inverter applications, with recent product sampling activities focused on ultra-compact quad-channel architectures for space-constrained industrial controls.
-
Broadcom Inc. delivers HCPL and ACPL series devices engineered for high-reliability deployments in industrial automation, renewable energy systems, and electric vehicle platforms. The company's recent multi-year supply agreement for gate driver components with a major EV manufacturer underscores the strategic importance of long-term procurement commitments in high-growth verticals.
-
Vishay Intertechnology, Inc. produces VOS and IL series optocouplers, including gate driver and high-voltage isolation products for consumer electronics, telecommunications, and automotive applications. Updated catalog releases expanding temperature operating ranges reflect ongoing efforts to address harsh-environment industrial requirements.
-
Lite-On Technology Corporation offers LTV series digital and analog opto-isolators tailored for power management, medical device integration, and home appliance applications. Its portfolio emphasizes integration flexibility and cost-optimized packaging for high-volume consumer and appliance manufacturing.
-
Everlight Electronics Co., Ltd. supplies EL series components focused on signal transmission in industrial control systems, smart grid infrastructure, and consumer products. Its offerings contribute to broader ecosystem compatibility in applications where standardized interfaces and reliable communication isolation are paramount.
-
ON Semiconductor (onsemi) provides FOD and NCV series devices engineered for automotive, industrial, and safety-critical isolation scenarios. Recent qualification achievements for automotive-grade high-speed components highlight the company's emphasis on meeting rigorous reliability standards in electrified transportation and industrial safety applications.
-
Infineon Technologies AG manufactures optiMOS and EiceDRIVER opto-isolators optimized for gate driving in silicon carbide and gallium nitride power systems, including EV chargers and solar inverter architectures. Its recent launch of a high-isolation opto-driver for SiC MOSFETs demonstrates continued investment in next-generation wide-bandgap ecosystem support.
-
Renesas Electronics Corporation delivers PS and RV series high-speed optocouplers for microcontroller interfaces, factory automation networks, and telecommunications equipment. Its product strategy aligns with the broader industry push toward higher data rates and lower latency in industrial and communication control loops.
-
Sharp Corporation manufactures PC series logic gate and high-output optocouplers serving printer systems, medical equipment, and security infrastructure. Its legacy manufacturing capabilities and specialized output configurations maintain relevance in applications where output drive strength and logic compatibility drive selection decisions.
-
Isocom Components Ltd. specializes in MOC and TLP-compatible optocouplers targeting military, aerospace, and high-reliability industrial environments. Its focus on extended qualification standards and application-specific customization positions it within supply chains where failure tolerance is exceptionally low and long-term component availability is a contractual requirement.
Together, these companies represent a market structure in which the top five participants account for a substantial share of aggregate revenue, while the broader field competes through specialization, regional responsiveness, and targeted qualification wins. Our competitive analysis examines product roadmap alignment, capacity expansion signals, pricing behavior, and partnership dynamics to provide a actionable view of where market share will shift and which capability gaps will create vulnerability.
Industry Dynamics: Constraints, Catalysts, and Structural Shifts
Market growth does not occur in a vacuum. Several concurrent forces are reshaping the opto-isolator supply-demand equilibrium, and understanding their interactions is essential for realistic planning.
Material Availability and Production Economics
Silicon wafer pricing has increased year-over-year due to tightened supply for optocoupler fabrication, directly influencing unit economics and prompting manufacturers to evaluate cost-pass-through strategies, design optimization, and alternative substrate utilization. Simultaneously, lead times for high-common-mode-transient-immunity models have extended into the 20-to-24-week range amid gallium arsenide substrate shortages, creating planning complexity for production scheduling and inventory buffering. Average pricing for 5kVrms digital opto-isolators has also trended upward, reflecting the combined pressure of material constraints, qualification costs, and elevated demand in certain application segments.
Regulatory and Standards Evolution
The IEC 62368-1:2023 standard mandates reinforced insulation for opto-isolators operating above 1kV in consumer electronics, altering compliance requirements for manufacturers and embedding new design constraints into product development cycles. Organizations that proactively align their isolation architectures with these requirements will reduce redesign risk and accelerate time-to-market, while those treating regulatory evolution as a retrospective compliance exercise may face costly late-stage engineering changes.
Geopolitical and Trade Environment
Export control measures associated with the US CHIPS Act have introduced restrictions on advanced opto-isolator technology transfers to China-listed entities, affecting cross-border collaboration, joint development initiatives, and certain supply chain configurations. These measures require companies to reassess technology sharing agreements, distribution partnerships, and manufacturing footprint strategies to ensure compliance while maintaining competitive access to key markets.
Capacity, Qualification, and Strategic Partnerships
Recent corporate developments illustrate how leading manufacturers are responding to these dynamics. Product launches targeting wide-bandgap power systems, expanded temperature ranges for industrial-grade components, automotive qualification achievements, and multi-year supply agreements with major end-users collectively signal a market in which performance differentiation, reliability certification, and supply security are becoming primary competitive differentiators. The organizations that will capture disproportionate value are those that integrate these elements into a coherent strategy rather than treating them as isolated tactical initiatives.
Strategic Imperatives for 2026 Decision-Makers
The convergence of expanding addressable demand, material and lead-time constraints, evolving regulatory standards, and a concentrated yet dynamic competitive field creates both opportunity and risk. Companies that approach the opto-isolator market with fragmented, reactive planning will likely experience margin erosion, qualification delays, and supply disruption. Conversely, organizations that embed comprehensive market intelligence into their strategic planning can achieve several structural advantages.
-
Portfolio Alignment: Matching product architecture investments to the application verticals and type categories with the strongest growth elasticity ensures that engineering resources and manufacturing capacity are deployed where demand momentum is most durable.
-
Supply Chain Resilience: Understanding regional lead-time differentials, substrate availability patterns, and pricing trends enables more accurate inventory modeling, dual-sourcing decisions, and negotiated procurement terms that protect production continuity.
-
Regulatory Anticipation: Proactively designing for reinforced insulation mandates and evolving safety standards reduces redesign exposure, shortens qualification cycles, and positions products for faster market acceptance in regulated end-use environments.
-
Competitive Positioning: Mapping competitor product roadmaps, recent qualification achievements, and supply agreement activity reveals where market share is vulnerable and where differentiation opportunities exist through performance, packaging, or reliability attributes.
Optical Isolators Market -
Geographic Strategy: Aligning distribution, warehouse positioning, and local qualification support with regional demand patterns and trade restrictions allows companies to optimize service levels while maintaining compliance and managing logistics costs.
These imperatives are interconnected. A pricing decision impacts supplier relationships. A qualification timeline affects application entry. A geographic expansion strategy influences compliance exposure. Only by viewing the market through an integrated analytical framework can leadership teams make decisions that compound advantage over time rather than create isolated tactical wins that erode under shifting conditions.
What This Report Delivers
PW Consulting's Worldwide Opto-Isolators Market research is structured to provide precisely this integrated perspective. The study goes beyond headline figures to deliver a multi-layered analysis that supports concrete decision-making across engineering, procurement, sales, and executive functions.
The report includes detailed historical revenue tracking from 2020 through the base year of 2025, establishing a verified baseline against which forecast trajectories can be evaluated. The forward-looking analysis extends through 2032, applying a compound annual growth rate framework that accounts for segment-level variation, regional divergence, and macroeconomic sensitivity.
Segmentation analysis covers product type, application, and region, with revenue distributions and growth pathways examined in relation to technical requirements, qualification cycles, and supply chain realities. Competitive profiling extends across the ten companies identified as market shapers, incorporating product portfolio assessment, recent corporate developments, and strategic positioning analysis that reveals where competitive intensity is rising and where whitespace opportunities persist.
Industry dynamics are treated as active variables rather than static background conditions. Material pricing trends, lead-time extensions, regulatory mandate timelines, and geopolitical trade restrictions are integrated into the analytical narrative to show how they influence pricing, availability, and market entry timing. Recent product launches, qualification achievements, catalog updates, and supply agreements are evaluated not as isolated news items but as indicators of where manufacturers are directing capability investment and how those investments will reshape competitive dynamics.
Market concentration metrics are examined to clarify the balance between incumbent scale advantages and specialist agility, helping organizations assess whether they are competing in a space where volume and qualification depth dominate or where niche performance, regional responsiveness, and application-specific customization drive value capture.
Worldwide Opto-Isolators Market
Accessing the Complete Intelligence
This article provides a structured preview of the strategic terrain covered in the full study. The detailed segmentation revenue distributions, regional growth pathways, application-level demand trajectories, company-level competitive assessments, and scenario-based market projections are developed in depth within the complete report. Those datasets, combined with the analytical framework described here, form the foundation for concrete strategic decisions across product planning, supplier selection, geographic expansion, and capital allocation.
For executives, engineering leaders, and procurement professionals who require precise, actionable intelligence to navigate the opto-isolator market through 2032, the full Worldwide Opto-Isolators Market research from PW Consulting delivers the comprehensive analysis necessary to move from awareness to execution. The complete report, including all segmentation breakdowns, competitive profiles, dynamic factor analysis, and forecast modeling, is available for review on our research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Opto-Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com