

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Nursing Call Systems Market to Hit $6.05B by 2032 at 11.72% CAGR

Navigating the Future of Healthcare Connectivity: Strategic Intelligence for the Nursing Call Systems Market (2026–2032)
Global healthcare delivery is entering a decisive transformation period, driven by aging demographics, workforce optimization mandates, and the rapid digitization of clinical environments. At the center of this infrastructure evolution lies the nursing call system, a foundational patient-safety network that has evolved from simple wired alert panels into intelligent, interoperable communication hubs. For executives, procurement leaders, and investors navigating capital allocation decisions in 2026, understanding the trajectory of this market is not merely an operational exercise, but a strategic imperative. Our latest Worldwide Nursing Call Systems Market research report provides the analytical framework required to anticipate demand shifts, evaluate competitive positioning, and align technology roadmaps with next-generation care models.
Market Trajectory and Growth Dynamics Through 2032
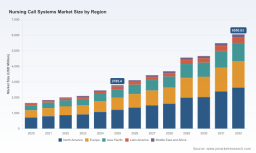
The historical performance of the nursing call systems sector demonstrates consistent upward momentum, reflecting sustained healthcare infrastructure investment and the modernization of aging facility assets. Between 2020 and 2025, the global market expanded from approximately USD 1.65 billion to USD 2.79 billion, underscoring a clear institutional shift toward reliable, scalable communication architectures. Looking ahead, our forecast models project continued expansion through 2032, with the market reaching a multi-billion-dollar valuation as acute care networks, long-term care communities, and outpatient facilities prioritize integrated patient engagement solutions. This growth is anchored by a compound annual growth rate of 11.72 percent over the forecast period, signaling that demand acceleration will outpace broader medical device segments in several regions.
Structural Catalysts Shaping the Forecast
Several converging factors are reinforcing this growth trajectory. Hospital networks are increasingly allocating capital budgets toward patient safety technology, with a measurable reallocation of facility investment toward communication and workflow integration platforms. Simultaneously, regulatory frameworks are tightening interoperability expectations. Compliance with established signaling standards such as UL 1069 remains a baseline requirement for hospital-grade equipment, while wireless deployments in the United States must navigate FDA Class II classification pathways, including 510(k) clearance processes for advanced radio-enabled modules. Beyond device-level compliance, healthcare systems are operating under reimbursement structures that bundle capital expenditures within diagnosis-related group frameworks, meaning that nursing call infrastructure is evaluated through the lens of long-term operational efficiency rather than standalone line-item spend.
Equally significant is the mandate for electronic health record interoperability. The integration of nurse call platforms with clinical data ecosystems using standardized health information exchange protocols is no longer optional for facilities pursuing seamless care coordination. This requirement has accelerated the transition from standalone alert systems to networked communication solutions capable of exchanging context-rich patient data. Together, these regulatory and operational pressures are compressing vendor evaluation cycles and elevating the strategic value of forward-looking procurement planning.
Technology Segmentation and Deployment Realities
The market is structurally divided across technology architectures that serve distinct clinical environments, facility maturity levels, and deployment constraints. IP-based nurse call systems have emerged as the dominant architecture for modern acute care facilities, offering centralized management, scalable network integration, and native compatibility with broader smart hospital initiatives. Wireless nurse call platforms are gaining traction in retrofit projects, senior living environments, and facilities requiring flexible modular expansion without extensive structural rewiring. Wired systems continue to maintain a reliable footprint in new construction and regions where regulatory or infrastructure preferences favor fixed infrastructure. Each architecture carries distinct total cost of ownership profiles, installation timelines, and integration pathways, and the optimal selection depends heavily on facility typology, regional deployment norms, and the desired level of electronic health record connectivity.
End-User Demand Patterns Across Care Settings
Demand is distributed across multiple care delivery environments, each with unique communication requirements and procurement rhythms. Hospitals represent the largest institutional demand center, driven by the need for integrated patient monitoring, staff workflow optimization, and compliance with acute care signaling standards. Nursing homes and assisted living centers constitute a substantial secondary demand segment, where resident safety, fall prevention, and wandering management have become core evaluation criteria for communication platforms. Ambulatory surgical centers and clinics contribute additional demand, particularly in ambulatory care environments seeking lightweight, scalable communication tools that complement rapid patient turnover and modular facility designs.
A critical insight for 2026 decision-makers is that end-user segmentation is not static. As care models shift toward decentralized and hybrid delivery settings, communication platforms originally designed for single-setting deployment are being reevaluated for multi-site interoperability. Facilities are increasingly prioritizing systems that can bridge acute and post-acute workflows, which is reshaping vendor selection criteria and accelerating demand for modular, software-defined architectures.
Competitive Landscape and Strategic Positioning
The vendor landscape is characterized by a mix of established medical device manufacturers, specialized nurse call providers, and communication technology firms expanding into healthcare environments. Market concentration indicators reveal a moderately consolidated competitive structure, with leading participants holding meaningful share while a long tail of regional and niche providers competes on integration capability, service responsiveness, and facility-specific customization. Understanding this competitive architecture is essential for buyers evaluating procurement risk, aftermarket support, and long-term technology roadmaps.
Profiles of Key Market Participants
Rauland remains a recognized provider of Responder nurse call platforms, offering both wireless and wired options with integration pathways for real-time location systems and electronic health records across hospital networks worldwide. Ascom delivers Telligence and smartOne nurse call platforms with DECT and voice-over-Wi-Fi integration, targeting acute care facilities that require robust clinical communication topologies. Baxter, through its Hill-Rom business, markets the Centre Point nurse call system, which emphasizes mobile workflow support and patient monitoring integration across a broad installed base. Stryker, leveraging its Vocera platform, provides wearable badge solutions and nurse call software designed for hands-free clinical communication. TekTone offers nurse call solutions tailored to long-term care and senior living settings, incorporating wander management and reporting capabilities.
Jeron Electronic Systems supplies Pro-Alert and SpectraLink solutions with voice and text messaging capabilities for hospitals and senior living environments. Cornell Communications focuses on nurse call and emergency response systems engineered to meet applicable safety standards for skilled nursing facilities. Alpha Communications provides wireless and entry-point nurse call systems deployed across apartments, hospitals, and assisted living environments globally. Vigil Health specializes in wireless nurse call technology with resident monitoring and fall detection features for senior care communities. Tunstall delivers community care alarm and telecare nurse call solutions with a strong footprint in European and Australian markets. Caretronic develops sensor-based nurse call systems incorporating AI-assisted fall prevention for Nordic and European deployments. Courtney-Thorne provides nurse call systems with DECT telephony integration suited to United Kingdom NHS hospital environments.
Recent Industry Developments Shaping Vendor Momentum
Recent vendor activity highlights the speed at which product roadmaps, regulatory compliance, and commercial contracts are reinforcing competitive positioning. In September 2025, Ascom introduced the myco 4 smartphone with enhanced nurse call interoperability for European hospitals. In June 2025, Stryker secured a multi-year contract for Vocera nurse call deployment across 50 United States hospitals. In March 2025, Baxter updated certification status for its Centre Point nurse call system to support expanded wireless features. In November 2024, Rauland showcased Responder 6 with analytics capabilities at a major international medical trade event. In August 2024, TekTone expanded its catalog with a second-generation wireless module for its MyCall platform.
Worldwide Nursing Call Systems Market
These developments are not isolated product updates; they signal broader strategic shifts toward mobility, interoperability, analytics integration, and expanded wireless validation. For procurement teams, this means that competitive evaluation must look beyond headline specifications and examine vendor capacity to support regulatory evolution, integrated clinical workflows, and post-deployment service reliability.
Strategic Considerations for 2026 Capital and Procurement Planning
As organizations finalize 2026 investment plans, several strategic considerations should guide market engagement. First, interoperability requirements are widening the scope of procurement evaluation. Nurse call systems are increasingly assessed as nodes within a broader clinical communication architecture, meaning that integration readiness with electronic health records, alarm management workflows, and mobile device ecosystems can materially influence total value. Second, facility lifecycle planning is becoming more important than unit-price comparisons. Retrofit constraints, phased deployment capability, and vendor-supported migration pathways can determine whether a solution scales gracefully or becomes a future integration bottleneck.
Decision Levers for Buyers and Investors
-
Evaluate architecture flexibility across IP, wireless, and wired deployment scenarios to ensure alignment with facility modernization timelines and capital constraints.
-
Assess vendor compliance capabilities in relation to signaling standards, wireless device clearance expectations, and interoperability mandates for clinical data exchange.
-
Prioritize platforms that support long-term operational efficiency by integrating patient monitoring workflows, mobile communication tools, and analytics-ready data structures.
-
Examine aftermarket service models, regional deployment support, and training capacity, as these factors frequently determine realized value after installation.
-
Align procurement timelines with broader healthcare capital budgets, recognizing that nurse call upgrades are often bundled within facility-wide patient safety investment initiatives.
Nurse Call Systems Market
Conclusion: Turning Market Intelligence into Forward-Deployed Advantage
The Worldwide Nursing Call Systems Market is entering a period of accelerated structural change, shaped by regulatory modernization, interoperability mandates, wireless adoption, and expanding demand across acute and post-acute care environments. The market expansion projected through the end of the decade reflects more than incremental growth; it signals a broadening definition of what a nurse call system must accomplish within contemporary healthcare delivery. Organizations that approach procurement and investment decisions with a clear view of technology segmentation, competitive dynamics, and regulatory context will be better positioned to capture operational value and reduce implementation risk.
This report is designed to provide the analytical depth necessary to support that decision-making process. It consolidates market sizing, growth trajectory insights, segmentation analysis, competitive profiling, and industry development tracking into a unified strategic framework. To access the full dataset, detailed segmentation breakdowns, comprehensive vendor assessments, and forward-looking scenario analysis, we invite you to explore the complete research publication for the definitive intelligence required to navigate the next phase of healthcare communication infrastructure investment.
For detailed analysis of this topic, please visit the official page: Worldwide Nursing Call Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com