

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Opacifying Agent Market to Reach $27,109.83M by 2032 at 4.2% CAGR

Strategic Clarity in an Opaque Market: Navigating the Global Opacifying Agent Landscape in 2026
In the complex hierarchy of industrial supply chains, few components are as fundamentally critical yet subtly influential as opacifying agents. While rarely visible to the end consumer, these materials define the aesthetic, functional, and regulatory compliance of products ranging from architectural coatings to personal care formulations. As we move through 2026, the global opacifying agent market stands at a inflection point, characterized by steady growth trajectories, shifting competitive dynamics, and an evolving regulatory environment that demands precise strategic planning.
PW Consulting has released a comprehensive Worldwide Opacifying Agent Market study designed to equip stakeholders with the actionable intelligence needed to navigate this landscape. This article serves as a strategic overview of the market dynamics detailed in our full report, highlighting the macroeconomic trends, competitive maneuvers, and operational challenges that will define decision-making in the coming years. While we provide a high-level view of the market trajectory here, the granular data required for precise capacity planning, sourcing strategies, and investment appraisal is reserved for our complete intelligence suite.
Macroeconomic Trajectory and Market Valuation
Understanding the scale and velocity of the opacifying agent market is the first step in contextualizing investment risks and opportunities. Our analysis covers historical performance from 2020 through the base year of 2025, with forecasts extending out to 2032. This longitudinal view allows organizations to distinguish between cyclical fluctuations and structural growth trends.
Worldwide Opacifying Agent Market
The market has demonstrated resilience and consistent expansion over the past half-decade. Revenue figures have climbed steadily from the 2020 baseline, reflecting sustained demand across core industrial sectors. As we project forward from the 2026 forecast period through 2032, the market is expected to maintain a positive compound annual growth rate. This growth is not merely a function of volume expansion but is also influenced by value optimization across different product types and geographic regions.
Key macroeconomic indicators tracked in the study include:
- Historical Performance (2020-2025): A detailed review of revenue evolution, capturing the impact of post-pandemic recovery and supply chain stabilization.
- Forecast Period (2026-2032): Projected revenue trajectories that account for capacity adjustments, raw material cost volatility, and demand shifts in end-use industries.
- Growth Rate Analysis: Assessment of the CAGR over the forecast horizon, providing a benchmark for potential ROI on capacity expansion or M&A activities.
While the overall market size continues to expand, growth is not uniform across all segments. Our full report dissects these variations without exposing sensitive competitive data, allowing clients to benchmark their own performance against market averages while maintaining strategic confidentiality.
Supply-Side Dynamics and Competitive Landscape
The opacifying agent industry is characterized by a moderately concentrated competitive structure. With a significant portion of market revenue captured by a handful of key players, strategic positioning is critical. The market concentration metrics indicate that while there is room for niche players and regional specialists, the bulk of volume and value is driven by integrated giants with extensive global footprints.
Our study profiles the core entities shaping the market. These companies range from diversified chemical conglomerates to specialized pigment producers. The competitive analysis goes beyond simple revenue rankings; it examines strategic postures, geographic strengths, and technological capabilities.
Key Market Participants Include:
- The Chemours Company: A major global producer known for its Ti-Pure titanium dioxide pigments, serving as a primary opacifying agent across coatings and plastics.
- Tronox Holdings plc: A vertically integrated producer supplying titanium dioxide and feedstock, with a significant presence in paints, coatings, and paper applications.
- KRONOS Worldwide, Inc.: Specializes in titanium dioxide pigments with a strong focus on architectural and industrial coatings, as well as cosmetics.
- LB Group (Lomon Billions): One of the largest Chinese producers of high-performance titanium dioxide pigments, leveraging scale in the Asia Pacific region.
- Venator Materials PLC: A supplier of titanium dioxide and functional additives, actively restructuring its portfolio to focus on core competencies.
- Dow Inc.: Offers ROPAQUE opaque polymers, providing polymeric opacifiers that serve as partial replacements for TiO2 in specific formulations.
- Tayca Corporation: A Japanese producer focusing on titanium dioxide and specialty opacifying materials for industrial and cosmetic uses.
- Evonik Industries AG: Provides specialty chemicals, including zinc oxide-based or hybrid opacifiers for cosmetics and personal care.
- Imerys: Supplies natural mineral-based opacifiers, such as ImerCare Opaque, for gels, shampoos, and personal care products.
- Arkema SA: Offers chemical solutions including opacifiers for coatings, plastics, and various material applications.
The competitive landscape is not static. Recent corporate maneuvers highlight the volatility and strategic recalibration occurring among these leaders. For instance, in early 2026, Tronox Holdings announced the permanent closure of its 46,000-metric-ton Fuzhou TiO₂ plant, citing sulfur feedstock cost escalation and market oversupply. This move underscores the sensitivity of production economics to raw material costs and regional demand balances.
Similarly, portfolio restructuring has been evident among other key players. In late 2025, Venator Materials agreed to divest its UK TiO₂ facility to LB Group, signaling a shift in geographic asset ownership and operational focus. Concurrently, Kronos Worldwide completed the acquisition of Venator's 50% stake in the Louisiana Pigment Company TiO₂ facility, gaining full control over a significant production asset. These transactions illustrate the ongoing consolidation and optimization of supply assets. Furthermore, pricing strategies remain dynamic; The Chemours Company implemented global price increases for TiO2 grades in plastics and coatings segments in late 2025, reflecting the interplay between cost pressures and margin protection.
In our full report, we analyze the market share distribution and competitive positioning of these entities in detail. The specific revenue splits by company and region are critical for understanding vulnerability to supply shocks and pricing power, but these figures are disclosed only to subscribers of the complete study to preserve the integrity of our competitive intelligence.
Segmentation and Application Drivers
The demand for opacifying agents is distributed across a diverse array of industrial and consumer applications. Each segment possesses unique growth drivers, regulatory constraints, and technical requirements. While the overall market grows, the appeal of specific segments varies based on regional industrialization levels and consumer trends.
Primary Application Sectors:
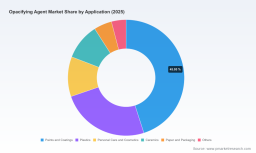
- Paints and Coatings: This remains a dominant consumption hub for opacifiers, driven by infrastructure development, automotive refinishing, and architectural maintenance. The demand here is closely tied to housing markets and industrial construction activities.
- Plastics: Opacifiers are essential for achieving aesthetic standards and UV protection in plastic packaging and automotive components. The shift toward durable and high-performance plastics supports steady demand in this sector.
- Personal Care and Cosmetics: This segment requires high-purity and compliant opacifying agents. Formulations for lotions, creams, and powders rely on specific grades that meet strict safety and regulatory standards.
- Ceramics: Industrial ceramic production utilizes opacifiers to achieve desired visual and physical properties, linked to construction and consumer goods manufacturing.
- Paper and Packaging: Opacity is a critical quality parameter for packaging materials, influencing consumer perception and product protection.
Product Type Dynamics:
The market is also segmented by the type of opacifying agent employed. Titanium Dioxide remains the cornerstone of the industry, valued for its high refractive index and versatility. However, alternative types such as Zircon Silicates and Opaque Polymers are gaining traction in specific applications where TiO2 faces regulatory hurdles or cost disadvantages. For example, polymeric opacifiers are increasingly explored as partial replacements in architectural coatings to manage costs and address specific regulatory concerns regarding TiO2 classification in certain jurisdictions.
Natural mineral-based opacifiers also hold a position, particularly in personal care, where brands seek natural derivative ingredients. The balance between synthetic pigments and natural minerals shifts based on end-user preferences and regulatory frameworks. Our report provides a detailed breakdown of revenue contribution by type and application, allowing clients to identify high-growth niches without exposing the specific market share percentages of competitors in each segment.
Critical Industry Dynamics: Regulation, Raw Materials, and Innovation
Strategic decision-making in 2026 requires a robust understanding of the external forces shaping the market. Regulatory changes and raw material economics are two of the most potent variables influencing supply stability and cost structures.
Regulatory Landscape
The regulatory environment for opacifying agents, particularly titanium dioxide, has been subject to intense scrutiny and evolution. A significant development occurred in August 2025, when the European Court of Justice upheld a ruling that titanium dioxide is no longer classified as a category 2 carcinogen in the EU. This ruling provides regulatory clarity for manufacturers and users within the European market, potentially stabilizing demand that may have been dampened by uncertainty.
However, regulatory complexity persists. Titanium dioxide was added to the Global Automotive Declarable Substance List (GADSL) Reference List on February 1, 2025, triggering reporting thresholds above 0.1% by weight. This affects automotive suppliers and manufacturers who must now adhere to stricter disclosure requirements. Additionally, EU restrictions on titanium dioxide nanoparticles in certain leave-on cosmetics continue to drive reformulation efforts toward compliant opacity systems. These nuances require formulators and procurement teams to stay ahead of compliance curves, a topic covered extensively in our regulatory analysis section.
Raw Material Economics
The cost foundation of opacifying agents is deeply tied to raw material availability and pricing. Ilmenite prices in the USA reached 351 USD/MT in December 2025, reflecting firmer procurement from titanium dioxide producers. This pricing pressure is linked to the ongoing competition among feedstock sources, including ilmenite, leucoxene, rutile, and slag, as reported in the USGS Mineral Commodity Summaries 2026.
Fluctuations in feedstock costs directly impact production margins and pricing strategies for downstream opacifying agents. Companies must navigate these cost volatilities through long-term contracts, vertical integration, or alternative sourcing strategies. Our study incorporates raw material trend analysis to help clients model cost scenarios and hedge against supply chain disruptions.
Worldwide Phosphating Agent Market
Innovation and Reformulation
Beyond regulation and cost, innovation is reshaping the market. The push for sustainable solutions, reduced environmental impact, and enhanced performance is driving R&D in opacifying technologies. From hybrid systems that blend minerals with polymers to specialized grades designed for specific cosmetic textures, innovation is creating new value propositions. Companies like Evonik and Imerys are actively developing specialty solutions that address specific consumer needs while navigating regulatory constraints. Understanding where R&D investments are yielding commercial results is vital for spotting future market leaders.
Strategic Value of the PW Consulting Study
In an environment defined by shifting regulations, raw material volatility, and competitive consolidation, generic market summaries are insufficient for strategic planning. The PW Consulting Worldwide Opacifying Agent Market study offers a depth of analysis tailored for executive decision-makers.
What Our Full Report Delivers:
- Granular Market Sizing: While this overview highlights total market trends, the full report provides specific revenue data for each segment, region, and type, enabling precise market entry or expansion calculations.
- Competitive Intelligence: Detailed profiles of key companies, including their strategic moves, capacity changes, and pricing behaviors, allow for benchmarking and competitive risk assessment.
- Regional Analysis: Breakdown of market performance across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, helping identify high-growth regions and localized risks.
- Regulatory Impact Assessment: In-depth analysis of how specific regulations affect different applications and regions, guiding compliance strategies and formulation choices.
- Forecasting Models: Robust forecasting mechanisms that account for various scenarios, providing a range of potential outcomes for 2026 through 2032.
This study is not merely a data repository; it is a strategic tool designed to answer critical questions. Where should capacity be added? Which applications offer the best margin potential? How will regulatory shifts impact supply chains? What are the competitive threats from major players like Chemours or Kronos?
Conclusion: Navigating the Future
The global opacifying agent market presents a landscape of steady growth tempered by complex operational challenges. As the industry moves through 2026, stakeholders must balance the opportunities presented by expanding demand in coatings, plastics, and personal care against the realities of raw material cost pressures and regulatory evolution. The recent strategic moves by major players—ranging from plant closures to acquisitions—signal a market that is optimizing for efficiency and resilience.
For organizations seeking to secure their position in this market, access to precise, forward-looking intelligence is paramount. The PW Consulting Worldwide Opacifying Agent Market study provides the comprehensive data and analysis required to make informed, confident decisions. We invite industry leaders, investors, and strategists to explore the full report for the detailed segmentation data, regional breakdowns, and competitor metrics that will anchor their 2026 strategic planning.
Unlock the full potential of your strategy with deep market intelligence. Access the complete Worldwide Opacifying Agent Market report to secure your competitive edge.
For detailed analysis of this topic, please visit the official page: Worldwide Opacifying Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com