

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Radiation-Hardened SSD Market Hits $615.14M in 2025, Projected 11.48% CAGR to 2032

Navigating the Radiation-Hardened SSD Market: Strategic Intelligence for the 2026 Decision-Maker
The space economy is no longer a distant frontier; it is a rapidly materializing infrastructure layer that demands resilience at every node. At the heart of this infrastructure lies data storage, and specifically, the radiation-hardened solid-state drive. As commercial constellations multiply and defense architectures evolve, storage solutions must survive ionizing radiation that would cripple conventional enterprise drives. This shift has transformed the rad-hard SSD segment from a niche procurement category into a strategic technology conduit. Our latest market research on the Radiation-Hardened SSD Market provides a structured, decision-grade view of this transition, anchored in historical performance from 2020 through 2025 and extended through a forecast horizon reaching 2032.
The research is designed for leaders who must allocate capital, evaluate suppliers, shape roadmaps, and manage risk in environments where tolerance thresholds, supply continuity, and compliance alignment directly determine mission outcomes. Rather than offering a static snapshot, the report treats the market as a dynamic system shaped by technological substitution, constellation economics, and the growing strain on high-density flash supply. It positions decision-makers to look beyond headline figures and engage with the operational realities that will define competitive advantage over the next several years.
The Market Trajectory: A Signal You Cannot Ignore
What the numbers tell us, in aggregate, is that demand has crossed an inflection point. The overall market expanded from roughly 385 million USD in 2020 to more than 615 million USD in 2025, reflecting a compound trajectory supported by sustained orbital deployment, defense modernization, and scientific research investment. Looking forward, the research models continued expansion through 2032, with medium-term projections indicating a passage into territory approaching the 700 million USD mark in 2026 and sustained upward momentum thereafter as constellation architecture matures and storage requirements become more capacity-intensive.
Behind that trajectory sits a market environment that is both opportunity-rich and structurally constrained. The report translates these dynamics into decision context: where growth is being generated, which technological pathways are gaining share, and where procurement teams should anticipate friction. Rather than presenting fragments in isolation, the analysis integrates technology evolution, application pull, and geographic divergence into a single strategic lens. The result is a framework that helps executives distinguish between cyclical fluctuations and durable structural shifts, particularly as high-density NAND supply faces pricing and lead-time pressure from competing enterprise and AI workloads.
Importantly, the report does not stop at aggregate movement. It examines concentration, technology substitution, and application pull as interconnected forces that shape buyer bargaining power, supplier qualification timelines, and technology roadmap risk. Readers emerge with a clearer sense of where margins are being contested, where standardization is advancing, and where specialized engineering remains the gatekeeper to market entry.
Why 2026 Decisions Require Rad-Hard Intelligence Now
For 2026 planning, timing matters. Program cycles in space and defense are long, qualification processes are rigorous, and supply commitments made today can determine operational readiness years later. The research is structured to support decisions that must be defensible under these constraints. It gives procurement and engineering leaders a basis for evaluating storage options not merely by capacity or footprint, but by radiation tolerance, data integrity architecture, screening alignment, and suitability for mission profiles ranging from low Earth orbit to deep space.
This is especially relevant as constellations scale and storage requirements move toward higher capacities with end-to-end data protection, error mitigation, and robust endurance. The report helps stakeholders assess whether a proposed technology route is aligned with near-term deployment needs or whether it carries hidden risk when exposed to radiation environments, thermal cycling, vibration, and long-duration operation. In practical terms, the analysis supports technology selection, vendor diversification, and roadmap synchronization before commitments become irreversible.
The strategic value also extends to competitive anticipation. As market adoption accelerates, suppliers with differentiated shielding approaches, validated screening practices, and advanced error mitigation are gaining attention, while buyers are increasingly sensitive to capacity availability, qualification lead times, and supply continuity. The research clarifies which capabilities are becoming table stakes and which remain differentiators worth paying for, enabling sharper negotiation positioning and more disciplined sourcing strategies.
Radiation-Hardened SSD Market
What the Report Covers: Operational Depth, Not Just Summary Data
The report is built around actionable content designed for cross-functional use. It moves beyond surface-level sizing to address the operational mechanics that influence purchasing, engineering, and program management. The coverage is organized to make the findings usable in real planning environments, not just as reference material.
Technology Assessment and Substitution Patterns
The analysis examines the major storage technology pathways shaping the market, including single-level cell NAND flash, radiation-tolerant multi-level and triple-level cell NAND, and emerging non-volatile memory approaches such as magnetoresistive RAM and related alternatives. The report evaluates these options in terms of endurance, density, power behavior, data integrity, and fitness for different radiation profiles and mission durations. Technology discussion is connected to practical procurement implications, helping readers understand where legacy architectures remain relevant and where higher-density tolerant memory is shifting the balance.
Application Landscape and Mission Alignment
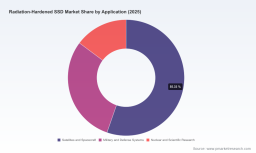
The research maps demand across space platforms, military and defense systems, and nuclear or scientific research environments. It interprets application pull in terms of operational requirements, not just revenue distribution. Readers gain insight into how storage needs differ by mission class, what data integrity and endurance expectations are implied by each context, and how qualification and screening practices influence procurement readiness. This application framing supports decisions about which solutions are most appropriate for specific program profiles and risk tolerances.
Competitive Landscape and Supplier Positioning
A central element of the report is an assessment of how leading suppliers are competing and differentiating. The analysis examines the strategies of companies including Foremay, Exascend, MEMKOR, Mercury Systems, ATP Electronics, and Flexxon, along with broader ecosystem developments involving component and memory suppliers. The report interprets recent activities within the context of product architecture, radiation-hardening methods, shielding design, endurance claims, and data path protection strategies.
Recent developments are integrated as a way to read strategic direction rather than as isolated announcements. For example, the report contextualizes the March 2026 unveiling of a full InterStellar line of radiation-hardened space-grade NVMe and SATA SSDs with Graded-Z shielding, alongside the November 2025 introduction of a radiation-tolerant space-focused SSD line for low Earth orbit missions, and a July 2025 launch of high-density radiation-tolerant SLC NAND flash for space-qualified portfolios. These events are examined not only for what they reveal about individual companies, but also for what they signal about capacity direction, shielding emphasis, and the expanding range of performance options available to mission planners.
Supply, Screening, and Market Dynamics
The research also addresses the external forces that shape execution risk. It discusses screening practices commonly associated with space-grade components, such as alignment with NASA EEE-INST-002 standards, and outlines how qualification discipline affects reliability and procurement timelines. It further explores the supply-side tension created by competing demand for high-density NAND flash, where enterprise and AI workloads can elevate pricing and extend lead times for specialized storage variants. By placing these factors into the market narrative, the report helps buyers anticipate bottlenecks, evaluate supplier resilience, and plan for longer commitment horizons where appropriate.
Procurement, Qualification, and Roadmap Implications
A distinct section is devoted to turning market intelligence into procurement action. It addresses how to evaluate technology readiness, how to interpret tolerance ratings and shielding approaches in the context of mission environment, and how to manage tradeoffs between performance, capacity, power, and reliability. It also supports roadmap planning by helping organizations compare current offerings against emerging architectural trends, so that selections made today remain aligned with anticipated mission and constellation requirements.
Reading the Competitive Field: Differentiation in a Concentrated Market
Market structure matters because it influences both pricing leverage and technology access. The research notes a concentrated competitive environment, where a relatively small group of suppliers accounts for a substantial share of revenue. This concentration is not simply a statistic; it reflects the specialized nature of rad-hard storage, the importance of qualification heritage, and the technical barriers associated with shielding, error mitigation, and radiation-tolerant memory integration. In such a market, differentiation comes from engineering depth, screening rigor, product breadth, and the ability to match storage architecture to mission conditions.
The report interprets how suppliers are positioning themselves across these dimensions. One theme is the broadening of product lines to span different interfaces and mission classes, from low Earth orbit constellations to deeper space applications. Another is the emphasis on data integrity mechanisms, including end-to-end path protection and error mitigation, which are increasingly valued where continuity matters more than raw density alone. A third theme is the integration of shielding and environmental tolerance as part of the storage solution, not merely an add-on, reflecting the reality that radiation, vibration, and thermal stress must be managed together.
The analysis also examines how component-level innovation influences downstream storage offerings. High-density radiation-tolerant memory releases, for instance, can expand the design space for SSDs and recorders, giving suppliers new options for capacity and endurance while also introducing supply sensitivity. By connecting these layers, the report helps readers understand where supplier advantage may be durable and where it may be vulnerable to substitution or supply disruption.
Decision Levers for 2026 and Beyond
For executives and program leaders, the practical value of the research lies in its ability to sharpen decision leverage. The report supports several recurring planning needs:
Worldwide Rad-hard Semiconductor Market
- Identifying which technology pathways are best aligned with specific mission radiation profiles and duty cycles
- Understanding where higher capacity, endurance, or data protection requirements are reshaping storage selection criteria
- Recognizing supplier strengths and limitations in the context of qualification practices and screening standards
- Evaluating exposure to supply constraints and lead-time variability for specialized flash and rad-hard components
- Anticipating how constellation expansion and defense modernization will shift storage demand over the forecast horizon
- Building sourcing strategies that balance performance, continuity, and qualification risk
These levers are particularly relevant when storage choices interact with broader system design, platform schedules, and program risk tolerances. The report is intended to make those interactions visible, so that storage is treated as an integral part of mission architecture rather than as a commodity component.
How to Use This Research
The report is structured to serve multiple internal audiences. Procurement teams can use it to benchmark supplier offers, qualify technology fit, and anticipate lead-time and availability issues. Engineering leaders can use it to evaluate architectural tradeoffs and map storage requirements to mission profiles. Strategy and business development teams can use it to assess competitive directions, identify partnership opportunities, and frame roadmaps in response to evolving demand. Executives can use it to validate investment timing and resource allocation in a market that is expanding but also becoming more technically demanding.
Because the research integrates market trajectory, segmentation context, technology evolution, competitive activity, and supply-side dynamics, it can serve as a common reference point across functions. That shared baseline is valuable when decisions require alignment between engineering feasibility, procurement realism, and strategic timing.
Access the Full Intelligence
This article provides the strategic context and analytical direction behind the Radiation-Hardened SSD Market research, but it is only the opening of the full intelligence package. The complete report contains the detailed segmentation view, competitive positioning detail, technology pathway interpretation, application-aligned procurement implications, and forecast structure needed to support specific 2026 decisions and beyond.
To obtain the full market size breakdown, segmentation insights, and comprehensive competitive analysis, request the complete research or access the source page where the full dataset and interpretive sections are available. That is where the deeper quantitative detail and supplier-by-supplier strategic assessment can be reviewed in support of your planning objectives.
For detailed analysis of this topic, please visit the official page: Radiation-Hardened SSD Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com