

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Card Access Market Hits $13.26B in 2025, Surges at 8.54% CAGR to $23.53B by 2032

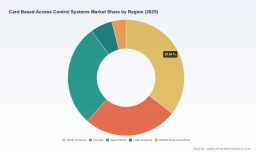
Strategic Intelligence for the Access Control Enterprise: Why the 2026 Worldwide Card Based Access Control Systems Market Report Matters
The global shift toward integrated physical security, identity management, and operational resilience has placed card-based access control at the center of enterprise infrastructure planning. As organizations reconcile legacy deployments with emerging credential standards, cloud-managed platforms, and tightening regulatory expectations, strategic decision-makers require more than headline growth figures. They need a structured, forward-looking view of demand drivers, technology transitions, competitive positioning, and the operational realities that will shape procurement, integration, and risk mitigation through 2032. Our newly published Worldwide Card Based Access Control Systems Market research is designed for precisely that purpose.
This market research is not a static snapshot. It is a decision-support instrument built to help security directors, IT leaders, facility planners, and corporate strategists evaluate where the market is moving, which segments are gaining traction, and how vendors are repositioning around interoperability, cloud services, and high-assurance credentialing. The report anchors its analysis in a rigorous historical and forecast framework, beginning with a base year of 2025 and extending through 2032. Over the historical review period from 2020 to 2025, the market expanded from approximately USD 8,840 million to roughly USD 13,256 million, reflecting sustained institutional investment in access control modernization across commercial, government, industrial, and institutional environments.
Stadium Access Control System Market
Looking ahead, the forecast period from 2026 to 2032 maps a trajectory of continued expansion. The market is projected to reach about USD 14,363 million in 2026 and climb to approximately USD 23,525 million by 2032, supported by a compound annual growth rate of 8.54 percent. These figures are not presented in isolation. They are contextualized within the operational forces shaping purchase decisions: the migration from legacy proximity formats to multi-technology smart card and contactless credentials, the growing integration of access control with video, intrusion, and building management platforms, and the increasing emphasis on certificate-based security and secure identity workflows. The research translates these forces into actionable intelligence for organizations that must plan budgets, evaluate vendor roadmaps, and align access control investments with broader digital transformation agendas.
Why This Research Is Strategically Relevant in 2026
The 2026 decision environment is defined by a convergence of technology modernization and compliance pressure. Enterprises are no longer asking only whether card-based access control works; they are asking how it fits into an ecosystem of mobile credentials, cloud-managed administration, encrypted communications, and cross-vendor interoperability. At the same time, procurement teams are navigating rising hardware and infrastructure costs linked to broader technology demand cycles, as well as evolving expectations around data sovereignty and on-premises control of credential databases and access logs.
Against this backdrop, the report provides a disciplined framework for interpreting market movement rather than simply documenting it. It helps leadership teams answer questions that directly affect planning cycles: which credential technologies are gaining adoption momentum, how vertical demand differs by security requirement and deployment scale, where regional dynamics are influencing infrastructure choices, and how major vendors are differentiating through platform integration, regulatory alignment, and lifecycle support. By connecting market size and growth patterns to real operational considerations, the research enables more confident capacity planning, vendor evaluation, and long-term investment prioritization.
What the Report Delivers: Operational Depth for Procurement and Planning
The study is structured to support practical use across the enterprise. It combines top-level market quantification with detailed segmentation analysis, competitive profiling, and forward-looking assessment of market dynamics. Readers gain access to a comprehensive view of the market structure, including the principal technology categories, vertical demand patterns, regional distribution of activity, and concentration trends among leading participants.
Worldwide Card Based Access Control Systems Market
Key components of the report include:
- A full historical and forecast revenue analysis that traces market evolution from 2020 through 2032, giving decision-makers a consistent basis for benchmarking growth expectations.
- Segment-level interpretation across card technology types, end-use verticals, and geographic regions, enabling organizations to understand where demand is concentrated and how different deployment contexts influence product and service requirements.
- Competitive landscape analysis that profiles leading manufacturers and platform providers, focusing on their product portfolios, credentialing capabilities, integration strategies, and areas of strategic emphasis.
- Market concentration metrics that clarify the share structure of the industry, helping stakeholders assess competitive intensity and the balance between established platform leaders and specialized solution providers.
- Market dynamics assessment that connects regulatory frameworks, technology standards, infrastructure cost trends, and procurement behavior to the broader trajectory of the market.
Crucially, the report avoids reducing the market to a single number or a generic growth narrative. Instead, it examines how different deployment models, security requirements, and organizational priorities create distinct demand signals. This makes the research particularly valuable for teams evaluating whether to standardize on a specific credential technology, expand into new sites or vertical applications, or reassess their access control architecture in response to changing operational and compliance demands.
Competitive Landscape: Platform Leaders, Credential Specialists, and the Shift Toward Interoperability
The competitive environment in card-based access control is both broad and increasingly layered. Established security hardware manufacturers, building management integrators, and specialized credential and identity providers all compete for enterprise deployments, but they do so with different strategic priorities. Some emphasize multi-technology reader portfolios and migration support. Others focus on high-assurance credentials, government-compliant readers, or cloud-managed administration. A further group extends access control into networked video, intrusion, and unified security platforms.
The report profiles the major companies shaping this landscape, including ASSA ABLOY AB, HID Global, Honeywell International Inc., Johnson Controls International plc, Allegion plc, dormakaba Group, Bosch Security Systems GmbH, Nedap N.V., Suprema Inc., Identiv Inc., Gallagher Group Ltd., Axis Communications AB, SALTO Systems S.L., ZKTeco Co., Ltd., and IDEMIA. Rather than presenting these participants as a simple roster, the research analyzes how their portfolios and recent initiatives reflect broader market directions.
For example, the analysis considers how leading providers are strengthening support for proximity, MIFARE, and multi-technology credentials while also advancing secure identity solutions aligned with government and enterprise requirements. It examines how certain vendors are integrating card-based access with building management, video, and intrusion systems to offer broader facility platforms. It also evaluates how others are differentiating through encrypted communications, high-user-capacity controllers, cloud-managed credential administration, and offline or wireless access models for specialized environments such as hospitality and distributed commercial sites.
Recent product and platform developments reinforce the strategic themes captured in the research. In early 2026, Genetec released new access control capabilities in its Security Center SaaS offering to simplify visitor workflows and support enterprise cloud modernization for card-based credential management. Around the same time, Sentry Interactive introduced an SDK for mass enrollment of PKOC credentials, enabling scalable deployment of interoperable physical and mobile credentials compatible with card-based readers. These moves reflect a market increasingly focused on interoperability, cloud-enabled administration, and flexible credential ecosystems.
Earlier developments also illustrate the pace of platform evolution. In late 2025, Honeywell updated its Pro-Watch platform with expanded cloud management for remote handling of card credentials, access schedules, and alarm events. In early 2025, Allegion launched a new series of RFID card readers with multi-format support for both legacy proximity cards and newer smart card formats, easing system migrations. Meanwhile, Nedap implemented AEOS certificate management and device certificate management, providing end-to-end certificate handling for servers, controllers, and card readers. Together, these initiatives show how competitive differentiation is increasingly tied to lifecycle support, migration ease, and cryptographic assurance rather than hardware alone.
Market Dynamics: Regulation, Standards, Infrastructure Costs, and the Data Sovereignty Question
The report situates market growth within a set of dynamics that are actively reshaping procurement and deployment strategies. One major theme is the role of regulatory and standards-based frameworks in guiding hardware selection and system architecture. Compliance expectations continue to influence government and high-security deployments, where approved reader and credential ecosystems matter significantly. At the same time, critical infrastructure operators face a broader set of considerations around communication pathways and access-related controls, prompting organizations to evaluate not only card readers and credentials but also the networks and management layers that support them.
Another defining dynamic is the emergence of interoperability-oriented credential specifications. Open standards work is expanding the feasibility of cross-vendor credentialing and mobile-compatible access models, reducing dependence on closed ecosystems and giving enterprises more flexibility in phased modernization. This matters because many organizations are simultaneously managing legacy proximity installations and planning future expansions that must accommodate newer smart card and multi-technology environments.
Cost pressure also remains a central operational concern. Recent increases in memory and high-bandwidth memory pricing have raised baseline costs for servers and controllers used in networked card-based access control systems. For enterprises planning large-scale deployments or major platform upgrades, this influences not only hardware budgeting but also the timing and architecture of centralized management infrastructure. The report addresses these pressures directly, helping readers understand how macroeconomic and component-level trends can affect total cost of ownership and deployment sequencing.
Data sovereignty and infrastructure placement considerations add another layer of strategic complexity. Organizations are increasingly weighing the tradeoffs between cloud-managed convenience and localized control of credential databases and access logs. This has prompted a measurable shift among some enterprises toward expanding on-premises storage capacity to mitigate vendor lock-in concerns and meet compliance expectations. The research interprets this trend within the broader market context, showing how infrastructure decisions are becoming inseparable from security policy, risk management, and long-term vendor relationships.
How to Use the Report for 2026 Decision-Making
The value of this research lies in its ability to connect quantitative market structure with qualitative strategic inference. Procurement leaders can use the segmentation analysis to understand which technology and vertical contexts matter most in their operating environment. Security architects can use the competitive and dynamics sections to evaluate vendor differentiation, interoperability options, and compliance alignment. Executive teams can use the forecast framework to test assumptions about growth, investment timing, and the pace of modernization across multiple sites or business units.
Because the report is designed as an intelligence platform rather than a one-time summary, it supports several practical use cases:
- Evaluating whether to prioritize migration from legacy proximity systems to multi-technology or contactless smart card environments.
- Assessing vendor fit based on credentialing capabilities, platform integration, cloud management options, and regulatory alignment.
- Contextualizing infrastructure cost pressures and data sovereignty requirements within long-term deployment planning.
- Benchmarking regional and vertical demand patterns to support expansion, standardization, or diversification strategies.
- Anticipating competitive shifts as interoperability standards, certificate-based security, and cloud-enabled administration become more central to procurement decisions.
Conclusion: Precision Intelligence for a Market in Transition
The worldwide card-based access control market is expanding on a clear trajectory, but its real significance for enterprise decision-makers lies in the changing shape of demand. Growth is increasingly tied to credential modernization, cross-platform integration, secure identity workflows, and the operational realities of cost, compliance, and data control. Our Worldwide Card Based Access Control Systems Market report is built to help leaders navigate that transition with confidence.
The complete research package provides the detailed segmentation analysis, company profiles, concentration metrics, and dynamics assessment needed to move from general awareness to precise planning. For organizations preparing investments, migrations, and vendor strategies for the 2026 to 2032 period, the full report offers the depth required to turn market intelligence into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Card Based Access Control Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com