

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Commercial Satellite Customization Service Market to Hit $17.75B by 2032 Growing at 16.03% CAGR

Navigating the Orbital Economy: Strategic Intelligence for the Worldwide Commercial Satellite Customization Service Market
The Imperative for Customization in a Crowded Sky
The commercial space sector has matured beyond the era of off-the-shelf solutions. As orbits become more congested and mission requirements more specialized, satellite operators and government agencies increasingly demand tailored architectures that align precisely with their operational objectives. From bespoke payloads for Earth observation to fully configured buses for sovereign communications networks, customization is no longer a premium add-on. It is the baseline expectation for market entry and long-term competitiveness.
Our latest research, the Worldwide Commercial Satellite Customization Service Market study, provides decision-makers with a comprehensive, data-driven view of this rapidly transforming landscape. The report is designed to support enterprise strategy through 2032 and beyond, offering senior leaders a clear understanding of market velocity, structural shifts, competitive positioning, and the regulatory currents that will shape procurement, investment, and partnership decisions.
Market Trajectory: A Growth Story Anchored in Structural Demand
The commercial satellite customization market has demonstrated sustained, multi-year expansion. Historical data from 2020 through 2025 reveals a market that has rebounded from early-cycle volatility and entered an accelerated growth phase. Revenue climbed steadily over this period, reflecting the combined effects of orbit diversification, payload sophistication, and the broader commercialization of space infrastructure. The base-year baseline for 2025 establishes a firm foundation for forward-looking projections, while the forecast window from 2026 to 2032 maps the next phase of market evolution.
Momentum continues into the forecast period, with the market projected to maintain a compound annual growth rate of approximately 16.03 percent through 2032. This growth trajectory is not merely a function of volume. It reflects a deeper transformation in how satellite services are conceived and acquired. Customers are moving away from standardized, one-size-fits-all platforms toward mission-specific configurations that address unique orbital slots, data throughput requirements, latency constraints, and sovereign or defense-grade compliance needs. The forecast period captures the compounding effect of these preferences as commercial, government, and scientific end-users expand their footprint across multiple orbital regimes.
Satellite Control Service Market
Currency-denominated revenue metrics tracked in the study reflect a market in which customization services are becoming a distinct, high-value segment of the broader space economy. The report presents these figures in a way that supports financial modeling, scenario planning, and investment prioritization without reducing a complex ecosystem to oversimplified aggregates.
What the Report Delivers: Actionable Intelligence for Executive Decision-Making
The study is structured around practical utility. It goes beyond headline figures to equip strategy teams, procurement leaders, investors, and market-entry planners with the analytical building blocks needed to make informed decisions. The core components include:
- Historical and forecast revenue modeling spanning 2020 through 2032, with a clear base-year anchor and forward-looking scenarios that support budgeting, capacity planning, and market-entry timing.
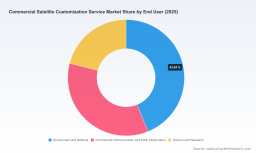
- Segment-level analysis across satellite size, end-user categories, and geographic regions, enabling stakeholders to identify where demand concentration is forming and where whitespace opportunities may exist.
- Competitive landscape profiling of the companies defining the customization service market, with an emphasis on each player's value proposition, service scope, and strategic positioning.
- Recent market-moving developments that illustrate how new capabilities, partnerships, and product-line launches are reshaping the pace and direction of market growth.
- Regulatory and spectrum dynamics that influence deployment timelines, cross-border data handling, and the feasibility of commercial constellations in key jurisdictions.
- Concentration and competitive intensity metrics that help readers gauge market maturity, barriers to entry, and the extent of competitive overlap across the leading providers.
The report is designed as a living reference for strategy teams. It can be used to benchmark internal roadmaps against external market signals, evaluate the timing of satellite procurement or service contracts, assess the risk-return profile of new market entry, and build defensible positions in an industry where differentiation increasingly depends on mission-specific engineering and integration capability.
A Competitive Arena Defined by Scale, Specialization, and Speed
The customization service market is populated by a mix of established aerospace primes, specialized integrators, and emerging players focused on rapid, tailored builds. The competitive fabric is shaped by differences in geographic footprint, orbital expertise, payload integration depth, and the ability to deliver across multiple mission classes efficiently.
Large, multi-domain space firms continue to anchor significant portions of the market. Companies such as Airbus Defence and Space, The Boeing Company, Lockheed Martin Space, Northrop Grumman, Thales Alenia Space, Maxar Technologies, Capella Space, Umbra, Azista USA, York Space Systems, and ISISpace Group each bring distinct strengths. Some emphasize full satellite design, manufacturing, and customization for commercial GEO, MEO, and LEO missions, offering tailored payloads, buses, and mission-specific configurations. Others focus on bespoke satellite platforms delivered with custom payloads and configurations for communications and observation uses. Several providers deliver end-to-end custom satellite solutions that span mission-specific design, integration, and testing for commercial customers, while others supply customized satellite buses, payloads, and full systems for communications and Earth observation missions.
Specialization is a recurring theme. Some firms specialize in custom satellite manufacturing and integration for commercial telecom and observation satellites across various orbits. Others concentrate on high-resolution Earth observation platforms and tailored geospatial capabilities, or offer custom satellite and mission solutions that include spacecraft bus customization, payload configuration, and sovereign system builds for commercial and strategic needs. A subset of providers has built its identity around delivering custom SAR satellite solutions through dedicated mission solution lines, including bespoke buses, payloads, constellations, and advanced mission capabilities. There are also players that provide end-to-end custom satellite manufacturing across LEO, GEO, CubeSat, and SmallSat platforms tailored to specific mission requirements, as well as firms that focus on bespoke and configurable satellite platforms for commercial, government, and defense customers with full-stack customization. In parallel, some integrators specialize in small satellite customization, including CubeSat and nanosatellite platforms and mission-specific integrations for commercial applications.
Worldwide Commercial Satellite Customization Service Market
This breadth of capability means that no single profile fits every procurement need. Instead, buyers evaluate providers based on orbit class, payload complexity, schedule pressure, integration depth, and the strategic importance of sovereign or protected data handling. The study maps these distinctions in detail so that readers can align supplier selection with mission architecture and commercial strategy.
Recent Developments That Are Reshaping the Market
Recent developments underscore how quickly the customization service market is evolving. In 2025, a notable breakthrough occurred in AI-enabled custom satellite bus design. A company achieved automated high-fidelity structural design for rapid custom satellite buses, signed its first commercial payload customer, and secured funding. This milestone points to a future in which design automation compresses timelines and lowers the marginal cost of customization, particularly for rapid bus and payload integration.
Another significant move came from a SAR-focused provider that announced a new business line for building fully operational custom SAR satellite solutions, including buses, payloads, constellations, and advanced mission capabilities for governments and corporations. The launch of this mission solutions line expanded the commercial availability of tailored radar-based Earth observation and monitoring capabilities, reflecting demand for mission-ready, rather than merely component-level, offerings.
A separate development highlighted the growing role of component selection within AI-enabled custom satellite bus design platforms aimed at rapid ESPA-class satellite production. A major provider was selected to supply components for an AI-enabled custom satellite bus design platform, reinforcing the trend toward modular, high-throughput production pipelines that still allow mission-specific tailoring. These developments are not isolated events. They are indicators of a market in which speed, automation, and mission-specific integration are becoming competitive differentiators.
Regulatory Currents and the Reality of Orbit Realities
Customization is not only a technical and commercial challenge. It is also shaped by an environment of spectrum access, orbital resource management, and data sovereignty concerns. The International Telecommunication Union continues to coordinate global radiofrequency spectrum and satellite orbit resources, while ongoing pressure on spectrum allocation reflects the high data-rate demands of commercial satellite systems. As customization becomes more prominent, securing appropriate spectrum and orbital slots becomes integral to mission feasibility.
In the United States, spectrum policy developments have introduced additional pipelines intended to support commercial satellite deployments and operations. These policy shifts matter for the timing and scale of commercialization, especially for operators seeking to expand service coverage and throughput through tailored systems. At the same time, national data sovereignty laws and regulations require careful observance in satellite data handling and operations, particularly for cross-border commercial satellite communications and services. Providers and operators that offer customization must account for these compliance dimensions from the outset, not as an afterthought.
On the deployment side, the schedule for LEO constellation build-out remains a closely watched indicator of market timing. Plans for the launch of initial production satellites for a commercial broadband LEO constellation in late 2026 illustrate how infrastructure rollout continues to accelerate and how customization demands may evolve as operational constellations move from design to in-orbit service delivery. Such milestones serve as benchmarks for when customization services will be called upon not only for initial mission builds but also for payload refresh, integration upgrades, and sovereign or commercial capacity expansion.
Concentration, Market Structure, and Strategic Interpretation
The market exhibits a degree of competitive concentration, with the top three and top five providers representing meaningful shares of revenue. This structure suggests that established players with broad integration capabilities and long-standing mission portfolios maintain strong positions, while nimble specialists and automation-driven entrants are creating new value propositions around speed, flexibility, and mission-specific delivery. For customers, this means a dual imperative: leverage the reliability and mission depth of large integrators where appropriate, while evaluating emerging providers for programs that require faster cycle times or highly specialized configurations.
For investors and strategists, concentration metrics offer a lens on competitive intensity and the sustainability of differentiation. A market that balances concentrated leadership with a growing base of specialized entrants creates opportunities for partnership, acquisition, and vertical integration. It also raises questions about supply-chain resilience, payload availability, and the extent to which customization can be scaled without sacrificing mission quality. The report provides the analytical scaffolding needed to interpret these dynamics in relation to specific business cases.
Why This Study Matters for 2026 Decision-Making
Strategic decisions made in 2026 will shape positioning through the end of the decade. The Worldwide Commercial Satellite Customization Service Market study is built to support those decisions by connecting macro trends with actionable detail. It helps leaders answer questions that go beyond market size:
- Where is customization demand most durable across satellite size categories and end-user segments?
- Which providers are best positioned to deliver mission-specific solutions across GEO, MEO, LEO, CubeSat, and SmallSat environments?
- How are AI-enabled design tools and rapid bus integration changing the economics of customization?
- What regulatory and spectrum realities should be factored into market-entry and procurement timelines?
- How should organizations interpret concentration metrics when evaluating competitive risk and partnership opportunities?
By blending historical performance, forward-looking forecasts, recent developments, and sector context, the study provides a decision-grade foundation for investment planning, supplier selection, mission architecture, and market-entry strategy. It is designed to be used by strategy teams who need more than a narrative. They need a structured intelligence resource that links observable market signals to concrete strategic choices.
Access the Full Market Intelligence
The breadth of customization in the commercial satellite market is expanding as fast as the market itself. Tailored payloads, mission-specific buses, sovereign configurations, rapid small satellite integrations, and AI-assisted design workflows are all converging to redefine what is possible in orbit. Understanding where value is being created, by whom, and under what constraints is essential for any organization operating in or adjacent to the space economy.
The full report contains the detailed segmentation, competitive profiles, recent developments, and regulatory context required to move from high-level awareness to precise planning. It is the kind of intelligence that supports confident decisions in a sector where timing, technical specificity, and compliance can determine success or delay. For leaders who need a complete, verified view of the market and its trajectory through 2032, the complete study is available through PW Consulting's research portal. Accessing the full report unlocks the deeper insights and scenario-ready detail that executive teams need to act with clarity in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Commercial Satellite Customization Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com