

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Millimeter Filters Market Hits $716.44M in 2025, Projected 10.45% CAGR to $1.44B by 2032

Navigating the Decade of Disruption: Strategic Intelligence for the Global Millimeter Filters Market (2026-2032)
The global millimeter wave (mmWave) filter market stands at a critical inflection point. As wireless communication systems migrate to higher frequency bands and defense architectures demand greater spectral purity, the component level has become the bottleneck for system-level performance. PW Consulting's latest research, Worldwide Millimeter Filters Market 2026-2032 , provides a comprehensive strategic framework for stakeholders navigating this high-growth, high-complexity landscape.
Worldwide Millimeter Wave Therapeutic Device Market
Based on historical analysis from 2020 through the base year of 2025, the market has demonstrated robust demand elasticity. The overall market size has evolved from 452.4 million USD in 2020 to an estimated 716.44 million USD in 2025. Looking forward, the forecast period from 2026 to 2032 projects a trajectory of sustained expansion, with the market volume expected to reach 1436.62 million USD by the end of the forecast horizon. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 10.45 percent, signaling a decade where filtering technology will be as strategic as the semiconductor chips they support.
For C-suite executives, supply chain managers, and R&D directors, this report is not merely a collection of statistics. It is a decision-support tool designed to mitigate risk in a supply-constrained environment, identify white spaces in a crowded competitive field, and align product roadmaps with the evolving regulatory and technological realities of the millimeter wave spectrum.
The Macro Picture: Valuation and Growth Vectors
Understanding the velocity of this market is essential for capital allocation. The data indicates that the period between 2025 and 2032 will likely see the market more than double in revenue terms. In 2026 alone, the market is projected to hit 806.74 million USD, bridging the gap between the immediate post-5G rollout phase and the deeper integration of mmWave in automotive and satellite sectors.
However, aggregate numbers only tell part of the story. The true value of this research lies in dissecting the drivers behind the 10.45 percent CAGR. The expansion is not uniform; it is concentrated in specific technological niches where performance requirements are most stringent. The shift from sub-6 GHz deployments to FR2 bands in telecommunications, coupled with the modernization of radar systems for electronic warfare and automotive sensing, creates a compound demand effect.
Investment decisions made in 2026 must account for the continuity of this growth curve. Stakeholders need to evaluate whether their current production capacities or sourcing strategies can sustain participation in a market that grows by approximately 150 to 200 million USD annually over the next half-decade. The report provides the granularity required to model these scenarios without exposing the organization to speculative forecasting errors.
Worldwide Millimeter Filters Market
Market Segmentation: Type, Application, and Geographic Nuances
Technological Segmentation and Demand Priorities
The market is stratified by filter type, each serving distinct signal processing needs. Band Pass Filters currently command the largest share of revenue, reflecting the dominance of selective frequency passing in modern communication chains. Low Pass Filters, High Pass Filters, and Band Stop Filters constitute the remainder of the typology, each addressing specific impedance matching and harmonic suppression requirements.
While specific revenue splits are reserved for the full dataset, the strategic implication is clear: the demand for Band Pass solutions is inextricably linked to the proliferation of broadband wireless standards. Meanwhile, Band Stop Filters are seeing renewed interest in applications where interference mitigation is critical, such as in dense urban electromagnetic environments or within complex radar waveforms. The report details the performance specifications—insertion loss, rejection ratios, and bandwidth capabilities—that are currently defining market winners across these categories.
Application Drivers: From 5G to Electronic Warfare
The application landscape is equally diverse. Telecommunications and 5G Infrastructure represent the primary revenue engine, driven by the need for filters that can handle high frequencies with minimal thermal drift. However, the report highlights a significant secondary vector: Radar and Electronic Warfare. As defense budgets prioritize spectrum awareness and jamming resistance, the demand for high-rejection mmWave filters in this sector is accelerating.
Satellite Communications and Automotive Radar form the emerging growth pillars. The miniaturization of satellite payloads requires filters that are not only high-performing but also exceptionally compact and lightweight. Similarly, the evolution of automotive radar beyond the 77 GHz standard into higher mmWave bands for higher resolution sensing is creating new specification requirements for suppliers. The research analyzes how these application segments interplay, identifying where cross-pollination of technology might occur and where supply chain segregation is necessary.
Regional Dynamics and Supply Chain Realities
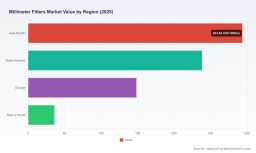
Geographically, the market is distributed across Asia Pacific, North America, Europe, and the Rest of World. Each region presents a unique value proposition. Asia Pacific continues to be a hub for volume manufacturing and integration, particularly within the telecommunications supply chain. North America remains a center for high-performance, defense-grade, and custom RF solutions. Europe maintains a strong presence in specialized industrial and aerospace applications.
Crucially, the report examines the supply chain vulnerabilities inherent in this geographic distribution. The concentration of certain raw material sources, specifically regarding Gallium-nitride wafer supply chains, introduces strategic risk for component suppliers. Understanding where these bottlenecks exist allows procurement teams to diversify sourcing or invest in alternative material technologies before disruptions impact production timelines. Furthermore, the report navigates the complex regulatory environment, including export control parameters that affect the transfer of advanced microwave and millimeter wave items between specific country groups, ensuring compliance strategies are aligned with market opportunities.
Competitive Landscape: Profiles and Strategic Movements
The millimeter filter market is characterized by a mix of established RF giants and specialized niche players. The top five companies currently command approximately 58.8 percent of the market revenue, while the top three hold 42.5 percent, indicating a moderately concentrated landscape where differentiation is key to capturing share.
Key Incumbents and Their Strategic Postures
Several core enterprises define the current competitive baseline. Knowles Precision Devices (DLI), based in the United States, offers catalog and custom 5G mmWave filters for FR2 bands including 26 GHz, 28 GHz, and 39 GHz. Their solutions feature 3 GHz bandwidth and greater than 50 dB rejection in surface-mount packages 20x smaller than alternatives, with temperature stability ranging from -55°C to +125°C. This level of miniaturization and stability sets a high bar for commercial cellular applications.
Reactel, Inc., also United States-based, designs and manufactures high-performance RF, microwave, and millimeter wave filters, multiplexers, and multifunction assemblies covering DC to 67 GHz. Their coverage across aerospace, defense, telecommunications, and industrial markets makes them a diversified player capable of bridging commercial and government sectors.
Benchmark Lark Technology provides compact, lightweight surface-mount mmWave bandpass filters using stripline and substrate-integrated waveguide (SIW) designs for 5-40 GHz applications. Their focus on small footprints and temperature-stable performance for 5G, satcom, and defense positions them well for size-constrained platforms.
Mini-Circuits supplies LTCC and thin-film mmWave filters including bandpass for 5G FR2 bands, low pass up to 30+ GHz, and waveguide bandpass up to 86 GHz. Their broad catalog availability supports rapid prototyping and volume production for a wide range of integrators.
Other notable players include Millimetre Wave Products Inc. (MI-Wave), offering waveguide bandpass filters from ~8 GHz to 140 GHz with low insertion loss and high rejection up to 60 dB; Qualwave Inc., a China-based manufacturer emphasizing low insertion loss and high frequency accuracy for 5G and military radar; TERASi from Sweden, developing ultra-compact E-band waveguide filters using AirCore technology that are 40x smaller than conventional alternatives with less than 0.4 dB insertion loss; and Wainwright Instruments GmbH from Germany, specializing in evanescent mode ridge waveguide designs extending into millimeter wave frequencies for mobile and satellite applications.
Recent Developments Shaping the Trajectory
Market dynamics are not static; they are driven by product launches and strategic announcements. In June 2024, Benchmark Lark Technology introduced new families of compact surface-mount XFH Series and STL Series mmWave bandpass filters for 5-40 GHz with small footprints for 5G, satcom, and defense applications at IMS 2024. This move signaled an intensification of competition in the surface-mount segment.
In April 2025, TERASi announced the development of ultra-compact E-band waveguide filters using AirCore technology, achieving packages 40 times smaller than conventional alternatives with less than 0.4 dB insertion loss for 5G radio systems. This innovation highlights the industry's push toward extreme miniaturization without sacrificing performance, a critical trend for dense urban infrastructure and airborne platforms.
More recently, in March 2026, Reactel, Inc. announced exhibition of a full line of application-specific RF, microwave and mmWave filters, multiplexers, and multifunction assemblies up to 67 GHz at IMS 2026 in Boston. Such activity underscores the ongoing investment in R&D and the willingness of incumbents to defend their turf through comprehensive portfolio showcases.
Strategic Imperatives and Risk Factors for 2026 Decision-Makers
As organizations plan their strategies for the remainder of the decade, several imperatives emerge from the data. First, supply chain resilience is non-negotiable. The concentration of Gallium-nitride wafer supply chains introduces strategic risk for component suppliers in millimeter wave technology including filters. Companies must assess their exposure to single-source dependencies and consider long-term agreements or alternative material qualifications.
Second, regulatory compliance is a market access barrier. The U.S. Bureau of Industry and Security (BIS) export controls on certain advanced computing and semiconductor items include parameters for microwave or millimeter wave items under 3A001.b, effective April 2024 with restrictions to specified country groups. For exporters and multinational supply chains, understanding these parameters is essential to avoid legal pitfalls and ensure uninterrupted delivery to key markets.
Third, differentiation through performance is the only sustainable competitive advantage. With a CAGR of 10.45 percent, the market will attract new entrants. Incumbents and new players alike must focus on metrics that matter to system designers: insertion loss, rejection ratios, size, weight, power, and thermal stability. The report details the specific specification thresholds that currently command premium pricing versus those that are becoming commoditized.
Finally, the shift in application mix requires portfolio agility. While telecommunications remains the volume leader, the high-margin opportunities in radar, electronic warfare, and satellite communications are growing rapidly. Companies that can pivot their manufacturing capabilities or forge partnerships to serve these higher-barrier segments will capture disproportionate value relative to the overall market growth rate.
Conclusion: Turning Intelligence into Advantage
The Worldwide Millimeter Filters Market is poised for a transformative decade. The revenue trajectory from 716.44 million USD in 2025 to over 1.4 billion USD by 2032 reflects a fundamental shift in how the world communicates, defends, and navigates. However, realizing the value of this growth requires more than passive observation. It demands precise intelligence regarding segmentation trends, competitive maneuvering, and the regulatory and material constraints that shape the supply chain.
PW Consulting's Worldwide Millimeter Filters Market 2026-2032 delivers this intelligence. It provides the detailed segmentation splits, historical data analysis, company profiles, and forward-looking strategic assessments necessary to make informed decisions. The market is complex, but the path to success is clear for those equipped with the right data. Stakeholders are invited to explore the full report to unlock the specific regional and application-level details that will define their next strategic move.
For detailed analysis of this topic, please visit the official page: Worldwide Millimeter Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com