

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Military Laser Market Hits $1,420.5M in 2025, Forecast 10.45% CAGR to 2032

Strategic Horizons: Navigating the Worldwide Semiconductor Military Laser Market in 2026
The defense technology landscape is undergoing a paradigm shift where directed energy is moving from experimental prototypes to operational deployment. At the heart of this transition lies the semiconductor laser, a critical enabler for high-energy weapons, precision targeting, and advanced sensing. PW Consulting latest release, the Worldwide Semiconductor Military Laser Market study, offers a comprehensive blueprint for stakeholders aiming to secure a competitive advantage in this rapidly evolving sector. As organizations finalize their strategies for the 2026 fiscal year, understanding the trajectory of this market is not merely an option; it is a strategic imperative.
This intelligence briefing synthesizes macro-level trends, competitive dynamics, and regulatory pressures to provide a clear view of the opportunities and risks that define the landscape. By examining the convergence of technological advancement, government procurement priorities, and supply chain vulnerabilities, decision-makers can align their portfolios with the forces shaping the future of military photonics. The following analysis outlines the strategic value contained within our latest market research, highlighting why immediate access to granular data is essential for sustained growth.
Macro Growth Trajectory and Revenue Outlook
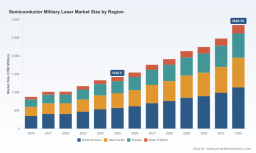
The financial magnitude of the semiconductor military laser market underscores its significance within the broader defense industrial base. Historical performance from 2020 through 2025 reveals a consistent upward trajectory, driven by intensified global security concerns and the operational advantages of directed energy systems over conventional munitions. Our research indicates that the market has expanded from approximately 875.4 million USD in 2020 to an estimated 1420.5 million USD in 2025.
Looking ahead, the forecast period spanning 2026 to 2032 projects sustained momentum with a compound annual growth rate of 10.45 percent. Revenue projections demonstrate a robust climb, positioning the market to reach significant valuation milestones by the end of the decade. This growth is fueled by multi-year investment commitments from defense departments seeking scalable, cost-effective solutions for counter-drone operations, missile defense, and naval protection. The acceleration reflects a broader doctrinal shift where electronic and directed energy capabilities are integrated into layered defense architectures.
For corporate strategists, this revenue expansion signals more than just aggregate opportunity; it highlights the critical importance of timing. Early movers who align their product development cycles with the projected demand surge will capture disproportionate market share. Conversely, organizations that delay entry or misjudge the pace of adoption risk ceding ground to competitors who are already scaling their manufacturing capabilities and securing long-term supply agreements. Understanding the precise inflection points and the variables that could alter the growth curve requires deep access to the segmentation and scenario modeling provided in our full report.
Segmentation Dynamics and Value Pools
The allocation of market value across different dimensions reveals where the highest concentration of opportunity resides. The market is not monolithic; it is fragmented across technology types, application domains, and geographic regions, each with distinct growth drivers and competitive intensities. Our detailed segmentation analysis dissects these layers, providing the granularity needed to identify target segments that align with specific corporate capabilities and risk appetites.
In terms of technology, the landscape encompasses diode lasers, vertical cavity surface emitting lasers, and edge emitting lasers. Each category serves different performance requirements, ranging from high-efficiency pumping for directed energy subsystems to compact modules for sensing and countermeasures. The value distribution across these types reflects the ongoing trade-offs between power output, beam quality, thermal management, and integration complexity. Companies must evaluate which technological pathway offers the best alignment with their core competencies and the evolving specifications of end-user platforms.
Application-wise, the market spans target designation and range finding, directed energy weapons subsystems, lidar and navigation, and laser countermeasures. These application areas correspond to different procurement cycles, budgetary priorities, and technical hurdles. The demand for directed energy subsystems, for instance, is closely tied to fielding schedules for high-energy laser weapon systems on ground, sea, and air platforms. Meanwhile, countermeasure and sensing applications continue to benefit from the proliferation of asymmetric threats and the need for autonomous defensive capabilities. Understanding the relative weight and interaction of these segments is vital for prioritizing R&D investments and go-to-market strategies.
Competitive Landscape and Strategic Positioning
The rivalry within the semiconductor military laser market is shaped by a mix of major defense primes and specialized photonics firms, each leveraging unique assets to secure their position. Our study profiles leading organizations such as Northrop Grumman Corporation, RTX Corporation including Raytheon, Lockheed Martin Corporation, nLIGHT Inc., Power Technology Inc., NUBURU Inc., L3Harris Technologies Inc., Coherent Corp., IPG Photonics Corporation, and Jenoptik AG. These companies represent the core of an ecosystem where vertical integration, partnership networks, and intellectual property play decisive roles.
Northrop Grumman and RTX have been instrumental in integrating semiconductor laser components into high-energy systems designed for counter-UAS and missile defense, often emphasizing thermal management and beam combining as key differentiators. Lockheed Martin continues to advance naval and ground-based directed energy platforms, utilizing diode laser technology as both pumps and direct emitters. nLIGHT has distinguished itself through high-power solutions, including contributions to Army DE M-SHORAD and coherent beam combining initiatives aimed at megawatt-class performance. Meanwhile, specialized players like Power Technology provide ruggedized diode modules for extreme environments, and NUBURU is pushing the boundaries of portable directed-energy platforms using high-power blue semiconductor lasers for counter-drone applications.
Recent developments illustrate the dynamism of this landscape. In early 2026, NUBURU completed a proof-of-concept for a portable directed-energy dazzler targeting counter-UAV defense, reinforcing the trend toward compact, deployable systems. That same month, BluGlass Limited entered a multi-phased development program with a U.S. tier-1 defense prime to create customized visible GaN DFB lasers and gain chips for dual-use applications, receiving an initial order as a signal of growing demand for specialized photonic components. Additionally, Power Technology updated its positioning to highlight high-performance diode modules suited for military defense in harsh operational settings. These moves, alongside earlier strategic alliances such as NUBURU network contract with Maddox Defense and Tekne S.p.A., highlight how partnerships and niche innovations are reshaping competitive dynamics.
The concentration of market share further emphasizes the importance of strategic differentiation. With a CR3 of 42.5 percent and a CR5 of 61.2 percent, the top firms command significant influence, but ample room remains for mid-tier and emerging players to carve out profitable niches through technology specialization, customization, or regional partnership strategies. Our report provides a detailed competitive mapping that allows stakeholders to assess competitor strengths, gaps, and potential vulnerabilities, enabling proactive positioning rather than reactive adaptation.
Industry Dynamics: Regulation, Supply Chains, and Innovation
The operating environment for semiconductor military lasers is heavily influenced by external forces that can accelerate or constrain market growth. Regulatory frameworks, raw material availability, and standardization efforts are among the most critical factors shaping strategic decision-making in 2026 and beyond.
Export controls represent a primary constraint. High-power semiconductor laser stacked arrays with specific wavelength and power parameters fall under dual-use restrictions defined by the Wassenaar Arrangement and U.S. EAR/ITAR frameworks. Compliance is not optional; it is a structural requirement for any organization participating in the global supply chain. Navigating these regulations demands a sophisticated understanding of classification, licensing, and end-use monitoring. Our research embeds these compliance considerations into the competitive analysis, helping firms evaluate how regulatory exposure may impact market access, partnership opportunities, and revenue potential in different jurisdictions.
Supply chain resilience is another pressing concern. Gallium, a critical material for fabricating high-power semiconductor lasers, is subject to geopolitical risks due to reliance on foreign sources and export restrictions. The National Defense Industrial Association analysis of directed energy weapon supply chains has highlighted these vulnerabilities, prompting defense programs to seek diversified sourcing and domestic production capabilities. For manufacturers and integrators, securing the supply of critical materials is as important as advancing the technology itself. The market study examines how material constraints intersect with demand growth, offering insights into potential bottlenecks and mitigation strategies.
On the demand side, the U.S. Department of Defense continues multi-year investments in directed energy programs, including scaling initiatives like HELSI that target 500kW to megawatt-class performance. Semiconductor lasers serve as foundational components, both as direct emitters and as pump sources for solid-state and fiber laser systems deployed in programs such as DE M-SHORAD and HELIOS. Furthermore, innovation pipelines are being sustained through government funding mechanisms such as SBIR and STTR topics, which support the development of bright blue semiconductor laser arrays and photonic crystal surface-emitting lasers for compact, high-brightness applications. These programs not only validate the strategic importance of semiconductor lasers but also create pathways for technology transfer and commercial scaling.
Standardization and integration challenges remain. The path to fielding megawatt-class systems involves overcoming hurdles in beam quality, thermal dissipation, and system reliability. Companies that can deliver modular, scalable components with proven performance in extreme conditions will be better positioned to capture long-term contracts. Our report integrates these dynamics into a cohesive framework, enabling stakeholders to assess how technological maturity, program funding, and regulatory shifts will interplay over the forecast period.
Operational Intelligence Within the Report
Beyond high-level trends, the Worldwide Semiconductor Military Laser Market study is designed as a decision-support tool that delivers actionable intelligence across multiple dimensions. The report structure enables users to drill into the components that matter most to their specific strategic needs, whether they are technology developers, system integrators, investors, or procurement advisors.
Key content areas include detailed market sizing with historical and forecast data, segmentation breakdowns that illuminate relative performance across regions, types, and applications, and competitive profiling that captures the strategic posture of leading firms. The study also examines recent corporate developments, partnerships, and program milestones that signal shifts in the competitive balance. In addition, the report contextualizes these findings within the broader regulatory and supply chain environment, providing a holistic view of the forces that could alter market trajectories.
For teams planning capacity expansion, technology roadmaps, or market entry, the segmentation and scenario information is particularly valuable. It allows for the identification of growth hotspots, the evaluation of regional demand patterns, and the assessment of how different application segments may evolve in response to threat landscapes and budgetary priorities. By combining quantitative projections with qualitative analysis of industry developments, the report equips users with the evidence base needed to justify investments, prioritize partnerships, and mitigate risk.
Worldwide Semiconductor Military Laser Market
The Strategic Imperative for 2026
The convergence of substantial market growth, intensifying competition, and complex external dynamics makes 2026 a pivotal year for organizations operating in the semiconductor military laser space. The revenue expansion projected through 2032 offers a compelling case for investment, but realizing value from that growth requires precise, up-to-date intelligence. Companies must understand not only the size of the opportunity but also where the value pools are forming, which technologies are gaining traction, how competitors are positioning themselves, and what regulatory or supply chain constraints could disrupt plans.
Our market research is built to answer these questions with rigor and clarity. It provides the depth and structure needed to transform raw data into strategic direction. Whether the goal is to secure a foothold in a high-growth segment, optimize a product portfolio for defense procurement cycles, or evaluate partnership and M&A opportunities, the report delivers the insights necessary to act with confidence.
Semiconductor Lasers Market
Stakeholders who rely on generalized industry narratives risk missing the nuances that separate high-performing strategies from suboptimal ones. Access to detailed segmentation, precise forecasts, and competitive intelligence is the difference between guessing and planning. PW Consulting Worldwide Semiconductor Military Laser Market study is designed to fill that gap, offering a single, authoritative source for the intelligence that drives informed decisions.
To fully leverage the insights outlined here and monitor the evolving dynamics of this critical market, readers are encouraged to consult the complete report. The full study contains the granular data, regional and application-level detail, and strategic analysis that are essential for shaping robust 2026 and beyond strategies in the worldwide semiconductor military laser market.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Military Laser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com