

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Phenolic Resin for Kraft Paper Market Worth $580.45M in 2025, Growing at 4.62% CAGR

Phenolic Resin for Kraft Paper Production Market: Strategic Intelligence for 2026 Decision-Making
The global phenolic resin market for kraft paper production stands at a critical inflection point as we enter 2026. Between 2020 and 2025, the sector recorded revenue movements from approximately USD 465 million to USD 580 million, reflecting a compound trajectory shaped by evolving laminate demand, regulatory tightening, and raw material dynamics. Our newly released market research delivers the granular intelligence that executives, procurement leaders, and strategy teams need to navigate the forecast period from 2026 through 2032. This article previews the strategic architecture of the report, demonstrates the analytical rigor behind our findings, and outlines why this intelligence is indispensable for competitive positioning in the coming years.
Macro Trajectory and the 2026 Inflection Point
The market's historical arc from 2020 to 2025 reveals both resilience and structural volatility. Revenue climbed steadily through 2022, experienced a corrective contraction in 2023, and then resumed growth to close the historical window at USD 580.45 million in 2025. This pattern underscores a market that is sensitive to macroeconomic pressures yet anchored by non-discretionary industrial applications. Looking forward, our forecast model projects continued expansion through 2032, with 2026 expected to reach approximately USD 624.69 million and terminal-year revenue approaching USD 796 million. The forecast period CAGR stands at 4.62 percent, a rate that signals moderate but durable growth rather than speculative overheating.
For decision-makers in 2026, the key question is not whether the market is growing but where value will concentrate and which segments will outperform. The report dissects this trajectory through multiple analytical lenses—segment-level performance, regional supply-demand balance, and competitive intensity—without exposing the proprietary numerical breakdowns that form the core deliverable. What we can preview is that the growth narrative will be shaped by divergent regional industrial footprints, material-cost sensitivity, and the pace of regulatory compliance adoption across end-use sectors.
Segment Architecture and Application Dynamics
The research categorizes the market along three primary dimensions: resin type, geographic region, and end-use application. Each dimension carries distinct strategic implications for producers, converters, and downstream laminate manufacturers.
Resin Type Segmentation
The two dominant resin families—Resol-type and Novolac-type phenolic resins—serve different functional and processing requirements in kraft paper impregnation workflows. Resol variants are typically favored for applications demanding faster curing, superior cross-linking density, and enhanced moisture resistance, while Novolac systems offer cost efficiency and specific adhesion characteristics for certain laminate configurations. The report evaluates how each type's share of total market revenue reflects end-user technical specifications, regional manufacturing preferences, and the evolving cost-of-ownership calculations that procurement teams are making in response to phenol price fluctuations.
Application Coverage
Kraft paper impregnated with phenolic resin is deployed across a spectrum of laminate and composite applications. High-pressure laminates represent the largest application pool, driven by construction, furniture, and architectural surfaces where durability and chemical resistance are paramount. Decorative paper impregnation constitutes a significant secondary channel, supporting surfaces that balance aesthetics with performance. Industrial and technical laminates, along with plywood overlay and bonding applications, round out the demand base with specialized functional requirements. The study maps how application mix influences resin grade selection, processing parameters, and margin structures—and how these relationships are shifting as manufacturers optimize for both performance and compliance.
Regional Distribution
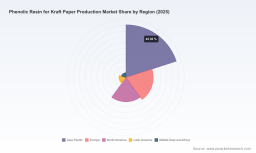
Geographic analysis in the report segments revenue across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. The distribution reflects divergent industrial ecosystems: Asia Pacific's scale advantages and manufacturing intensity contrast with Europe's emphasis on sustainability-aligned production and North America's regulatory-driven specification environment. The research does not merely allocate revenue shares; it examines the structural drivers behind regional performance, including local resin capacity, import dependence, downstream laminate fabrication density, and the impact of cross-border pricing differentials in phenol and formaldehyde feedstocks.
Competitive Landscape: Incumbents, Specialists, and Strategic Positioning
The phenolic resin for kraft paper production market is characterized by a mix of global resin specialists, regional manufacturers, and toll-production arrangements that together create a moderate concentration profile. Our analysis places the competitive environment in context using concentration metrics that indicate a market where leading players command meaningful share but do not exercise monopolistic control. This structure fosters both competition on technical performance and collaboration through toll-manufacturing and supply-chain partnerships.
Key Company Profiles and Strategic Roles
The report provides detailed company-level assessments of the principal participants shaping this market. Prefere Resins, headquartered in Germany, specializes in phenolic resins formulated for paper impregnation in industrial and decorative laminates, with a particular emphasis on kraft paper applications in high-pressure laminates where chemical resistance and machinability are critical. Metadynea Austria GmbH, based in Krems, produces phenolic resins used in kraft paper impregnation for laminates and wood composites, and has strengthened its sustainability positioning through certifications supporting bio-based raw material compliance. Bakelite, operating through its Hexion and Sumitomo Bakelite dimensions across the United States and Japan, supplies phenolic heat-reactive resins for saturating paper substrates including kraft paper, serving filtration, electrical, bearing, and gasket applications.
MÜNZING Chemie, located in Abstatt, Germany, complements the resin supply chain with additives that support phenolic resin-based industrial overlays and films for kraft paper in plywood and concrete forming applications, offering wetting agents and release agents that optimize PF resin impregnation. UCP Chemicals in Austria and Allnex Belgium both manufacture or offer phenolic resins targeted at kraft paper production for laminate and impregnation markets, reinforcing the European specialty-chemicals footprint. Capital Resin Corporation operates as a toll manufacturer in the United States, producing phenolic resins for industrial applications including paper impregnation and kraft paper composites. In Russia, PC Standart LLC produces phenolic paper consisting of specially impregnated kraft paper for plywood lamination and woodworking coatings, while Italy's Loma Srl manufactures LOMAPHEN-grade kraft papers impregnated with thermosetting phenolic resins for standard high-pressure laminates.
Recent Developments and Strategic Signals
The competitive dynamics are not static. Recent activity demonstrates how companies are adapting to shifting performance expectations and compliance requirements. In May 2025, Prefere Resins continued its supply of specialized phenolic impregnation resins for kraft paper in both high-pressure and low-pressure laminates, emphasizing improved surface characteristics and durability—an indication that surface quality and lifecycle performance are becoming differentiating factors. In December 2024, Metadynea Austria GmbH renewed its ISCC PLUS certificate for bio raw materials compliance, reinforcing its capability to supply sustainable phenolic resins for paper impregnation and signaling that bio-based feedstocks and certification-mediated market access are gaining strategic importance. In December 2025, MÜNZING Chemie referenced its FENTAK® additives portfolio for phenolic resin impregnation of core stock and industrial overlays on kraft paper-based films for plywood applications, illustrating how additive chemistry is being positioned to enhance process efficiency and end-product performance.
The full report expands these company profiles with competitive positioning analysis, supply-chain relationships, and an assessment of how each player's capabilities align with emerging application requirements. It also maps the implications of toll-manufacturing arrangements and regional production footprints for procurement flexibility and supply security.
Cost Structure, Raw Materials, and Pricing Realities
Any strategy for the phenolic resin for kraft paper production market must contend with the material cost foundation. Phenol accounts for approximately 50 to 60 percent of phenolic resin production costs, making phenol price volatility a direct determinant of resin economics for kraft paper impregnation. Pricing benchmarks from the third quarter of 2025 illustrate the geographic dispersion that manufacturers must manage: phenol-formaldehyde resin prices reached approximately USD 1,715 per metric ton in the United States, USD 1,370 per metric ton in China, and USD 1,695 per metric ton in Germany. This spread highlights the importance of regional sourcing strategies, logistics optimization, and hedging or contract structuring decisions that can materially affect margin outcomes.
The report integrates these raw-material dynamics into a broader cost-structure analysis that examines how resin producers and downstream converters respond to feedstock uncertainty. It considers the interplay between inventory management, regional procurement, and pricing pass-through mechanisms, providing a framework for evaluating cost resilience across different operating models. Rather than offering a static cost snapshot, the study constructs a decision-oriented view of how material-cost variability interacts with segment mix, regional positioning, and product-grade selection.
Phenolic Resin for Kraft Paper Production Market
Phenolic Resins Market
Regulatory Pressures and Compliance as Strategic Variables
Regulatory frameworks are increasingly shaping specification requirements and material choices in this market. In the United States, EPA TSCA Title VI formaldehyde emission standards govern composite wood products, and phenol-formaldehyde resins benefit from certain exemptions relative to urea-formaldehyde restrictions when used in hardboard and laminated products that meet threshold requirements ranging from 0.05 to 0.11 ppm depending on product type. For high-pressure laminates using phenolic-impregnated kraft paper, formaldehyde emission levels must typically remain below 0.05 ppm under E1 or equivalent classifications. These thresholds are not merely technical footnotes; they influence resin formulary decisions, process controls, and market access conditions, particularly for exporters and multinational laminate manufacturers.
The research places regulatory dynamics within the competitive and operational context, exploring how compliance requirements affect resin formulation priorities, certification pathways, and the relative attractiveness of different resin types and application channels. It also considers how sustainability certifications and bio-based feedstock credentials are becoming embedded in procurement criteria, extending the compliance conversation beyond emission thresholds to include lifecycle and sourcing considerations.
Forecast Outlook and Scenario-Based Planning for 2026–2032
The forecast window from 2026 to 2032 is the analytical centerpiece of the report. Building on the historical trajectory and current segment dynamics, the study projects revenue progression through 2032 and frames it within scenario-based considerations that help leadership teams stress-test their assumptions. Rather than presenting a single deterministic path, the report structures the outlook to accommodate variations in raw-material pricing, regional demand growth, regulatory adoption pace, and competitive intensity.
The forecast model reflects the market's 4.62 percent CAGR and incorporates the moderating influences of regional maturity and the accelerants of application-driven demand in construction, furniture, and industrial laminates. It also accounts for the potential impact of sustainability-driven substitutions, certification adoption, and shifts in the cost-of-ownership calculus as resin producers and converters adapt to material-cost volatility. By delivering this outlook within a structured analytical framework, the report enables readers to align their strategic planning with the most probable demand pathways while remaining prepared for alternative scenarios.
Report Contents and Operational Utility
This market research is designed as a decision-support tool rather than a general industry overview. It combines quantitative market sizing with qualitative competitive and operational analysis to provide a comprehensive view of the phenolic resin for kraft paper production landscape. The study includes:
- Detailed market size and forecast data spanning the historical period from 2020 to 2025 and the forecast window from 2026 to 2032, with revenue expressed in USD millions.
- Segment-level analysis by resin type, geographic region, and application, with interpretive commentary on the drivers behind each segment's performance.
- A competitive landscape assessment covering key companies, their headquarters and operational focus, and recent strategic developments that signal shifting priorities.
- Cost-structure and raw-material analysis that situates phenol price dynamics and regional pricing differentials within resin production economics.
- Regulatory and compliance context, including emission standards and sustainability certifications, mapped to their implications for resin selection and market access.
- Strategic recommendations and decision frameworks tailored for producers, converters, and downstream laminate manufacturers seeking to optimize positioning in a market characterized by moderate concentration and material-cost sensitivity.
The report is structured to allow readers to move quickly from macro trends to segment-specific insights and then to company-level intelligence, supporting both strategic planning and operational decision-making. By integrating quantitative data with interpretive analysis, it provides a foundation for evaluating investment priorities, procurement strategies, and competitive responses.
Why This Intelligence Matters for 2026 Decisions
As enterprises enter 2026, the phenolic resin for kraft paper production market presents a landscape in which growth is real but unevenly distributed, where raw-material volatility demands active cost management, and where regulatory and sustainability considerations are becoming embedded in specification and procurement decisions. In this environment, general market awareness is insufficient. What is needed is segment-aware intelligence that connects demand trajectories to resin types, regional supply conditions, competitive capabilities, and cost dynamics.
This report is built to supply that intelligence. It enables readers to identify where value is likely to concentrate over the forecast period, which application channels offer the strongest performance and margin potential, how regional dynamics influence sourcing and pricing strategy, and what competitive moves by key players mean for supply security and differentiation. By grounding the forecast in detailed segment and company analysis, it supports a range of decisions—from resin procurement and product formulation to capacity planning and market-entry evaluation.
The preview above outlines the scope and strategic logic of the research; the full study provides the underlying quantitative detail, segment-level breakdowns, and company-specific assessments that executives require to act with confidence. For organizations seeking to align their 2026 strategies with the realities of this market, the complete report offers the depth and precision necessary to convert insight into action.
For detailed analysis of this topic, please visit the official page: Phenolic Resin for Kraft Paper Production Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com