

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Broadband Network Market to Hit $626.26B by 2032, 4.8% CAGR

Strategic Intelligence for the Connected Decade: Inside the Worldwide Broadband Network Market Research
The global broadband network landscape is entering a defining phase. As digital infrastructure becomes the backbone of economic activity, the decisions made in 2026 will shape competitive positioning for the remainder of the decade. PW Consulting has just released our comprehensive Worldwide Broadband Network Market research, a strategic intelligence asset designed to cut through market noise and deliver actionable clarity for executives, investors, and policy stakeholders. Drawing on rigorous historical analysis and forward-looking modeling, this report equips decision-makers with the architectural understanding needed to navigate a market characterized by rapid technological shifts, intense consolidation, and evolving regulatory frameworks.
This introduction previews the strategic value embedded in the full study. It outlines the macro trajectory, the analytical framework, the competitive dynamics at play, and the operational realities reshaping deployment economics. The complete report contains detailed segmentation, granular forecasts, and proprietary competitive profiling that cannot be fully replicated in a summary. For organizations operating at the intersection of connectivity, infrastructure, and service delivery, this research is not optional context. It is foundational intelligence.
Worldwide Broadband Network Market
A Market Accelerating Toward Structural Maturity
Broadband networks have transitioned from utility-grade connectivity to mission-critical infrastructure. The trajectory of the worldwide broadband network market reflects this shift. From a base valuation of approximately 358.5 billion USD in 2020, the market expanded steadily through the mid-2020s, reaching an estimated 451.05 billion USD in 2025. Projections indicate continued expansion, with the market expected to surpass the 600 billion USD threshold by the early 2030s. This growth is not a simple continuation of historical momentum; it is driven by a compounding set of structural forces, including the proliferation of high-bandwidth applications, enterprise digital transformation, the rollout of next-generation access architectures, and the expanding footprint of fixed wireless and satellite alternatives in underserved geographies.
The forecast period from 2026 through 2032 is projected to deliver a compound annual growth rate of 4.8 percent. While the percentage itself signals steady expansion, the underlying narrative is more nuanced. Growth will be uneven across technology paths and demand segments, shaped by capital allocation efficiencies, labor and materials cost pressures, and the pace at which legacy infrastructure can be economically upgraded or replaced. The market is maturing, but maturity does not imply stagnation. It implies a shift in the battlefield, where advantages are won through deployment execution, ecosystem partnerships, and the ability to align technology roadmaps with end-user demand cycles.
What the Report Delivers: Operational Intelligence, Not Just Forecasts
Market research at the executive level must do more than chart historical curves and project endpoints. The PW Consulting study is built around operational utility. It maps the broadband ecosystem across the dimensions that matter most to strategic planning: technology pathways, end-user demand structures, and geographic deployment dynamics. Rather than treating the market as a monolith, the analysis isolates the segments that are driving capital expenditure, shaping vendor roadmaps, and influencing service provider investment priorities.
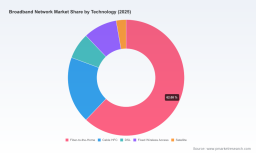
Readers will find a structured examination of the technology landscape, with focused attention on the access architectures that dominate current deployments and those gaining traction as operators optimize cost-per-passing and capacity targets. The report evaluates how fiber-centric architectures, hybrid coaxial systems, legacy copper-based services, fixed wireless access, and satellite solutions interact within the broader ecosystem, including where substitution, coexistence, and convergence are most likely to reshape investment flows.
In parallel, the study addresses demand-side segmentation across residential, commercial and enterprise, and government and public sector environments. Each segment carries distinct throughput expectations, latency requirements, procurement cycles, and regulatory considerations. By separating these demand profiles, the report helps stakeholders align product strategy, go-to-market planning, and partnership models with the segments that offer the most viable margin and scale opportunities in their target markets.
Wireless Broadband Market
The geographic dimension of the analysis reflects the reality that broadband deployment is fundamentally regional. Infrastructure economics, competitive intensity, policy incentives, and labor dynamics differ sharply by territory. The report breaks down the market across major regions and identifies the structural factors that determine where growth is most attainable and where execution risk is highest. This regional lens is essential for anyone evaluating market entry, capacity expansion, vendor selection, or capital deployment across multiple jurisdictions.
Competitive Architecture: Technology Leaders, Service Providers, and the Changing Frontier
The worldwide broadband network market is defined by a dense competitive structure that spans equipment manufacturers, optical and transport specialists, and large-scale service providers. The report provides a detailed competitive landscape assessment of the organizations setting the pace across access, aggregation, core transport, and end-user provisioning. These players are not competing in isolation. They are competing across integrated value chains, where hardware performance, software control, service orchestration, and deployment economics collectively determine market share.
At the equipment and infrastructure layer, the analysis examines firms that anchor broadband architecture across access and transport. Huawei Technologies Co., Ltd. and ZTE Corporation continue to scale end-to-end broadband solutions spanning fiber access platforms, PON systems, and supporting transport and wireless infrastructure for global operators. Nokia Corporation and Ericsson AB maintain strong positions in fixed broadband access, PON technology, IP routing, optical transport, and converged fixed and mobile broadband platforms. Cisco Systems, Inc. remains central to provider network routing, switching, cable access systems, and optical networking gear, while Ciena Corporation and ADTRAN Holdings, Inc. serve critical roles in high-capacity optical transport and fiber access platforms tailored to service provider requirements. CommScope Holding Company, Inc. and Corning Incorporated supply foundational connectivity materials and network components that underpin both fiber-to-the-home and hybrid fiber-coaxial rollouts. Juniper Networks, Inc. rounds out the infrastructure picture with high-performance routing, switching, and security capabilities for provider core and edge networks.
On the service provider side, the competitive dynamic is equally strategic. AT&T Inc., Verizon Communications Inc., and Comcast Corporation operate some of the most extensive consumer-facing broadband networks in the market, with aggressive fiber expansion and fixed wireless initiatives shaping demand-side expectations and competitive benchmarks. China Mobile Ltd. remains a decisive force in scale deployment, particularly as it continues massive fiber-to-the-home and fixed broadband initiatives. Deutsche Telekom AG represents a leading European model of converged fixed and mobile broadband strategy. Together, these operators illustrate how service providers are simultaneously competing for subscribers and consolidating infrastructure ownership to control long-term margin structures.
Market concentration data reinforces the strategic significance of this competitive set. The report notes a combined market share of approximately 38.4 percent among the top three players and 52.15 percent among the top five, reflecting an environment where scale, integrated capabilities, and ecosystem leverage matter more than ever. Yet concentration is not uniformity. The competitive frontier is being reshaped by partnerships, acquisitions, and infrastructure-sharing arrangements that blur traditional lines between vendor and operator, equipment and service, and national and regional strategies.
Recent Market Intelligence: Consolidation, Deployment Economics, and Policy Shifts
Strategic planning in broadband requires awareness of how recent moves are changing the operational ground. The report integrates a range of developments that reveal where capital, policy, and execution are converging. One of the most visible trends is the acceleration of fiber ownership and footprint expansion through partnerships and acquisitions. T-Mobile’s formation of strategic fiber joint ventures with Oak Hill Capital and Wren House, aimed at acquiring networks such as GoNetspeed and Greenlight Networks as well as i3 Broadband, signals a clear push to extend fiber reach into new households at speed. Similarly, AT&T’s agreement to acquire substantially all of Lumen’s Mass Markets fiber internet business for 5.75 billion USD reflects a deliberate strategy to consolidate consumer fiber assets and accelerate access to millions of additional locations. These moves are not isolated transactions. They represent a broader shift toward scale-based fiber positioning and infrastructure consolidation.
At the same time, deployment economics remain an operational priority. Recent industry reporting highlights that U.S. fiber build costs continue to vary by construction method, with median total deployment costs reaching levels that require careful site-level planning. Median underground fiber deployment costs and aerial deployment costs diverge enough to influence route design, permitting strategy, and make-ready execution. Labor cost structures also play a central role, with median labor expenses differing substantially between underground and aerial builds. Yet despite these cost pressures, industry expectations point to continued expansion. Fiber now passes a substantial majority of primary households in the United States, with total fiber-to-the-home passings approaching a milestone scale that underscores the technology’s transition from selective rollout to broad-based baseline infrastructure.
Cost expectations, however, remain a watch item. A significant majority of industry respondents anticipate that deployment costs will rise again during the forecast window, driven by labor, materials, permitting complexities, and make-ready requirements. This expectation is strategically important because it affects not only capital planning but also the attractiveness of alternative access technologies in specific environments. Policy frameworks further shape the deployment equation. Ongoing discussions around broadband programs, permitting, and infrastructure support for hyperscale data centers and AI-driven services indicate that broadband strategy is increasingly tied to the broader digital economy agenda. Recent industry policy forums have emphasized the need for frameworks that enable mission-critical applications, high-capacity backbones, and continued fiber expansion, reinforcing the idea that broadband infrastructure planning is now inseparable from long-term economic and technological development strategies.
Strategic Implications for 2026 Decision-Making
For executives and strategic planners, the broadband market research is designed to answer several questions that directly affect capital allocation, product strategy, and partnership decisions. First, it clarifies where growth is structurally supported versus where it is dependent on temporary tailwinds. Second, it identifies which technology pathways are gaining momentum in different demand environments and which are facing margin compression or substitution risk. Third, it helps decision-makers interpret how competitive consolidation and infrastructure acquisition activity will affect market access, pricing dynamics, and vendor negotiation leverage.
The study also supports scenario-based planning. Because deployment economics, policy incentives, and labor conditions can shift the attractiveness of different access strategies, the report provides the analytical scaffolding needed to evaluate multiple pathways rather than relying on a single forecast narrative. Organizations evaluating fiber expansion, fixed wireless deployment, hybrid network optimization, or enterprise service positioning can use the framework to determine where they can achieve scalable advantage and where localized execution will determine outcomes.
For investors and advisors, the report offers a structured view of how value is being created and captured across the broadband value chain. Understanding concentration patterns, end-user demand composition, and the divergence between access technologies helps clarify which business models are most resilient and which are most exposed to cost inflation or regulatory shifts. For operators, the intelligence supports more precise prioritization of capital projects, vendor selection, and partnership strategies in a market where speed to passing and quality of deployment execution increasingly separate winners from followers.
How to Use This Intelligence
The full PW Consulting Worldwide Broadband Network Market research is built for decision-makers who need depth, not just direction. It combines historical reconstruction with forecast modeling, segmentation analysis, competitive profiling, and deployment-context intelligence into a single strategic reference. Readers who rely on the complete report will be better positioned to:
- Align investment priorities with the segments and geographies that offer the strongest risk-adjusted growth
- Interpret competitive moves within a market where consolidation and partnerships are reshaping infrastructure ownership
- Evaluate technology pathways in the context of cost structures, demand profiles, and regional deployment realities
- Plan for policy and regulatory dynamics that influence permitting, program funding, and infrastructure support for high-demand applications
- Benchmark deployment economics and understand the cost factors that will shape expansion feasibility through the end of the decade
The preview above captures the strategic architecture of the study. The complete report delivers the segmented detail, competitive profiles, regional context, and forecast structure required to translate market understanding into executable decisions. For organizations preparing for 2026 and beyond, the broadband network market is not simply growing. It is reorganizing around new ownership models, new demand expectations, and new infrastructure imperatives. The organizations that navigate this transition most effectively will be those that base their decisions on rigorous, current, and deeply structured intelligence.
To access the full dataset, segmentation detail, competitive profiles, and forward-looking analysis, request the complete Worldwide Broadband Network Market research from PW Consulting. This intelligence is designed to support the decisions that define long-term positioning in one of the most strategically significant infrastructure markets of the decade.
For detailed analysis of this topic, please visit the official page: Worldwide Broadband Network Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com