

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
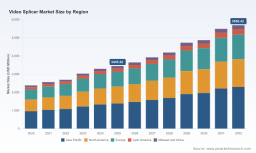
PW Consulting: Worldwide Video Splicer Market Hits $3,445.42M in 2025, Projected to Reach $5,686.42M by 2032

Strategic Imperatives in the Global Video Splicer Market: A 2026 Intelligence Brief
As enterprise display architectures, broadcast distribution networks, and command-center visualization infrastructures converge, the video splicer ecosystem has transitioned from a peripheral hardware category to a strategic integration layer. PW Consulting’s latest Worldwide Video Splicer Market research delivers a structured, operator-ready intelligence framework designed to help technology buyers, channel partners, and regional strategists navigate a market that is simultaneously maturing, fragmenting by deployment model, and accelerating through real-time processing demands. This brief outlines how the study translates market mechanics into actionable 2026 decision pathways without relying on backward-looking assumptions.
A Market Defined by Scale, Velocity, and Consolidation
The video splicer landscape has demonstrated consistent expansion across both consumer-adjacent visualization deployments and mission-critical control environments. Our historical reconstruction frames a trajectory that aligns with sustained capital allocation toward unified display management, low-latency signal routing, and adaptive content orchestration. The five-year historical window reveals a compounding growth pattern that extends confidently into the forward forecast horizon. Market value has advanced from a modest baseline into a substantially larger operating base, and the projected forecast period reflects a measured compound annual growth rate that supports credible investment modeling, capacity planning, and vendor engagement timelines.
That continuity matters strategically. Organizations evaluating display controllers, video processing matrices, or broadcast stream splicing infrastructure cannot treat near-term procurement as an isolated transaction. The market’s upward arc implies tightening lead times for advanced processing boards, increased demand for modular interoperability, and a broadening set of integration requirements across commercial display, enterprise education, and monitoring contexts. Our analysis anchors these implications in a coherent quantitative baseline, enabling leadership teams to stress-test scenario assumptions rather than extrapolate from isolated product announcements.
What the Study Delivers for 2026 Decision Cycles
The research is built as a workable operating manual, not a static sizing table. It moves systematically from macro validation to deployment-specific intelligence, ensuring that procurement leads, product planners, and regional distributors can locate the decision variables most relevant to their mandate. The report’s architecture is designed to close the gap between market narrative and execution.
Core Research Components
- A quantified market baseline with forward projections that distinguish between established demand pools and emerging growth vectors, helping teams separate structural expansion from short-cycle promotional activity.
- Technology-formulation analysis that maps processing approaches to real-world deployment tolerance, signal-path complexity, and maintenance expectations, so buyers can align architecture choices with facility constraints rather than vendor defaults.
- Application-coverage mapping across high-intensity visualization, commercial media presentation, broadcast signal management, and corporate or educational environments, clarifying where integration risk, support SLAs, and upgrade cadence differ most sharply.
- Competitive positioning coverage that identifies where incumbents concentrate capabilities, where new entrants can gain traction, and how product roadmaps are reshaping the value chain across regions and distribution channels.
- Market concentration diagnostics that quantify the balance between consolidated influence and fragmented opportunity, enabling partnership strategies to account for both scale advantages and niche differentiation.
Competitive Architecture: Where Capability Is Being Shaped
The competitive field in this market is not monolithic. It spans companies focused on fine-pitch LED control and modular processing, vendors emphasizing multi-screen matrices and plug-and-play signal handling, global visualization specialists concentrated on control-room continuity, and software-defined stream management providers targeting frame-accurate broadcast workflows. Understanding this distinction is essential because procurement cycles often conflate hardware processing maturity with software orchestration flexibility, even though the two address different failure modes and upgrade economics.
Leading Contributors and Strategic Profiles
- Hardware-led display control specialists continue to advance all-in-one splicing processors built for fine-pitch LED and large-format video walls. Their roadmaps typically emphasize modular expandability, image enhancement, and direct integration with display ecosystems, which matters for operators seeking reduced cabling complexity and centralized management.
- Video processor and matrix vendors provide multi-screen splicing architectures designed for both dynamic and static content workflows. Their strategic relevance lies in scalable routing, content distribution flexibility, and the ability to adapt splicing configurations without extensive infrastructure redesign.
- Multi-image processing providers focus on large LED video wall deployment, often pairing signal cards with broad third-party equipment compatibility. This approach reduces integrator friction in mixed environments and supports faster commissioning in commercial or event-based installations.
- Two-in-one and multi-channel splicer designs cater to high-load monitoring and full-color display applications, combining processing with operational oversight. These offerings appeal to facilities that want tighter visibility across channels while preserving expansion headroom.
- Professional signal processing manufacturers concentrate on seamless switching, scaling, and splicing across AV and LED display contexts. Their value proposition is reliable handoff between source formats and display targets, especially where configuration stability matters more than experimental feature sets.
- High-performance video wall controllers from established visualization firms remain critical for command environments and digital signage at scale. Their importance lies in consistent multi-display management and visualization continuity, particularly where uptime and configuration discipline are non-negotiable.
- Software-based transport stream splicing specialists address broadcast and media delivery with frame-accurate stream handling and metadata support. Their evolution points toward operational monitoring and flexible deployment models, reflecting a broader shift toward software-managed media pipelines.
Recent activity reinforces the direction of travel. In early 2026, one software-focused provider presented refreshed splicer releases alongside a monitoring dashboard intended to improve operational oversight across on-premises, cloud, and hybrid arrangements. Separately, a major fusion splicer manufacturer expanded service-partner certification, updated maintenance software, and supported technical skills competitions in China. While these events span adjacent segments, collectively they signal the same underlying dynamic: performance is increasingly defined not only by core processing power, but by service readiness, interoperability, and deployment flexibility.
Market Dynamics Reshaping Procurement and Deployment
Several external forces are altering how organizations evaluate video splicing investments. Regulatory and infrastructure developments are not abstract context; they directly affect deployment timelines, energy planning, network readiness, and the total cost of standing up large-scale visualization or data-intensive facilities.
Policy and Infrastructure Pressure Points
- Broadband regulatory interpretations have introduced uncertainty around how internet traffic management frameworks will evolve, which in turn influences downstream planning for content delivery, streaming workflows, and cloud-adjacent video processing architectures.
- Utility and energy regulations are increasingly tying large data center deployments to long-term power contracts and infrastructure cost responsibility. As hyperscale projects scale toward very large capital footprints, the cost of energy, transmission, and networking support becomes inseparable from the feasibility of adjacent digital signage, control-room, or media infrastructure expansion.
- Policy acceleration for qualifying large capital projects has shortened permitting pathways for high-voltage transmission and networking equipment in certain contexts, improving infrastructure readiness for facilities that rely on robust power and connectivity to support continuous video processing and display operations.
- Commitments from major hyperscale operators to absorb transmission and distribution costs without raising household rates illustrate the broader negotiation dynamic: large-scale digital infrastructure is increasingly expected to internalize externalities, which reshapes how adjacent vendors plan deployment economics and service engagements.
For video splicer buyers and integrators, these dynamics translate into practical caution. A display wall or broadcast splicing architecture may appear technically straightforward, yet its real viability often depends on facility power strategy, network provisioning, and the likelihood of future infrastructure upgrades. Decision-makers who ignore this context risk under-scoping installation complexity or over-committing to architectures that are sensitive to local utility and permitting timelines.
How to Use This Research for 2026 Strategy
This study is designed to support three distinct strategic functions. First, it gives procurement and technology teams a defensible baseline for budget planning, vendor benchmarking, and roadmap alignment. Second, it helps product and channel leaders identify where differentiation is achievable by technology form factor, application context, or regional readiness. Third, it equips senior leadership with enough structural clarity to decide whether to prioritize scale, specialize in a high-value segment, or reposition around service and integration capabilities.
The analysis treats segmentation and concentration as decision lenses rather than static facts. Understanding how processing approaches, application settings, and regional demand patterns interact allows organizations to forecast changeover cycles, anticipate support requirements, and choose between standardized deployments and customized integration. Concentration metrics further clarify whether the market rewards partnerships with established scale players or whether targeted niches still offer viable entry points.
Worldwide Video Splicer Market
Why the Full Intelligence Package Matters
A market brief can indicate direction, but operational decisions require the full architecture of the study: the quantification logic behind the forecast, the segmentation mapping that connects technologies to use cases, the competitive profiles that explain capability gaps, and the regulatory and infrastructure overlays that shape deployment risk. Those layers are where ambiguity gets resolved and procurement cycles become more resilient.
PW Consulting’s complete Worldwide Video Splicer Market research provides that depth. It links macro momentum to micro decisions, bridges hardware and software dynamics, and translates complex industry signals into a format usable by strategists, engineers, and commercial leaders alike. For organizations preparing 2026 investments, the report offers a structured path from market awareness to deployment confidence.
Optical Fiber Fusion Splicer Market
The full dataset, segmentation breakdowns, competitive analysis, and forward scenarios are available in the complete study. Reviewing the full report will allow decision-makers to validate assumptions against the underlying methodology, compare vendor profiles in detail, and build planning models that reflect both current demand and the structural changes already shaping the next forecasting cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Video Splicer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com