

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Independent Cart Tech Market Hits $938.5M in 2025, Projects 13.45% CAGR to 2032

Independent Cart Technology Market: Strategic Intelligence for 2026 Decision-Makers
The global manufacturing landscape is undergoing a quiet yet profound transformation. As factories face mounting pressure to increase throughput, reduce changeover times, and maintain uncompromising hygiene standards in regulated sectors, the limitations of traditional conveyor architectures have become impossible to ignore. Enter independent cart technology—a paradigm shift that replaces rigid mechanical linkages with electronically orchestrated, self-propelled carriers capable of dynamic positioning, simultaneous multi-directional movement, and rapid reconfiguration. For executives navigating capital allocation decisions in 2026, understanding the trajectory of this technology is no longer optional; it is a prerequisite for operational competitiveness. This article outlines the strategic context behind PW Consulting’s latest Worldwide Independent Cart Technology Market report, demonstrating why the full intelligence dossier represents an essential asset for forward-looking organizations.
A Market Built on Acceleration and Architectural Disruption
Over the past half-decade, independent cart technology has transitioned from a niche automation curiosity to a mainstream engineering solution. The global market, valued at $485.2 million in 2020, expanded consistently through each subsequent evaluation year, reaching $817.83 million by 2024 and crossing the nine-hundred-million threshold in 2025. Forecasts project sustained momentum through the end of the decade, with the market expected to approach $1.22 billion by 2027, surpass the $1.35 billion mark in 2028, and continue climbing toward $1.80 billion by 2030 before exceeding $2.26 billion in 2032. This expansion translates to a compound annual growth rate of 13.45 percent across the forecast horizon, a trajectory that outpaces broader industrial automation benchmarks and reflects deeper structural adoption across manufacturing footprints.
What drives this velocity? The answer lies in the physics and economics of the architecture itself. Traditional conveyance systems remain bound by fixed mechanical pathways, requiring physical reconfiguration for new product formats or line bottlenecks. Independent cart systems, by contrast, leverage permanent magnets mounted on individual carriers interacting with electromagnetic coils embedded in track arrays. This design eliminates gears, chains, and belts, dramatically reducing mechanical wear while enabling precise, uncoupled motion control. In targeted production segments, operators report movement speeds up to ten times faster than legacy conveyor configurations, with the added capability to pause, reroute, or accelerate individual units without halting the entire line. For facilities running high-mix, low-volume production schedules or managing stringent regulatory environments, these capabilities translate directly into reduced downtime, higher asset utilization, and more flexible capital deployment.
Architecture Blueprints and Application Channels
The report dissects the independent cart technology landscape across multiple structural and operational dimensions. Layout configurations reveal a clear divergence in application preferences. Linear track systems dominate deployment scenarios where straight-line throughput optimization is paramount, serving applications that require predictable sequencing and straightforward integration with existing upstream and downstream machinery. Planar surface systems cater to manufacturers demanding two-dimensional mobility, enabling carriers to approach workstations from multiple vectors and eliminating singular choke points that plague linear arrangements. Circular and closed-loop architectures address facilities seeking continuous flow with minimal dead zones, often proving highly effective in high-volume batch processing environments where balanced throughput and spatial efficiency are non-negotiable.
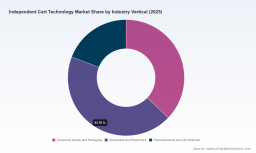
Industry vertical adoption patterns reflect corresponding priorities. Consumer goods and packaging operations prioritize rapid format changeovers, high-speed sequencing, and washdown-ready engineering that withstands aggressive cleaning protocols. Automotive and electronics manufacturers emphasize precision positioning, synchronized multi-cart coordination, and the ability to handle varied payload profiles across complex assembly workflows. Pharmaceutical and life sciences facilities demand stringent environmental isolation, validated cleaning cycles, and material handling integrity that aligns with health authority compliance frameworks. Each vertical leverages independent cart architectures differently, but all converge on a shared strategic objective: decoupling product flow from rigid mechanical constraints to unlock responsive, scalable production operations.
PW Consulting’s research goes beyond surface-level categorization. The full dossier maps deployment logic across regional manufacturing hubs, compares engineering trade-offs between competing track configurations, and evaluates total cost of ownership models that factor in maintenance intervals, energy consumption profiles, integration complexity, and lifecycle scalability. For engineering directors and operations executives, these analytical layers provide a structured framework for internal technical evaluations, vendor shortlisting, and capital approval narratives.
Competitive Architecture: How Leading Providers Are Shaping the Field
The independent cart technology market exhibits pronounced vendor concentration, with the top three participants accounting for approximately sixty-five percent of total revenue, while the top five collectively command over seventy-eight percent. This consolidation reflects the capital intensity of the technology stack, the engineering complexity of precision electromagnetic control systems, and the long-term service relationships that OEMs build with industrial end-users. Three companies stand at the forefront of this competitive arena, each pursuing distinct architectural philosophies and market positioning strategies.
- Rockwell Automation, headquartered in Milwaukee, Wisconsin, maintains the broadest commercial portfolio in this category. Its iTRAK Intelligent Track Systems, MagneMover LITE Intelligent Conveyor, and QuickStick Intelligent Conveyor platforms utilize electromagnetic propulsion to deliver flexible, high-speed motion control tailored for manufacturing and packaging environments. Product literature emphasizes environmental hardening, with motors and cart assemblies rated IP65 or higher to support rigorous washdown protocols and harsh operating conditions in food, beverage, and pharmaceutical settings. Integration capabilities further extend the value proposition, as systems synchronize with industrial Ethernet protocols such as EtherNet/IP to enable coordinated multi-cart motion control and embedded safety functions.
- Bosch Rexroth, based in Lohr am Main, Germany, pursues a magnetic levitation centric engineering approach with its High-Speed Smart Conveyance portfolio. The ctrlX Flow 6D platform delivers six degrees of freedom through contact-free magnetic actuation, enabling precise positioning and dynamic transport across assembly, packaging, and high-performance use cases. The ctrlX Flow HS variant complements this range for applications requiring controlled contact-free conveyance with streamlined mechanical footprints. Recent market activity underscores the pace of refinement: in mid-2025, the company enhanced packaging line throughput demonstrations by leveraging the ctrlX Flow 6D configuration for contact-free smart conveyance, while separate showcases highlighted permanent magnet motor integration that improved flexibility in high-speed motion control scenarios. Earlier in the year, trade exhibition appearances illustrated transfer system payloads scaling from three to four hundred kilograms, signaling expanding capacity envelopes.
- Beckhoff Automation, located in Verl, Germany, anchors its independent cart strategy around dual-platform differentiation. The eXtended Transport System merges linear and rotary transport principles to address applications requiring coordinated sequencing and directional versatility. Its XPlanar architecture introduces planar independent mover technology, allowing carriers to move freely across a surface without fixed track orientation, dramatically expanding layout flexibility for complex workspace geometries. Engineering teams integrating Beckhoff solutions often prioritize native compatibility with the broader TwinCAT automation ecosystem, streamlining software-driven motion orchestration and diagnostics.
The competitive narrative extends beyond product specifications. Each provider is actively expanding system boundaries, refining control architectures, and deepening integration pathways that connect independent cart platforms to broader factory-to-enterprise data flows. The full report captures these strategic movements, evaluates recent product enhancements, and assesses how corporate roadmaps may influence procurement timing, compatibility planning, and vendor negotiation leverage over the coming investment cycle.
Regulatory, Standardization, and Engineering Dynamics Influencing Adoption
Market expansion does not occur in a vacuum. Several operational and compliance forces are actively shaping deployment velocity. Washdown and environmental resilience requirements remain central for food and beverage processing, pharmaceutical manufacturing, and certain chemical handling operations. Independent cart systems engineered with IP65-rated enclosures and sealed coil assemblies address these demands more elegantly than legacy belt-driven alternatives that degrade under aggressive sanitation cycles. Standardization efforts around industrial networking protocols further accelerate integration feasibility. The ability to synchronize multiple carts using established Ethernet-based control frameworks reduces the learning curve for control engineers, enables unified safety architecture, and aligns deployment planning with existing plant infrastructure rather than demanding wholesale system replacement.
Worldwide Independent Cart Technology Market
Metabolic Cart Market
From a materials and mechanical perspective, the shift away from gears, chains, and belts toward permanent magnet and electromagnetic coil interaction reduces consumable replacement cycles and simplifies mechanical maintenance planning. This architectural simplification carries downstream implications for spare parts inventories, service contracts, and factory floor ergonomics. Meanwhile, the capacity to vary cart speeds independently and reposition units on demand introduces granular throughput modulation that traditional conveyors cannot replicate. Factories managing multiple SKUs with different processing dwell times can now route individual carriers to appropriate workstations without fixed-speed bottlenecks, improving line balancing and reducing idle cycles across mixed-model production runs.
PW Consulting’s comprehensive study evaluates these dynamics within the context of purchasing decision timelines, lifecycle cost modeling, and regulatory compliance planning. The complete dossier also examines regional implementation maturity, infrastructure requirements for new installations, and comparative engineering trade-offs that procurement and plant engineering teams routinely weigh during capital project scoping.
Strategic Implications for 2026 Investment Cycles
Organizations evaluating independent cart technology in 2026 face a converging set of strategic questions. Should procurement timelines align with immediate throughput targets, or should investments be phased to accommodate broader Industry 4.0 integration roadmaps? How do vendors’ differing control architectures affect internal engineering capacity, training requirements, and long-term service partnerships? Will certain layout types prove more resilient to future product portfolio shifts, or does hybrid configuration adoption deliver superior operational flexibility over time? The full market intelligence report addresses these considerations with structured scenario comparisons, vendor alignment matrices, growth trajectory projections, and expenditure planning guidance calibrated for manufacturing and automation decision-makers.
Capital allocation in the automation sector increasingly rewards early clarity. Early visibility into market concentration trends, architecture evolution cycles, and competitive product roadmaps enables teams to anticipate pricing dynamics, negotiate more effectively, and design facility layouts that accommodate technology evolution without costly rework. Conversely, delayed assessment carries compounding risk: accelerating adoption curves, tightening vendor capacity, and shifting integration standards can compress planning windows and raise implementation costs over time. The forecast period extending to 2032 provides a sufficiently long horizon to model multiple investment scenarios, stress-test expansion assumptions, and align technology procurement with broader operational strategy milestones.
Unlocking the Complete Intelligence Dossier
The executive summary presented here offers a structural preview of the forces reshaping the independent cart technology market. It reflects the analytical rigor applied across historical performance evaluation, architectural segmentation, competitive mapping, and forward-looking trend assessment. However, the complete research repository delivers substantially greater operational utility. Decision-makers will find detailed valuation frameworks, application-specific deployment considerations, integration pathway analyses, competitive positioning narratives, and multi-period forecast tables designed to support presentation-ready business cases and internal investment approvals. The full study also explores procurement timing dynamics, vendor capacity outlooks, and engineering integration pathways that directly influence purchasing strategies across consumer goods, automotive and electronics, pharmaceutical and life sciences, and adjacent industrial verticals.
To access the complete Worldwide Independent Cart Technology Market research, including granular scenario modeling, layout-type trade-off evaluations, regional deployment logic, and strategic procurement guidance calibrated for 2026–2032 planning cycles, request the full report through the source platform. Organizations that secure this intelligence early position themselves to make informed technology investments, negotiate from a position of structural clarity, and align automation strategy with the accelerating evolution of independent cart architectures.
For detailed analysis of this topic, please visit the official page: Worldwide Independent Cart Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com