

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global 6PPD Market to Hit $1.29B by 2032, Driven by Asia Pacific's 55% Share

Navigating the 6PPD Market: Strategic Intelligence for 2026 and Beyond
As the global rubber chemicals industry stands at a critical intersection of performance demand and environmental scrutiny, the need for precise, forward-looking market intelligence has never been more acute. The 6PPD market—a cornerstone of tire manufacturing and industrial rubber applications—continues to evolve under the weight of regulatory shifts, technological alternatives, and regional manufacturing dynamics. Our latest comprehensive study on the 6PPD market delivers the analytical depth required for executives, procurement leaders, and strategy teams to navigate the 2026–2032 horizon with confidence.
This research is not merely a retrospective of historical trends. It is a decision-ready framework that maps revenue trajectories, concentration patterns, competitive positioning, and the regulatory fault lines that will shape sourcing strategies, capital allocation, and product development priorities over the next decade. For organizations that depend on antiozonants and antioxidants in rubber compounding, the insights contained in this report offer a structured path from uncertainty to informed action.
Market Scale, Growth Trajectory, and Structural Signals
The 6PPD market has demonstrated steady expansion over the past half-decade, reflecting the indispensable role of this antioxidant in preserving rubber durability, extending service life, and meeting rigorous safety and performance standards. The global market reached a base value of approximately 1,022.04 million USD in 2025, building on a historical trajectory that saw the market grow from 825.4 million USD in 2020 through a series of steady annual increments. This expansion underscores the entrenched position of 6PPD across tire production and industrial rubber goods, even as market participants contend with supply chain recalibration and regional demand variations.
p-Phenylenediamine (PPD) Market
Looking ahead, the forecast period from 2026 to 2032 projects a measured but consistent upward path, with the market anticipated to reach 1,291.57 million USD by 2032. The compound annual growth rate across the full forecast window stands at 3.4 percent, a figure that captures the balance between sustained end-use demand in automotive tires and the moderating influences of substitution pressures, regulatory adaptation, and regional shifts in manufacturing capacity. This growth profile is not uniform across the horizon; it reflects a market that is maturing in certain segments while opening new strategic questions in others. Executives navigating this landscape require more than top-line numbers—they need to understand where volume concentrates, how pricing power is distributed, and which structural forces will accelerate or constrain expansion in specific timeframes.
The market’s concentration characteristics further illuminate the competitive architecture. With the top three players accounting for roughly 42.5 percent of revenue and the top five capturing approximately 61.8 percent, the landscape exhibits meaningful consolidation without the dominance of a single monopolistic force. This distribution has direct implications for sourcing leverage, supply security, and the negotiating dynamics between tire manufacturers, compounders, and chemical producers. Understanding how this concentration interacts with regional production footprints and application-level demand is essential for building resilient procurement and partnership strategies.
The 2026 Decision Environment: Why This Research Matters Now
The year 2026 represents a pivotal inflection point for organizations operating in or adjacent to the 6PPD value chain. Several converging forces make this moment particularly consequential. First, tire manufacturers and industrial rubber producers are simultaneously managing cost pressures, feedstock variability, and the imperative to maintain compliance with evolving product safety and environmental standards. Second, regulatory bodies in key markets are advancing frameworks that scrutinize not only the active chemical but also its transformation products, creating a compliance environment that demands proactive scenario planning rather than reactive adjustment. Third, the competitive field includes a mix of established global specialty chemical firms, regional producers with significant capacity, and innovators exploring alternative chemistries that could reshape demand patterns over the medium term.
In this context, strategic decisions made in 2026—whether regarding supplier diversification, inventory planning, R&D investment in alternative formulations, or regional sourcing pivots—will have multi-year consequences. A market research study that isolates historical data without connecting it to decision logic offers limited utility. By contrast, an analysis that ties market size evolution, concentration metrics, and competitive moves to operational implications enables leadership teams to stress-test assumptions, identify exposure points, and prioritize interventions that protect both margin and supply continuity.
Our report is structured to serve precisely this function. It treats the 6PPD market not as a static commodity space but as a dynamic system shaped by performance requirements, regulatory timelines, manufacturing geography, and the strategic behavior of key participants. The result is an intelligence asset that supports procurement negotiation, risk assessment, capacity planning, and long-range strategic positioning.
Inside the Report: Actionable Scope and Analytical Coverage
The study provides a multi-dimensional examination of the 6PPD market, combining quantitative foundation with qualitative assessment to produce a usable playbook for decision-makers. The analytical architecture is designed to answer the questions that matter most to commercial and operational leadership.
- Historical and Forecast Revenue Analysis: The report traces the market’s evolution from 2020 through the base year of 2025 and extends the projection arc across the 2026–2032 forecast period. This longitudinal view enables readers to distinguish cyclical fluctuations from structural shifts, assess the durability of growth signals, and anchor planning assumptions in a consistent dataset expressed in million USD.
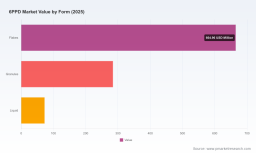
- Form and Application Segmentation: The market is examined across its principal physical forms and end-use applications, allowing readers to understand where demand is most concentrated and how different product configurations align with downstream manufacturing requirements. This structure supports more precise procurement targeting and helps identify which product formats carry the greatest strategic weight in specific customer environments.
- Regional Market Distribution: Geographic breakdowns illuminate the spatial distribution of revenue and the relative weight of key regions in the global supply-demand balance. Understanding these regional contours is essential for evaluating logistics exposure, currency and trade dynamics, and the localization strategies of both suppliers and buyers.
- Competitive Landscape and Player Profiling: The report profiles the leading organizations that define the market’s structure, examining their production focus, geographic anchors, and strategic orientations. By mapping the capabilities and positioning of major manufacturers, the study provides context for supplier evaluation, partnership assessment, and competitive benchmarking.
- Regulatory and Environmental Dynamics: A dedicated analysis addresses the regulatory environment surrounding 6PPD and its transformation products, including product designation frameworks, alternatives analysis requirements, and proposed legislative timelines. This section translates compliance developments into strategic implications, helping organizations anticipate adjustment costs, timeline pressures, and the potential impact of substitution trajectories.
- Strategic Implications and Decision Frameworks: Beyond description, the study integrates findings into actionable guidance for sourcing strategy, risk mitigation, and forward-looking investment. The objective is to equip readers with a structured lens for evaluating trade-offs between cost efficiency, supply resilience, and regulatory preparedness.
Competitive Landscape: Concentration, Capability, and Strategic Positioning
The 6PPD market is shaped by a diverse set of participants whose capabilities span integrated specialty chemical operations, regional production hubs, and focused suppliers serving tire and industrial rubber customers. The presence of both globally established firms and regionally anchored producers creates a competitive environment where scale, cost position, technical service, and regulatory readiness all influence market share and customer preference.
Several global and regional organizations anchor the market’s supply structure. Sennics operates as a leading global manufacturer of 6PPD with significant production capacity oriented toward rubber antidegradants for tires and industrial rubber products. Flexsys, with its established position in rubber chemicals and its Santoflex 6PPD pastilles, supplies the antioxidant and antiozonant needs of tire and rubber goods manufacturers while actively developing alternative chemistries. LANXESS contributes through vertically integrated operations that serve the tire and polymer industries, reinforcing a model in which specialty chemical expertise is paired with broad downstream relationships. China Sunsine Chemical Holdings functions as a key Asian producer, offering cost-effective grades to tire manufacturers and reinforcing the importance of regional supply hubs in the global balance. KKPC extends the competitive field through its rubber chemicals portfolio, supporting both synthetic and natural rubber applications in tire production. Sinopec Nanjing Chemical Industries adds state-backed production capacity aimed at tire and technical goods manufacturing, while Duslo provides European manufacturing capability for 6PPD and related PPD-based antioxidants. Shandong Stair Chemical Technology and Shandong Kaiyue Chemical Co., Ltd. represent specialized Chinese supply channels for tire and general rubber compounding, and NOCIL brings an Indian production base serving domestic and export tire markets. Kawaguchi Chemical Industry contributes Japanese manufacturing depth for high-performance rubber applications, and YUSHENG supplies antioxidant 6PPD grades compatible with a wide range of synthetic and natural rubber systems in tire production.
This competitive fabric matters because it determines where pricing pressure originates, how supply disruptions propagate, and which suppliers can offer the technical and compliance support that modern tire and rubber manufacturers require. The report examines these participants not as isolated corporate profiles but as components of a market system in which capacity additions, regional cost advantages, and innovation agendas interact to shape buyer options and negotiating dynamics.
Regulatory and Environmental Forces Reshaping the Trajectory
No analysis of the 6PPD market in the current cycle is complete without a serious engagement with the regulatory environment. The market is being influenced by a series of actions and developments that alter the risk calculus for manufacturers, compounders, and end users alike.
In California, the Department of Toxic Substances Control began regulating motor vehicle tires containing 6PPD as a Priority Product under Safer Consumer Products regulations starting October 1, 2023. This designation requires manufacturers to conduct alternatives analysis, introducing a formal compliance pathway that has prompted significant industry activity. The U.S. Tire Manufacturers Association 6PPD Consortium, representing a substantial share of the California tire market, submitted yearly progress reports on Stage 1 alternatives analysis, including ongoing ozone resistance testing, and received notice of compliance for its preliminary alternatives analysis report in August 2024. These steps reflect an industry-wide effort to balance performance requirements with environmental accountability.
At the federal level, the U.S. EPA issued an Advance Notice of Proposed Rulemaking under TSCA Section 6 in November 2024, with a comment period extended into March 2025, to gather information on the risks of 6PPD and 6PPD-quinone following a tribal petition. This action signals a widening regulatory aperture and introduces additional uncertainty for organizations that must anticipate possible future restrictions or use conditions. Meanwhile, Washington state legislation proposes prohibiting the manufacture, sale, and distribution of new vehicle tires containing 6PPD or regrettable substitutes beginning January 1, 2035, with a mitigation fee starting in 2027. These regional initiatives, while not globally synchronized, create a patchwork of requirements that complicates multi-market sourcing and product standardization strategies.
These regulatory dynamics interact with a core technical reality: 6PPD is used as the primary antiozonant in the full range of passenger, light truck, truck/bus radial, and motorcycle tires produced by USTMA members to ensure compliance with Federal Motor Vehicle Safety Standards and performance requirements. At the same time, the compound is not banned globally, but it faces increasing scrutiny due to its transformation product, 6PPD-quinone, which is highly toxic to certain salmonid species. Tire manufacturers are therefore actively evaluating alternatives while maintaining tire safety, and the industry is watching the emergence of successor chemistries closely.
Flexsys, for example, announced in November 2025 the development of a viable alternative to 6PPD using substantially the same intermediate chemistry, with extensive testing indicating it meets performance and environmental requirements without toxic quinone by-products. Developments of this kind matter because they illustrate how the market may evolve not through abrupt replacement but through phased qualification, testing, and adoption cycles that unfold over multiple years. For organizations planning around 2026 and beyond, the strategic question is not whether alternatives will emerge, but how quickly they will clear performance and regulatory thresholds, and what that means for existing supply commitments and formulation roadmaps.
Using This Intelligence: From Insight to Execution
The value of this report lies in its ability to convert complex market signals into executable insight. For procurement and supply chain leaders, the study supports supplier evaluation by clarifying concentration patterns, regional supply distributions, and the strategic postures of key producers. For R&D and product development teams, it frames the timeline and stakes of alternatives qualification, helping organizations sequence their own formulation work in alignment with likely regulatory and market milestones. For executive planning functions, the forecast trajectory and concentration metrics provide a basis for scenario modeling, capital prioritization, and risk provisioning.
6PPD Market
The report is designed to be referenced, not merely read. Its segmentation structure, competitive mapping, and regulatory synthesis give teams a common evidentiary foundation for cross-functional discussion. Whether the objective is to renegotiate supply terms, assess exposure to regional regulatory shifts, evaluate the resilience of a sourcing portfolio, or prepare for the possibility of accelerated substitution in specific applications, the analysis offers a structured starting point that reduces reliance on fragmented secondary information.
Access the Full 6PPD Market Research
This article provides a strategic preview of the market environment and the analytical perspective contained in our full study. It is intended to demonstrate the depth and decision relevance of the research while preserving the detailed segmentation data, regional and application-level breakdowns, and granular competitive assessments that enterprise subscribers require for operational planning.
Organizations that rely on 6PPD for tire manufacturing, conveyor belts and hoses, industrial rubber components, or broader rubber compounding applications will find that the complete report delivers the specificity needed to translate market dynamics into procurement strategy, compliance planning, and long-range positioning. The full dataset, extended profiles, and scenario-oriented interpretive sections are available through the source page, where readers can access the complete market research and integrate its findings into their 2026 decision cycles.
In a market defined by steady growth, meaningful concentration, and an accelerating regulatory and innovation agenda, the difference between reactive adaptation and proactive strategy is information quality. This report is built to provide exactly that—structured, current, and oriented toward the decisions that will shape performance through 2032.
For detailed analysis of this topic, please visit the official page: 6PPD Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com