

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Auto Fender Market toHit 5.12% CAGR 2026-2032

Strategic Horizons in the Global Auto Fender Market: A 2026 Decision-Maker's Guide
The global automotive industry stands at a critical inflection point, where every component's weight, cost, and carbon footprint influences a manufacturer's competitive standing. Among these components, the auto fender has evolved from a simple protective panel into a complex engineering element integral to vehicle aerodynamics, safety, and sustainability profiles. As we navigate the forecast period extending through 2032, understanding the trajectory of the Worldwide Auto Fender Market is not merely an exercise in inventory planning but a strategic imperative for stakeholders across the value chain. This article serves as a primer to our latest comprehensive market research, designed to equip executives with the high-level intelligence needed to navigate the complexities of 2026 and beyond.
Market Trajectory and Growth Dynamics
The macroeconomic indicators for the auto fender sector reveal a story of steady resilience amidst technological disruption. Drawing from historical data spanning 2020 to 2025, the market has demonstrated consistent upward momentum, recovering from early pandemic-induced fluctuations to establish a robust baseline. In 2025, the total market revenue reached approximately 10,857.14 million USD, reflecting the enduring demand for both original equipment manufacturer (OEM) supplies and aftermarket replacements.
Our forecast model projects this growth to continue through 2032, with the market valuation anticipated to climb toward 15,400.03 million USD by the end of the period. This expansion is underpinned by a compound annual growth rate (CAGR) of 5.12 percent. While this growth rate may appear moderate compared to high-tech sectors, it represents significant capital flow in a mature manufacturing segment, driven by increasing vehicle production volumes in emerging economies and the continuous replacement needs of aging global fleets.
It is crucial for decision-makers to recognize that this growth is not uniform. The interplay between material costs, regulatory pressures, and vehicle type shifts creates distinct pockets of opportunity. While the aggregate numbers provide a health check of the industry, the real strategic value lies in understanding the velocity and direction of these shifts. For instance, the transition toward electric vehicles (EVs) is altering the composition of demand, favoring materials that optimize range efficiency over traditional heavy steel solutions. Our research delves into these nuances, offering a granular view of how different market segments are expected to perform relative to the overall CAGR.
Material Shifts and Regulatory Pressures
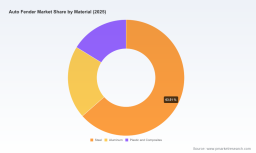
The composition of the auto fender market is undergoing a fundamental transformation driven by the dual engines of lightweighting and sustainability. Historically, steel has dominated the material landscape, accounting for a significant portion of market revenue due to its durability and cost-effectiveness in mass production. However, the industry context is shifting. Global demand for automotive composites, including those used in fenders, reached a record 4.9 billion pounds in 2024, according to industry data. This surge is directly linked to the aggressive lightweighting needs of modern vehicle architectures.
Aluminum and plastic composites are gaining traction, particularly in passenger cars where aerodynamic performance and weight reduction are paramount. The shift is not solely technical; it is heavily influenced by regulatory frameworks. European OEMs are now required to include product carbon footprint data with supplier quotations for components such as fenders. With full compliance frameworks advancing toward 2025 net-zero targets, suppliers must provide transparent environmental data to remain viable partners for major automakers. This regulatory pressure is accelerating the adoption of thermoplastic polymers and composite fenders, which offer distinct advantages in recycling and manufacturing emissions compared to traditional stamped metal.
Fender Flare Trim Market
However, this transition introduces volatility. Prices for composite resins, fibers, steel, and aluminum remain susceptible to global commodity fluctuations and supply chain disruptions. For procurement managers and strategic planners, navigating this volatility is a key challenge. Understanding which material segments offer the best balance of cost stability and performance compliance is essential for maintaining margins in 2026.
Competitive Landscape and Key Players
The market structure is characterized by a moderately fragmented landscape where regional specialists and global Tier 1 suppliers coexist. Our analysis indicates a competitive environment where consolidation and technological specialization are key differentiators. The top three companies hold a combined market share of 18.45 percent, while the top five account for 26.12 percent. This concentration suggests that while large players dominate significant volumes, there is substantial room for niche innovators and regional leaders to capture value through specific technical capabilities or geographic strength.
Several key companies define the current competitive boundaries. Magna International Inc., headquartered in Aurora, Ontario, remains a dominant force as a global Tier 1 supplier. Their focus on lightweight composite, steel, and aluminum fenders with advanced integration for OEMs underscores the industry-wide priority on durability and weight reduction. Similarly, Plastic Omnium SE in France has carved a specialized niche in plastic and composite automotive exterior components. Their emphasis on sustainability and design flexibility aligns closely with the aerodynamic and environmental demands of modern passenger vehicles.
Worldwide Auto Fender Market
North American manufacturing remains robust with players like Flex-N-Gate Corporation and Martinrea International Inc. Flex-N-Gate supplies stamped steel, aluminum, and composite fenders to global OEMs, leveraging its scale and integration capabilities. Martinrea focuses heavily on aluminum and steel lightweight body structures, catering to the specific requirements of North American and European OEMs. In Europe, Faurecia, now operating as FORVIA, supplies eco-friendly and customizable fender solutions, while Gestamp Automoción S.A. provides stamped metal fenders using advanced high-strength steel and aluminum for weight optimization. Thyssenkrupp AG also contributes through its steel and components divisions, supplying high-strength steel solutions critical for structural integrity.
The Asian market is represented by formidable entities such as Hyundai Mobis Co., Ltd. in South Korea, which offers modular fender systems for Hyundai/Kia and global platforms, and Japanese suppliers like Futaba Industrial Co., Ltd., Toyota Boshoku Corporation, and Aisin Corporation. These Japanese firms emphasize precision manufacturing and material innovation, often supplying major Asian and global automakers with integrated lightweight designs. The presence of these diverse players highlights the global nature of the supply chain, where regional strengths in manufacturing efficiency, material science, and OEM relationships dictate competitive positioning.
Strategic Implications for 2026 and Beyond
For business leaders preparing for the 2026 fiscal year, the insights from this market research translate into several actionable strategic avenues. First, supply chain resilience must be prioritized against the backdrop of raw material volatility. The impact of US tariffs on steel and aluminum raw materials continues to affect manufacturing costs for sheet metal fenders. While certain outer closure components may have specific treatment under Section 232 and reciprocal tariffs, the overall cost pressure remains a critical factor in pricing strategies and sourcing decisions.
Second, product development roadmaps must align with the electrification trend. The shift to electric vehicles accelerates the adoption of materials that optimize aerodynamics and range efficiency. Suppliers who can offer fender modules that integrate lighting and sensing technologies, such as those explored by Valeo SA, may find new value propositions beyond traditional protection. The ability to provide modular systems that fit diverse EV platforms will be a key differentiator in the OEM channel, which continues to hold the largest revenue share compared to the aftermarket.
Third, regulatory compliance is becoming a competitive moat. As carbon footprint data becomes a standard requirement in supplier quotations, companies with robust sustainability tracking and low-emission manufacturing processes will secure preferential partnerships with European and increasingly global OEMs. This is not just about avoiding penalties but about winning contracts in a carbon-constrained market.
Finally, regional strategy requires calibration. While Asia Pacific remains a significant volume driver, growth expectations vary across North America, Europe, and Latin America due to differing regulatory environments and vehicle mix preferences. A one-size-fits-all approach to market entry or expansion is unlikely to yield optimal results. Decision-makers need to understand the specific demand drivers in each geography, from the dominance of passenger cars in certain regions to the specific needs of light and heavy commercial vehicles in others.
Conclusion
The Worldwide Auto Fender Market is far more than a commodity segment; it is a barometer for broader automotive trends including electrification, sustainability, and supply chain complexity. The projected growth to 15,400.03 million USD by 2032 offers a substantial opportunity, but capturing this value requires precision intelligence. Understanding the specific growth vectors, material shifts, and competitive maneuvers detailed in our full report is essential for crafting a winning strategy in 2026. This overview provides the strategic framing, but the detailed segmentation, pricing dynamics, and specific regional forecasts contained in the complete study are necessary for operational execution.
For detailed analysis of this topic, please visit the official page: Worldwide Auto Fender Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com