

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Spark Testing Machines Market to Hit $616.92M by 2032

Strategic Intelligence for 2026: Inside the Worldwide Spark Testing Machines Market
In the rapidly evolving landscape of industrial quality assurance, the spark testing machines market stands at a critical intersection of safety regulation, manufacturing expansion, and technological precision. As organizations commit capital to production lines and infrastructure projects throughout 2026, understanding the trajectory of insulation testing equipment is no longer optional. PW Consulting's latest deep-dive analysis into the Worldwide Spark Testing Machines Market provides executive leadership, procurement strategists, and industry investors with the structural intelligence needed to navigate a market undergoing steady consolidation and capability-driven growth.
This article serves as a strategic preview of the full research report. It highlights the macroeconomic contours, competitive pressures, and operational dynamics that will define purchasing and partnership decisions in the coming years. While select high-level figures are shared here to establish market context, the complete segmentation logic, regional breakdowns, and granular forecasts remain embedded in the full publication. The objective is straightforward: equip decision-makers with enough analytical depth to recognize the stakes, while preserving the precise data architectures that deliver a tangible return on research investment.
The Macro Trajectory: A Market Built on Consistency and Quality Mandates
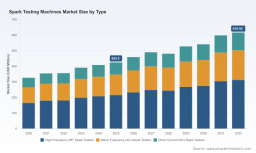
From a foundational perspective, the global spark testing machines market has demonstrated resilient expansion across the historical review period, moving from a baseline measured in 2020 through sustained annual growth to a current valuation established in 2025. The report's forward-looking framework extends through 2032, capturing a compound annual growth rate of 5.45 percent across the forecast window. This trajectory is not merely a function of incremental demand; it reflects the structural role that spark testing plays in safeguarding electrical integrity across power distribution, automotive assembly, telecommunications infrastructure, and construction-grade wiring.
By 2026, the market's revenue scale signals a mature but still-growing ecosystem. Growth is being shaped by three reinforcing forces. First, continued expansion in global wire and cable manufacturing raises the baseline requirement for inline and post-production insulation verification. Second, infrastructure investment cycles across multiple economies are extending the footprint of cable-dependent projects, increasing total inspection volume. Third, stricter safety and quality regulations in electrical applications are reinforcing the necessity of reliable pinhole and fault detection, embedding spark testing more deeply into standard operating procedures rather than treating it as an optional quality check.
What makes this growth pattern strategically significant for 2026 decision-making is its consistency. Markets that expand at a measured pace often conceal meaningful shifts in subsegment performance, buyer preferences, and technology adoption. A surface-level read can obscure where competitive advantage will be won or lost. The full report isolates these layers, allowing organizations to align procurement timing, capacity planning, and vendor evaluation with the actual shape of demand rather than its headline direction.
The Report's Operational Architecture: What Decision-Makers Gain
A market study earns its place in a strategic workflow only when it translates into actionable planning. The Worldwide Spark Testing Machines Market research is designed around operational relevance. It maps the equipment landscape across the principal technology categories used in contemporary manufacturing and quality-control environments, providing a comparative view of where capacity, pricing volatility, and specification requirements are concentrating. Rather than offering static snapshots, the analysis traces how different testing modalities are positioned relative to production throughput, cable and coating profiles, and compliance expectations.
The application dimension is treated with equal rigor. The report examines how demand is distributed across major end-use environments, including power cable manufacturing, automotive wiring harness production, communication and data cable fabrication, and building wire and related applications. This segmentation matters because each use case carries distinct defect-detection thresholds, electrode contact requirements, line-speed considerations, and certification dependencies. Understanding which applications are expanding most rapidly, and why, enables manufacturers and suppliers to prioritize product development, service coverage, and market-entry timing.
Regional intelligence is presented as a strategic overlay rather than a list of isolated figures. The study evaluates how geographic demand patterns interact with local manufacturing capacity, regulatory frameworks, and infrastructure priorities. For firms evaluating export opportunities, sourcing locations, or localized service networks, this regional lens clarifies where competition is intensifying and where whitespace may still exist. Equally important, the report frames regional performance within the broader market structure, helping leaders avoid overinvestment in regions where growth is being absorbed by established capacity or where regulatory complexity may slow adoption.
Beyond segmentation, the publication incorporates the practical elements that determine day-to-day market behavior. That includes analysis of electrode design norms, such as bead chain and brush configurations used to maintain consistent contact and fault detection on insulated cables, and the role of standardized conformance expectations in shaping procurement decisions. It also examines how product innovations are responding to space-constrained production lines and varying cable diameter ranges, reflecting the industry's shift toward compact, adaptable testing solutions. By integrating these operational details with forward-looking estimates, the report gives readers a working map of the market rather than a simple forecast.
Competitive Landscape: Leadership, Specialization, and the Battle for Specification Influence
The spark testing machines market is characterized by a recognizable concentration of established players, with the top three firms accounting for roughly 38.5 percent of collective market share and the top five reaching approximately 52.3 percent. This concentration does not imply a uniform competitive environment. Instead, it reflects a market in which leadership is built through a combination of historical invention, specification recognition, product breadth, and application-specific specialization.
Clinton Instrument Company, headquartered in Clinton, Connecticut, exemplifies the role of foundational innovation in shaping market expectations. As a pioneer and leader in high-frequency spark testers for wire and cable insulation testing, the company's early patented work established technical reference points that continue to influence buyer requirements. Its offerings span equipment for pinhole detection and custom solutions recognized by worldwide testing specifications, reinforcing a position anchored in specification credibility and application familiarity.
Proton Products, operating from the United Kingdom with global reach, illustrates a competitive model centered on versatile test platforms and standards alignment. Its InteliSENS series covers high-frequency, AC, and DC spark testers designed for single-wire and multi-wire insulation testing in cable production. By incorporating bead chain and brush electrodes that meet standards such as UL1581 and IEC62230, the company positions its equipment at the intersection of testing flexibility and compliance assurance, an increasingly valuable combination for manufacturers managing diverse product lines.
ZUMBACH Electronic AG, based in Orpund, Switzerland, demonstrates another competitive vector: compact engineering and standards-driven design. Its Sparktester series, including DST and AST models, supports mains frequency and high-frequency insulation testing on cables and tubes, with compact configurations designed for diameters up to 30 mm or more. Compliance with IEC 62230 and UL standards further underscores the market premium placed on instruments that can be integrated into constrained production environments without sacrificing certification relevance. In September 2024, the company introduced the compact DST 10 spark tester with a diameter measuring range up to 30 mm, a development that highlights how product iteration is responding to space-sensitive cable production requirements.
The competitive field extends well beyond these leaders, reflecting a spectrum of specialization. DeFelsko Corporation, located in Ogdensburg, New York, focuses on high-voltage holiday and spark detection for thicker coatings, with pulsed DC and continuous DC options used for pinhole and discontinuity detection on protective coatings applied to metal and concrete. Buckleys (UVRAL) Ltd, in the United Kingdom, addresses a different inspection context with PST-100 series handheld AC spark testers suited to thicker coatings and linings, including weld joint inspection across plastics, rubber, petrochemical, and pipeline applications.
SIKORA AG, based in Bremen, Germany, broadens the equipment conversation with AC, DC, and high-frequency spark testers for cable jacketing and insulation, including self-test and calibration modules and coverage for diameters from 1 mm to 200 mm. Wegener International GmbH, also based in Germany, contributes sinusoidal AC voltage spark testing solutions for cable insulation while also supporting watertightness testing of plastic welds in tanks and containers. Hipotronics, part of Hubbell and headquartered in Brewster, New York, rounds out the competitive ecosystem with a focus on high-voltage test equipment, including hipot and spark-related dielectric strength testers for electrical components and insulation.
This diversity of players means that competitive advantage is increasingly determined by how well a supplier can match product architecture to application requirements, certification expectations, and integration constraints. For buyers, the strategic question is not simply who offers the lowest acquisition cost, but which vendor can most reliably support specification compliance, maintenance continuity, and process adaptation over the life of the equipment. For suppliers, the challenge is to differentiate in a market where standards recognition and engineering adaptability often matter more than broad product overlap.
Hardness Testing Machine Market
Market Dynamics Shaping 2026 Strategy
Successful planning in this market requires attention to the forces that alter purchasing behavior, spec selection, and competitive positioning. Regulatory expectations remain central. Spark testers used for wire and cable insulation must align with international standards including IEC 62230, UL 1581, and UL 2556 to support reliable pinhole and fault detection during production. As these standards become more firmly embedded in buyer evaluation criteria, equipment that demonstrably supports conformance is likely to command stronger preference, especially in procurement environments where quality documentation and audit readiness carry substantial weight.
Material and component design also influence market behavior. High-voltage electrodes commonly rely on bead chain or brush designs made from conductive materials to ensure consistent contact and fault detection on insulated cables. This is not a minor technical detail; it shapes maintenance expectations, contact reliability, and suitability for different cable profiles. In practical terms, electrode configuration and contact consistency are becoming part of the value proposition that separates routine testers from process-critical inspection tools.
On the demand side, the broader macro trend is clear: the requirement for spark testing equipment is being reinforced by expansion in global wire and cable manufacturing, ongoing infrastructure investments, and tighter safety and quality regulations in electrical applications. These drivers do more than add volume; they change the nature of purchasing. As inspection becomes more integrated into production continuity and compliance documentation, buyers are increasingly sensitive to reliability, throughput compatibility, and the ability to adapt to varying cable and coating specifications. That shift favors suppliers and internal teams that can articulate total operational value rather than list price alone.
Why the Full Report Matters for 2026 Decision-Making
Leaders evaluating market entry, capacity expansion, vendor selection, or investment allocation need more than directional confidence. They need a research basis that connects growth trends to the underlying segments, regional dynamics, and competitive behaviors that actually determine outcomes. The Worldwide Spark Testing Machines Market report is built for that purpose. It translates historical performance into a disciplined forecast framework, separates broad market momentum from segment-level opportunity, and frames competitive intensity in terms that support practical strategy.
The preview presented here has been designed to demonstrate analytical depth without disclosing the full segmentation values, regional percentages, and application-level figures that constitute the report's core intelligence. Those details are where the most actionable insights reside: in the relative weight of testing technologies, the distribution of demand across end-use categories, and the geographic patterns that inform sourcing, service coverage, and expansion timing. Accessing the complete publication allows organizations to move from general awareness to precise, evidence-backed planning.
PW Consulting's market research is intended to function as a decision-support instrument, not a static reference document. For executives and analysts preparing for 2026, the report offers the kind of structured intelligence that reduces uncertainty around specification choices, competitive exposure, and demand timing. The market's measured growth and evolving competitive dynamics make this an opportune moment to ground strategy in verified data rather than assumption.
To obtain the complete segmentation analysis, regional assessments, company profiles, and forward forecasts, please visit the source page for the full Worldwide Spark Testing Machines Market research. The full study provides the detail required to convert market momentum into disciplined strategy for the year ahead.
Worldwide Spark Testing Machines Market
For detailed analysis of this topic, please visit the official page: Worldwide Spark Testing Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com