

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Sees Neulasta and Biosimilar Market Recover to $3.4B by 2026, Growing at 2.02% CAGR

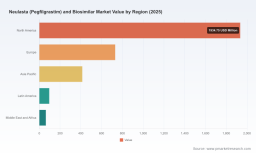
Strategic Intelligence: Navigating the Fork in the Road for Pegfilgrastim and Neulasta Biosimilars Through 2032
Executive Overview: A Market in Structural Transition
The global landscape for Neulasta (pegfilgrastim) and its expanding biosimilar cohort has entered a decisive new phase. Following five years of pronounced revenue contraction, market modeling indicates that the worldwide market will stabilize in 2026 at approximately $3,404.3 million, reflecting a measured compound annual growth rate of 2.02 percent across the 2026 to 2032 forecast horizon. This trajectory is not a simple recovery narrative. It is a structural recalibration driven by aggressive biosimilar penetration, evolving clinical delivery preferences, reimbursement mechanisms that increasingly reward cost efficiency, and distinct regional adoption curves that reward localized commercial execution.
The historical dataset underpinning this outlook captures a steep pricing and volume adjustment period. From 2020 through 2025, reported market value declined from roughly $5,420.3 million to $3,240.5 million, a reflection of biosimilar entry compressing the originator franchise while volume utilization expanded in chemotherapy supportive care protocols. Moving into the forecast window, the market is positioned to gradually widen through 2032, tracking a slow but deliberate ascent toward the mid-$3,700 million range. For pharmaceutical leaders, market access teams, and supply chain strategists, this inflection point demands more than retrospective analysis. It requires forward-looking intelligence that maps competitive dynamics, regulatory pacing, and delivery-device differentiation to real commercial outcomes.
Macro Trajectory and the Geometry of Recovery
The seven-year forecast window reveals a market that is neither collapsing nor exploding, but carefully rebalancing. After bottoming in 2025, top-line valuations are projected to expand incrementally through the late 2020s, with modest year-over-year adjustments reflecting the interplay between net price erosion and volume uptake across biosimilar offerings. This pattern illustrates a mature biologic category where therapeutic equivalence has already been established in the eyes of prescribers and payers. The commercial battlefield has therefore moved from clinical differentiation to operational execution, device preference, channel economics, and contracting velocity.
Importantly, the stabilization narrative masks considerable variation in how value is being redistributed across segments. Originator portfolios with differentiated delivery technology continue to defend meaningful share, while biosimilar entrants compete on acquisition pricing, institutional relationships, and manufacturing reliability. The overall market growth rate of 2.02 percent is best interpreted as a baseline equilibrium: enough expansion to justify sustained investment in commercial infrastructure, but not enough to reward undifferentiated scale plays. Companies that treat this as a commodity category risk being outmaneuvered by competitors who understand where margin actually survives in a biosimilar-heavy ecosystem.
Competitive Architecture: Incumbent Defense Meets Biosimilar Offensives
The competitive structure of this market is highly concentrated, a reality that shapes pricing behavior, formulary strategy, and partnership economics. The top three firms collectively account for 62.45 percent of category value, while the top five extend their influence to 81.3 percent. This concentration does not imply a static hierarchy. It reflects a tiered ecosystem in which originator assets, biosimilar portfolios, and specialized commercialization partners are locked in continuous renegotiation of value.
Amgen remains the defining incumbent. As the originator of Neulasta and the Neulasta Onpro on-body injector, the company anchors a franchise historically built on reduction of febrile neutropenia in patients receiving myelosuppressive chemotherapy, alongside indications tied to the hematopoietic subsyndrome of acute radiation syndrome. Amgen’s continued presence in the market through 2025 and beyond demonstrates that originator assets can retain relevance even amid sustained biosimilar competition, particularly when delivery convenience creates a practical barrier to full substitution. At the same time, net price declines and sales erosion in the established products segment underscore that defensive positioning requires continuous investment in device experience, payer engagement, and supply reliability.
Biosimilar participants have built a crowded and increasingly sophisticated field. Lupin Limited recently moved into a more prominent commercial position with FDA approval of Armlupeg (pegfilgrastim-unne) 6 mg/0.6 mL pre-filled syringe in late 2025, complementing an exclusive US commercialization and distribution arrangement with Valorum Biologics. Under this structure, Lupin retains responsibility for manufacturing and supply from its Pune, India biotech facility, while Valorum leads downstream commercialization. The arrangement illustrates a recurring strategic pattern in this category: originator-scale manufacturing capability paired with specialized US commercial execution.
Coherus BioSciences, now aligned through partnerships involving Intas and Accord, markets Udenyca and Udenyca Onbody autoinjector/on-body injector versions, extending biosimilar competition into delivery formats that directly challenge device-dependent usage patterns. Biocon and Viatris continue to advance Fulphila, while Sandoz, a Novartis division, markets Ziextenzo. Pfizer competes with Nyvepria, and Amneal Pharmaceuticals, working in collaboration with Kashiv Biosciences, promotes Fylnetra. Fresenius Kabi rounds out the landscape with Stimufend. Taken together, these players demonstrate that the biosimilar segment is no longer a single-format contest. It is a multi-formulation, multi-device competition in which supply chain integrity and device familiarity are becoming as commercially decisive as acquisition cost.
Market Dynamics: Seven Biosimilars, Device Loyalty, and Volume Reallocation
Several interlocking dynamics explain why the post-2025 market behaves differently from the contraction period that preceded it. By late 2025, the US FDA had approved seven pegfilgrastim biosimilars to Neulasta, with Armlupeg representing the most recent addition. This level of regulatory clearance indicates that the category has moved well past the early-adopter phase of biosimilar adoption. The practical consequence is that institutional purchasing groups and oncology practices now evaluate pegfilgrastim options through a lens of operational fit rather than first-time equivalence.
Reimbursement patterns further complicate the picture. In the US, pegfilgrastim biosimilar market share has reached up to 85 percent by year seven post-entry, with two leading products accounting for 73 percent of biosimilar share. This concentration within the biosimilar tier is a critical strategic signal. It suggests that early price leadership and contract positioning can lock in durable share, but it also means that later entrants must either bring a differentiated delivery solution, a superior supply proposition, or a specialized access strategy to avoid commoditization.
Device economics remain a defining friction point. Amgen’s Neulasta Onpro on-body injector continues to retain meaningful share because of its convenience profile and the current lack of fully comparable biosimilar delivery devices. In supportive cancer care, where workflow efficiency, nursing burden, and patient experience can influence adoption as much as drug acquisition cost, device parity is not a trivial feature. It is often the difference between superficial biosimilar substitution and structural market displacement.
Meanwhile, originator and biosimilar manufacturers alike are navigating the same underlying manufacturing reality. Pegfilgrastim is a PEGylated recombinant human granulocyte colony-stimulating factor biologic, and producing it reliably requires specialized biologics manufacturing infrastructure. That requirement elevates the strategic value of compliant facilities, consistent batch performance, and scalable supply commitments. In a category where multiple approved alternatives already exist, continuity of supply and quality assurance can become the tie-breaker in institutional sourcing decisions.
Worldwide Neulasta (Pegfilgrastim) and Biosimilar Market
Report Scope: The Operational Intelligence Behind the Headlines
The full market research study is designed for executives who need decision-grade clarity rather than high-level aggregates. It translates the macrotrajectory into a practical operating framework, mapping how distinct product forms, distribution channels, and regional demand patterns interact to shape revenue capture in the 2026 to 2032 period.
The analysis examines the competitive implications of pre-filled syringe and on-body injector formats, not simply as product specifications, but as commercial variables that influence substitution behavior, nursing workflow, procurement economics, and formulary placement. It further evaluates how hospital pharmacies, retail pharmacies, and online pharmacies channel pegfilgrastim utilization in different treatment settings, with attention to contract structures, inventory logistics, and the shifting balance between inpatient and outpatient administration.
Beyond segmentation, the report situates manufacturer strategies within the operational realities of biosimilar commercialization. It explores how licensing agreements, manufacturing footprints, and US commercialization partnerships affect time-to-market, launch execution, and long-term share durability. It also contextualizes regulatory pacing and reimbursement pressure as continuous strategic inputs rather than one-time events, helping teams anticipate where net pricing, volume migration, and channel mix are likely to move next.
Long-acting G-CSF Market
Importantly, the study treats the market as a system of trade-offs. Growth in one channel or format often intersects with pricing pressure in another. Concentration among a small number of leading players raises the stakes for launch sequencing and contracting discipline. Regional variation matters because adoption velocity, procurement models, and reimbursement design do not move in lockstep across markets. The report framework is built to help readers see these interconnections before they commit capital or reshape go-to-market plans.
What 2026 Decision-Makers Must Get Right
For organizations operating in or adjacent to this market, 2026 is not a year for passive observation. The combination of a stabilizing top-line environment, high biosimilar penetration, device-sensitive adoption, and a concentrated competitive set means that small strategic advantages can compound quickly. Several priorities stand out.
- First, evaluate exposure to device-dependent demand. Where usage relies heavily on on-body injector convenience, biosimilar substitution may progress more slowly than headline share numbers suggest. Commercial plans should reflect the actual substitution ceiling in each institutional segment rather than assuming uniform adoption.
- Second, treat manufacturing and supply reliability as a commercial differentiator. In a category with multiple approved alternatives, procurement teams will increasingly favor partners who can demonstrate consistent supply, regulatory readiness, and risk-mitigated production capacity.
- Third, calibrate contracting strategies to the real distribution of share within the biosimilar tier. Since a small number of products can command a disproportionate share of biosimilar utilization, entry timing, contract placement, and access partnerships may matter more than broad pricing discounts alone.
- Fourth, align regional planning with local market structure. Demand patterns, channel economics, and reimbursement dynamics differ materially across geographies, and the aggregate market trend can obscure where value is actually created or defended.
Conclusion: The Market Is Settling, Not Simplifying
The worldwide Neulasta and pegfilgrastim biosimilar market is entering a period where clarity, not scale alone, will determine commercial success. The 2026 to 2032 outlook points to a market that has absorbed the shock of biosimilar entry, stabilized its revenue base, and begun a gradual upward march shaped by device differentiation, channel economics, and competitive concentration. That environment rewards teams who can read the structural signals early: which delivery formats are protected by workflow preference, which biosimilar positions are likely to consolidate share, and where originator franchises can still extract value through convenience and reliability.
The full research study provides the detailed segmentation, competitive diagnostics, and scenario-based context required to convert these signals into action. For executives planning product positioning, market access strategy, partnership selection, or portfolio exposure in the pegfilgrastim category, the difference between a reactive posture and a decisive one will come down to how precisely the market is understood before the next wave of contracting and adoption decisions takes hold.
For detailed analysis of this topic, please visit the official page: Worldwide Neulasta (Pegfilgrastim) and Biosimilar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com