

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Low Carbon Primary Aluminium Market to Reach $181.7B by 2032, Growing at 15.5% CAGR

The Low Carbon Primary Aluminium Market: Strategic Imperatives for 2026 and Beyond
The global transition toward decarbonized industrial supply chains has placed low carbon primary aluminium at the forefront of strategic material markets. As of 2025, the sector commands a substantial revenue base, having expanded consistently from approximately $32.45 billion in 2020 to over $66.25 billion in the base year. Forward projections indicate that the market will continue its robust expansion trajectory, crossing the $75.87 billion threshold in 2026 and scaling toward $181.66 billion by 2032. This sustained growth is anchored by a compound annual growth rate of 15.5 percent across the 2026 to 2032 forecast period, reflecting the accelerating alignment of industrial procurement, regulatory pressure, and technological maturation.
For executive leadership, procurement architects, and sustainability strategists, the low carbon primary aluminium landscape is no longer a peripheral ESG consideration. It has evolved into a core competitive differentiator, a compliance necessity, and a sourcing imperative. The market research released by PW Consulting maps this transformation with precision, offering decision-makers a structured pathway to navigate sourcing allocations, technology investments, and regional capacity shifts throughout the remainder of the decade.
Market Architecture and Growth Catalysts
The expansion of low carbon primary aluminium is fundamentally driven by the intersection of energy transition mandates and industrial decarbonization targets. Aluminium smelting has historically been energy-intensive and carbon-heavy, but the last five years have witnessed a decisive shift toward renewable-powered electrolysis, inert anode experimentation, and integrated supply chain optimization. The market's trajectory reflects not only incremental improvements in existing smelting operations but also the emergence of entirely new production pathways that decouple metal output from direct greenhouse gas emissions.
Revenue growth over the historical 2020 to 2025 window was shaped by early-adopter procurement commitments, voluntary carbon disclosure frameworks, and the gradual pricing of carbon in key jurisdictions. The forecast period from 2026 onward amplifies these drivers. Regulatory mechanisms that internalize the cost of embedded emissions are now operational, while multinational manufacturers face mounting pressure to secure verifiable low-carbon inputs for automotive, construction, packaging, electrical systems, and consumer durables applications. The market's compounding growth rate underscores how quickly low carbon primary aluminium is transitioning from a niche premium segment to a mainstream procurement category.
Understanding the structural components of this growth requires a granular view of production sources, end-use demand, and regional capacity distribution. Each of these dimensions carries distinct risk profiles, supply continuity considerations, and pricing dynamics that directly influence corporate sourcing strategies. The report dissects these layers systematically, enabling buyers and investors to anticipate where capacity will materialize, which production technologies will achieve commercial scale, and how demand elasticity will evolve across industrial verticals.
Production Pathways and Technology Trajectories
Low carbon primary aluminium is not a uniform commodity. It emerges from multiple production architectures, each with its own emissions profile, scalability constraints, and cost structure. The market research categorizes and evaluates these pathways to clarify which technologies will dominate near-term supply and which will define the long-term decarbonization frontier.
- Hydro-powered smelting continues to anchor a significant share of low-carbon output, leveraging established renewable electricity infrastructure in regions with favorable hydropower endowments. This pathway benefits from mature operational footprints, predictable energy costs, and verifiable Scope 2 reductions, making it the backbone of currently available low-carbon supply.
- Wind and solar-powered smelting represents a rapidly expanding alternative, particularly in regions where corporate power purchase agreements and renewable grid integration can be synchronized with smelter demand profiles. This pathway is gaining traction as industrial buyers seek geographically diversified, renewable-matched supply that aligns with Scope 2 reduction targets.
- Inert anode technology marks the most transformative frontier, targeting the elimination of direct greenhouse gas emissions from the electrolysis process itself. While still advancing through industrial-scale deployment milestones, this technology is being positioned as the long-term zero-emission standard and is already attracting joint venture investment, pilot integration, and strategic partnerships among major producers.
Beyond production sources, the report examines the technological and operational levers that producers are deploying to strengthen their low-carbon credentials. Closed-loop recycling integration, renewable energy optimization, carbon capture research, and advanced process efficiency upgrades are all factored into the competitive assessment. The analysis distinguishes between near-term commercial readiness and longer-horizon innovation, allowing stakeholders to separate currently purchasable supply from future capacity that may reshape procurement planning over the 2028 to 2032 window.
End-Use Demand and Regional Supply Dynamics
Demand for low carbon primary aluminium is distributed across a broad industrial base, but the concentration and growth pace vary materially by sector. Automotive and transportation applications lead demand allocation, reflecting OEM commitments to lightweighting, electrification, and lifecycle carbon reduction. Construction and building sectors follow closely, driven by green building certification requirements, structural material decarbonization targets, and the growing preference for low-embodied-carbon metals in large-scale infrastructure projects.
Packaging demand, particularly in beverage and consumer goods supply chains, has accelerated as brands pursue verifiable footprint reductions and circular-material strategies. Electrical and electronics applications contribute a meaningful share, with data center expansion, grid modernization, and energy-efficient component manufacturing creating new procurement vectors. Consumer durables round out the demand landscape, where premium branding and sustainability positioning increasingly influence material selection.
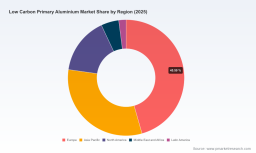
Regionally, the market exhibits a clear hierarchy of supply concentration and procurement relevance. Europe maintains a leading position in low-carbon aluminium demand and regulatory-driven procurement, reinforced by carbon border mechanisms and stringent industrial emissions frameworks. Asia Pacific represents a large and growing market region, shaped by manufacturing scale, industrial modernization, and increasing attention to supply chain transparency. North America functions as a strategically important market where trade measures, domestic capacity restarts, and renewable-powered sourcing initiatives converge. The Middle East and Africa, along with Latin America, contribute specialized supply roles, often tied to renewable resource endowments, integrated mining-to-smelting operations, and emerging export-oriented low-carbon production.
The report avoids oversimplified regional generalizations. Instead, it provides a structured comparison of regional capacity readiness, policy exposure, trade-flow sensitivity, and procurement timing, enabling buyers to calibrate sourcing geographies against their own compliance timelines and cost constraints.
Competitive Landscape and Strategic Positioning
The low carbon primary aluminium market is shaped by a concentrated group of global producers, each pursuing distinct decarbonization strategies, geographic expansions, and technology partnerships. The report profiles the core companies that define the current competitive topology and tracks the strategic moves that are reshaping supply availability.
Among the leaders, Rio Tinto and Alcoa Corporation stand out for their coordinated advancement of inert anode technology through the ELYSIS joint venture, alongside established hydro-powered smelting operations in Canada and other renewable-rich jurisdictions. Rio Tinto has also expanded its low-carbon integrated footprint through a controlling stake acquisition in a Brazilian producer, strengthening renewable-powered supply exposure in South America. Norsk Hydro ASA emphasizes hydro-powered smelting operations with benchmark-low emission plants and offers a differentiated low-carbon product line supported by closed-loop recycling and renewable energy optimization. Aluminerie Alouette operates one of the largest primary aluminium smelters in the Americas, underpinned by a nearly fully renewable electricity base and emissions performance significantly below the global average.
United Company RUSAL continues to advance low-carbon aluminium using hydropower and inert anode development, while also introducing industrial-scale low-carbon beverage can solutions with high recycled content and reduced footprint targets. Emirates Global Aluminium focuses on scaled, decarbonized operations and is evaluating broader geographic expansion, including potential smelter initiatives in new markets. Century Aluminum Company is repositioning U.S. capacity with an emphasis on low-carbon and value-added products, including the restart of idled smelting capacity. Aluminium Dunkerque has established one of the lowest carbon footprints among European smelters, with comprehensive decarbonization efforts spanning recycling, carbon capture, and nuclear power purchase agreements.
Vedanta Aluminium is pursuing low-carbon initiatives within domestic Indian infrastructure and smelter project development. Aluminum Corporation of China Limited (Chalco) participates in international low-carbon expansions through joint acquisitions and strategic partnerships, reinforcing the global redistribution of renewable-powered supply. Companhia Brasileira de Alumínio represents a vertically integrated model with 100 percent renewable electricity, bauxite mining, alumina refining, and smelter capacity, positioning Brazil as an increasingly relevant low-carbon supply hub.
High Purity Aluminum Market
Recent strategic developments illustrate how quickly this competitive landscape is evolving. A major joint venture achieved a milestone in deploying an industrial-size carbon-free inert anode in an existing smelter, signaling tangible progress toward zero direct emissions smelting. Leading producers have launched industrial-scale low-carbon aluminium cable production tailored for data center applications, aligning decarbonized metal supply with rapid digital infrastructure growth. Strategic partnerships have also accelerated carbon capture research across smelting operations, with multi-year investment commitments aimed at reducing residual emissions. Meanwhile, feasibility activity around new low-carbon smelter projects in Northern Europe indicates that capacity expansion is becoming increasingly tied to renewable energy availability and technology readiness.
Regulatory, Trade, and Input Market Dynamics
No low carbon primary aluminium strategy can be built on technology and supply alone. Market participants must also navigate a rapidly changing regulatory and input-cost environment that directly affects pricing, sourcing eligibility, and competitive exposure.
The implementation of the EU Carbon Border Adjustment Mechanism marked a defining regulatory milestone, applying carbon-linked charges to aluminium imports based on embedded emissions. This mechanism reshapes the cost competitiveness of conventional primary aluminium relative to verified low-carbon supply and incentivizes procurement shifts toward materials with demonstrable emissions advantages. In parallel, China's enforcement of a primary aluminium production capacity ceiling constrains supply elasticity in one of the world's largest producing regions, reinforcing the strategic importance of diversified, low-carbon sourcing channels.
Trade measures and tariff dynamics have also influenced market pricing and regional supply rerouting, contributing to volatility in benchmark aluminium pricing during early 2026. At the input level, alumina and bauxite pricing movements have introduced additional variability into smelter economics. Alumina spot assessments have shown moderation after earlier period averages, while bauxite pricing has experienced declines following earlier peaks. These input dynamics affect margin structures, capacity utilization decisions, and the relative attractiveness of different production geographies.
Together, these regulatory, trade, and raw material factors create a decision environment in which low carbon primary aluminium is not only a sustainability choice but also a risk-mitigation and cost-structuring instrument. The report integrates these dynamics into a cohesive market view, helping stakeholders interpret how policy shifts, trade flows, and input-cost cycles interact with technology deployment and procurement timing.
What the PW Consulting Report Delivers
The Low Carbon Primary Aluminium Market research is designed as an execution-oriented intelligence asset rather than a static market summary. It combines macro market sizing, forward forecasts, segmentation analysis, competitive profiling, and dynamic regulatory context into a unified decision framework. The objective is to give procurement leaders, strategy teams, investors, and supply chain planners a single reference point for evaluating where low-carbon aluminium supply is expanding, which technologies will define future procurement options, and how regional and regulatory factors will influence sourcing economics.
The report provides a structured breakdown of production source pathways, end-use industry demand allocation, and regional market distribution, enabling stakeholders to identify where supply is most concentrated, where demand growth is strongest, and where competitive intensity is likely to increase. It profiles the leading producers and their strategic differentiators, tracks recent partnerships, technology milestones, acquisitions, and product launches, and places these developments within the broader context of decarbonization timelines and capacity expansion plans.
In addition, the research incorporates the latest market dynamics related to raw material pricing, regulatory implementation, capacity constraints, and trade measures, allowing readers to interpret market movement through a multi-variable lens. The analysis is built to support scenario-aware planning: buyers can evaluate sourcing diversification, producers and investors can assess technology and geographic positioning, and sustainability teams can align procurement claims with verifiable supply characteristics.
Importantly, the report preserves forward visibility across the 2026 to 2032 forecast horizon, giving stakeholders a structured basis for multi-year planning rather than short-term reaction. By integrating historical growth evidence with projected expansion, segmentation structures, competitive movements, and external market forces, the research equips organizations to make sourcing, investment, and compliance decisions with greater confidence and specificity.
Strategic Takeaways for 2026 Decision-Making
The low carbon primary aluminium market is entering a phase in which strategic advantage will belong to organizations that can align procurement, compliance, and supply-chain design with a clear understanding of technology readiness, regional capacity, and regulatory exposure. Several implications stand out for decision-makers operating in 2026.
Low Carbon Primary Aluminium Market
- Procurement strategies must move beyond aggregate market sizing and engage directly with production-source differentiation, because hydro-powered, wind/solar-powered, and inert-anode-based supply carry different emissions profiles, scalability trajectories, and commercial availability windows.
- Regional sourcing decisions should account for regulatory pressure, trade dynamics, and renewable-energy endowments, since carbon border mechanisms, capacity ceilings, and tariff environments are actively reshaping relative cost and availability across markets.
- Competitive monitoring should focus not only on current production footprints but also on partnerships, technology milestones, and integrated expansions, because the next wave of supply differentiation will come from joint ventures, renewable-powered integrated operations, and pilot-to-commercial transitions in zero-emission smelting.
- Input-market volatility in alumina and bauxite, alongside shifting benchmark aluminium pricing, means that low-carbon sourcing decisions should be evaluated within a broader cost-structure and risk-management framework rather than as isolated sustainability purchases.
- Multi-year planning should be anchored to the forecast horizon, because the market's projected expansion will likely intensify competition for verified low-carbon supply, accelerate technology commercialization, and increase the premium on early, informed sourcing commitments.
The full research release provides the detailed segmentation values, competitive benchmarks, regional breakdowns, and forward forecasts needed to operationalize these strategic conclusions. For teams preparing sourcing strategies, compliance roadmaps, capacity evaluations, or investment thesis development, the report offers a comprehensive foundation for navigating the low carbon primary aluminium market through 2032.
For detailed analysis of this topic, please visit the official page: Low Carbon Primary Aluminium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com