

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: 24-Hour Gym Market to Hit $38.87 Billion by 2032 at 6.75% CAGR

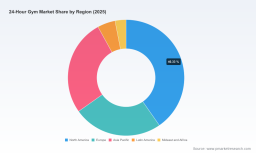
Navigating the 24-Hour Gym Market: Strategic Intelligence for 2026 Decision-Makers
The global fitness industry is undergoing a structural transformation driven by shifting consumer schedules, technological automation, and an intensified focus on personalized wellness. For investors, operators, and corporate strategists, the 24-hour gym segment represents one of the most dynamic and resilient sub-sectors within the broader health and wellness economy. As we enter 2026, the need for precise, forward-looking market intelligence has never been more critical. This article introduces our latest comprehensive market research on the 24-Hour Gym Market, outlining the strategic architecture of the study, the competitive forces reshaping the landscape, and the operational dynamics that will define profitability and growth over the forecast horizon.
Our research is designed not merely to report historical trends, but to equip leadership teams with the analytical frameworks required to navigate an increasingly complex operating environment. By synthesizing macro-level revenue trajectories with granular competitive profiling, facility innovation tracking, and cost-structure modeling, this study serves as a foundational decision-support tool for capital allocation, market entry planning, and operational optimization in 2026 and beyond.
Market Trajectory and Forecast Architecture
The 24-hour gym market has demonstrated consistent expansion over the past half-decade, reflecting a durable alignment between consumer demand for flexible access and the operational efficiencies enabled by modern facility design. Drawing on a historical baseline spanning 2020 through 2025, our analysis captures a sector that has steadily scaled its revenue footprint, culminating in a 2025 market valuation that underscores the segment's commercial maturity. Looking ahead, the forecast period from 2026 through 2032 projects a compound annual growth rate of 6.75%, signaling sustained momentum rather than a short-term cyclical spike.
This growth trajectory is not uniform across time or geography. The early forecast years reflect a market still absorbing post-pandemic behavioral shifts, while the latter half of the projection window captures the compounding effects of facility modernization, franchise network expansion, and the integration of intelligent access and recovery technologies. All financial figures are anchored in USD and expressed in billions, providing a consistent unit of account for cross-market comparison and scenario modeling. The research deliberately structures its forecasting methodology to account for variables such as membership pricing elasticity, equipment lifecycle depreciation, and regional real estate cost differentials, ensuring that leadership teams can stress-test their strategic assumptions against multiple macroeconomic conditions.
Importantly, the study avoids the common pitfall of treating the market as a monolithic entity. Instead, it maps revenue distribution across key structural dimensions, allowing strategists to identify where value is being created, where competitive intensity is concentrating, and where whitespace opportunities may be emerging. The segmentation architecture, competitive mapping, and operational cost benchmarking are all calibrated to answer the questions that boardrooms and private equity diligence teams actually ask: Where is the growth? Who is capturing it? And what operational levers determine whether a given location or membership model achieves target returns?
What the Research Delivers: Operational Content and Analytical Depth
This market study is built around actionable intelligence rather than abstract commentary. The deliverable is structured to move sequentially from macro validation to micro execution, ensuring that readers can translate insight into planning. At the core of the report is a detailed segmentation analysis that disaggregates market revenue by membership type, equipment category, and regional footprint. This framework enables stakeholders to evaluate which access models are driving the highest retention, which equipment categories are commanding the strongest capital allocation, and how regional demand patterns diverge in ways that materially affect site selection and build-out economics.
Beyond segmentation, the research incorporates a rigorous competitive landscape assessment. Rather than offering a superficial list of players, the study profiles the operational philosophies, expansion postures, and strategic positioning of the sector's most influential operators. These profiles are contextualized within broader industry dynamics, including the shift toward franchise-led scalability, the rise of micro-gym formats optimized for low-staff or unmanned operation, and the strategic importance of ancillary amenities in differentiating otherwise commoditized access models.
The report also integrates a forward-looking component on technology and operational efficiency. As 24/7 facilities increasingly rely on IoT-enabled access control, automated membership management, and AI-driven scheduling and equipment monitoring, the study maps how these capabilities are reshaping unit economics. Labor allocation, member throughput, and facility utilization are examined through the lens of cost optimization, with explicit attention to how technology adoption alters the traditional expense structure of full-service and hybrid fitness environments.
To support scenario planning, the research includes operational benchmarking data that situates labor costs, occupancy expenses, and ancillary service revenue within realistic ranges for different facility archetypes. These benchmarks are essential for evaluating whether a proposed market entry, remodel program, or membership repackaging initiative is financially viable under local conditions. By coupling these benchmarks with competitive intelligence and forecast data, the study provides a multi-layered foundation for strategic decision-making.
24 Hour Emergency Roadside Assistance Market
Competitive Landscape: Key Players and Strategic Positioning
The competitive architecture of the 24-hour gym market is defined by a mix of large-scale branded operators, franchise networks, and regionally concentrated chains, each pursuing distinct value propositions within the flexible-access segment. Understanding how these players differentiate themselves is essential for evaluating market entry risks, partnership opportunities, and competitive threats.
Anytime Fitness operates as the largest 24/7 gym franchise network, with a globally distributed footprint that spans thousands of locations. Its model emphasizes key-fob access, a consistent equipment mix across strength and cardiovascular categories, and a community-oriented micro-gym format designed to accommodate varied schedules without the congestion typical of larger facilities. The franchise structure enables rapid geographic scaling while maintaining a relatively standardized member experience, making the brand a benchmark for scalability in the 24-hour segment.
24 Hour Fitness remains a major operator of 24/7 fitness centers, concentrated primarily across a set of U.S. states. Its positioning targets the mid-market 24-hour access consumer while increasingly layering on personalization and recovery-oriented amenities. Recent strategic actions signal a deliberate shift toward facility modernization and brand revitalization. In early 2026, the company's founder partnered with LongRange Capital to reacquire the business and return as Owner and Executive Chair, with a stated focus on innovation, remodels, partnerships, and expansion. This leadership realignment has been accompanied by a substantial club upgrade program exceeding $100 million, incorporating new floorplans, Recovery24 spaces, Reformer24 Pilates offerings, and updated strength equipment, with a target of redesigning dozens of clubs within the first half of 2026. Anticipating this transformation, the company introduced a personalized fitness approach in late 2025 emphasizing coaching flexibility and member wellness experiences, and had previously rolled out service innovations including recovery tools, intelligent machines, and Pilates programming.
Snap Fitness represents another franchise-led 24/7 model, building a network of hundreds of locations around flexible month-to-month memberships and a supportive, less-crowded environment. Its strategy places emphasis on strength and cardiovascular equipment, personal training, group classes, and recovery amenities such as infrared saunas. By catering to members who value schedule flexibility and a lower-density workout setting, Snap Fitness occupies a distinct position within the broader 24-hour ecosystem, particularly among consumers who prioritize convenience and a streamlined experience over large-scale group programming.
Workout Anytime operates as a franchise chain focused on 24/7 high-value, low-price access. Its model pairs cardio and strength training with personal training, tanning, and recovery amenities, all accessible through 24-hour key access. The emphasis on convenience and affordability positions the brand as a value-oriented alternative within the flexible-access category, appealing to cost-conscious members who still demand round-the-clock availability and essential amenity support.
Together, these operators illustrate the range of strategic approaches available in the 24-hour gym market: franchise scalability, branded mid-market revitalization, community-focused micro-gyms, and value-driven convenience. The research maps how each model interacts with membership pricing, equipment investment, labor deployment, and amenity differentiation, providing strategists with a comparative lens for evaluating competitive pressure and opportunity.
Industry Dynamics Shaping 2026 and Beyond
Several structural forces are converging to redefine how 24-hour gyms create and capture value. On the demand side, health and fitness spending continues to reflect strong consumer commitment. Recent survey data indicates that Americans plan to allocate approximately $60 billion toward health and fitness in 2026, with average planned spending of roughly $733 per person among those setting goals. This spending intent underscores a resilient consumer base, but it also raises the bar for operators to justify membership choices through differentiated experiences, flexible access, and demonstrable wellness outcomes.
On the cost side, labor remains a defining constraint. For full-service gym environments, staff and instructor wages typically account for around 30% of revenue, while boutique and studio formats often see labor fall in the 20% to 25% range. When combined with rent, labor and occupancy frequently comprise 50% to 70% of operating expenses. These cost realities make the 24/7 unmanned or low-staff model particularly compelling when executed effectively. By leveraging IoT and AI for access control, monitoring, and routine operations, such facilities can reduce labor intensity while preserving flexible member access. The research examines how these technology-driven models influence payback periods, membership pricing thresholds, and the trade-off between automation and the perceived value of staffed touchpoints.
At the same time, facility-level innovation is becoming a competitive differentiator. Remodel programs, recovery amenities, and personalized programming are no longer optional enhancements for many branded operators; they are central to retention strategy and pricing power. The integration of recovery spaces, intelligent equipment, and tailored coaching models reflects a broader industry shift toward experiential value, where access alone is insufficient to sustain premium positioning. The study evaluates how these investments translate into membership segmentation performance and how operators can sequence capital deployment to maximize near-term engagement while preserving long-term asset value.
Market Concentration and Strategic Implications
The 24-hour gym market is not evenly distributed among participants. Competitive concentration analysis reveals that the three largest firms capture approximately 28.5% of market revenue, while the top five collectively account for roughly 36.2%. This concentration pattern indicates that scale, brand recognition, and network effects matter, but it also leaves meaningful room for regional specialists, franchise expansion, and niche positioning. For strategists, this landscape has several implications.
First, concentration at the top suggests that established operators benefit from shared infrastructure, standardized operating procedures, and the ability to amortize technology and remodel investments across large fleets. Second, the remaining market share is sufficiently fragmented to allow targeted entry strategies, particularly in underserved regions or within membership segments that prioritize specific amenities, price points, or community dynamics. Third, concentration data should be interpreted alongside regional and segmentation performance, since national share does not automatically translate into local dominance. The research provides the analytical scaffolding needed to assess where concentration reflects genuine competitive moats and where it merely reflects historical footprint rather than future advantage.
Why This Research Matters for 2026 Decision-Making
As organizations plan capital deployment, market expansion, and operational optimization in 2026, the quality of market intelligence directly influences the quality of decisions. This study is designed to reduce ambiguity across several high-stakes planning dimensions. For investors and corporate development teams, it clarifies where growth is most likely to materialize, which membership and equipment categories are driving the largest revenue pools, and how competitive concentration shapes margin dynamics. For operators and franchise decision-makers, it offers benchmarks for labor and occupancy costs, technology adoption pathways, and the strategic trade-offs involved in remodeling, amenity expansion, and membership repackaging. For market entrants, it provides a structured view of regional demand patterns and competitive positioning without oversimplifying the local nuances that determine site-level success.
Crucially, the research does not stop at headline figures. It integrates macro growth signals with competitive profiles, operational cost realities, and technology-driven efficiency trends, enabling decision-makers to connect high-level market direction with on-the-ground execution considerations. This integrated approach is particularly valuable in a sector where membership models, equipment mix, and staffing strategies interact so tightly with unit economics and member retention.
Accessing the Full Strategic Intelligence
This article provides a curated preview of the analytical framework and strategic relevance embedded in our 24-Hour Gym Market research. To fully operationalize these insights, stakeholders require the complete dataset, detailed segmentation breakdowns, competitive profiling depth, regional performance context, and scenario-ready forecast tables that underpin the study's conclusions. The full report is structured to support direct application in investment memos, expansion plans, competitive response strategies, and operational budgeting cycles.
For leadership teams preparing for 2026 and the forecast window through 2032, the comprehensive version of this research offers the granularity needed to move from directional confidence to precise planning. We invite decision-makers, investors, and industry executives to access the complete market intelligence, where the full segmentation architecture, competitive analysis, and operational benchmarks are available in a format designed for immediate strategic use.
24-Hour Gym Market
For detailed analysis of this topic, please visit the official page: 24-Hour Gym Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com