

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Pool & Spa Supplies Market Hits $18.45B in 2025, 5.24% CAGR to 2032

Navigating the Currents: Strategic Intelligence for the Global Pool and Spa Supplies Market 2026
The global pool and spa supplies industry stands at a critical inflection point as it moves through the 2026 calendar year. For executives, investors, and strategic planners, the difference between reactive management and proactive growth lies in the quality of intelligence available. Our latest Worldwide Pool and Spa Supplies Market research report is designed not merely as a data repository, but as a strategic compass for navigating the complex economic, regulatory, and competitive currents defining this sector. As the market continues to expand beyond its 2025 baseline of 18.45 billion USD, understanding the trajectory toward 2032 becomes essential for capital allocation, supply chain optimization, and product portfolio strategy.
This comprehensive analysis synthesizes historical performance data from 2020 through 2025 with forward-looking projections extending to 2032. The narrative that emerges is one of sustained growth tempered by significant macroeconomic headwinds. With a projected compound annual growth rate of 5.24 percent over the forecast period, the sector demonstrates resilience, yet the path to 26.38 billion USD by 2032 is not linear. Stakeholders must understand where value is consolidating, how regulatory shifts are reshaping cost structures, and which competitive maneuvers are defining market leadership in this mature yet evolving landscape.
Market Trajectory and Macro Economic Context
The historical window from 2020 to 2025 established a robust foundation for the industry. Revenue grew from 14.35 billion USD to 18.45 billion USD, reflecting a post-pandemic surge in residential outdoor living and a gradual stabilization of commercial hospitality sectors. The transition from 2025 into the forecast period suggests a continued upward momentum, with 2026 opening at 18.88 billion USD. However, market participants must recognize that aggregate top-line figures mask underlying volatility driven by input costs, tariff regimes, and shifting consumer spending patterns.
Worldwide Pool and Spa Supplies Market
Our forecast model projects the market will reach approximately 20.61 billion USD by 2027 and 21.32 billion USD by 2028, before accelerating toward 23.51 billion USD in 2029. It is crucial for decision-makers to note that growth trajectories are subject to external pressures. The market demonstrates a nuanced path, with slight consolidations observed in certain forecast years before resuming expansion toward the 26.05 billion USD mark in 2031 and the final 2032 projection. This volatility underscores the necessity of scenario planning rather than reliance on static growth assumptions.
Key macro drivers influencing this trajectory include the enduring preference for residential leisure assets and the ongoing rehabilitation of commercial aquatic facilities. However, the cost environment has shifted materially. Industry estimates suggest the U.S. pool service and maintenance segment alone reached 7.2 billion USD in 2025, with residential pool owners averaging around 1,700 USD in annual maintenance spend. This recurring expenditure supports a steady baseline demand for chemicals and maintenance tools, buffering the market against some volatility in equipment sales.
Regulatory Headwinds and Supply Chain Dynamics
No strategic assessment of the 2026 landscape is complete without addressing the profound impact of trade policy and raw material costs. The expansion of Section 232 tariffs in the United States during 2025 has subjected steel and aluminum content in derivative products to significant duties, reaching up to 50 percent for certain equipment categories including pumps, valves, and fittings. These measures, combined with reciprocal tariffs impacting imports from key trading partners, have fundamentally altered the cost calculus for manufacturers and distributors.
Further compounding these pressures, new tariffs on imported steel and aluminum at a 25 percent rate, alongside baseline duties on certain chemicals and components from China, are driving up manufacturing input costs. For domestic chlorine and pool chemical manufacturers reliant on imported inputs, these cost increases pose a direct threat to margins and retail pricing stability heading into the peak 2025-2026 pool season. The Pool and Hot Tub Alliance continues to advocate on these policy fronts, representing a broader 62 billion USD U.S. industry ecosystem, but the immediate operational reality for businesses is one of compressed margins and necessary price adjustments.
Pool Chemical Market
Strategic implications of these dynamics are multifaceted. Companies must evaluate their supplier diversification strategies, reconsider inventory positioning ahead of tariff implementations, and assess the elasticity of their customer base regarding price increases. Our report dissects these supply chain vulnerabilities to help organizations model the financial impact of continued regulatory friction and identify opportunities for localization or value engineering that can mitigate cost exposure.
Segmentation Landscape: Where Value Is Created
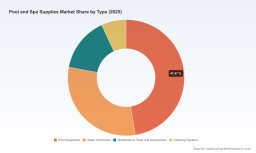
Understanding the architecture of the market is vital for targeting investment and sales efforts. The industry is broadly structured around equipment, consumables, and accessories, each exhibiting distinct growth profiles and sensitivity to economic cycles. In the equipment category, which represents a substantial portion of market revenue, innovation in energy efficiency and automation is driving replacement cycles. Water chemicals and treatment solutions form the recurring revenue backbone, closely tied to the aforementioned maintenance spend trends and regulatory standards around water quality and safety.
Maintenance tools and accessories, along with advanced cleaning systems, represent high-growth niches fueled by labor shortages in the service sector and consumer demand for convenience. The rise of robotic solutions and smart monitoring technologies is reshaping how owners interact with their aquatic assets, shifting value from purely mechanical components to integrated technology ecosystems. These segments are not growing in isolation; they are increasingly interdependent, with automation systems requiring compatible equipment and specific chemical regimes to function optimally.
Geographically, the market exhibits diverse maturity levels and growth potentials. North America remains a dominant revenue contributor, reflecting high pool penetration rates and a strong culture of residential outdoor living. Europe follows as a significant market, driven by tourism infrastructure and regulated public health standards. The Asia Pacific region presents a different dynamic, characterized by rapid urbanization and increasing disposable incomes fueling new installations. Latin America and the Middle East and Africa, while smaller in current revenue contribution, offer emerging opportunities tied to hospitality development and climate-specific demand. Our analysis provides the qualitative context and relative positioning needed to prioritize these regions without relying solely on historical volume metrics.
Competitive Arena: Strategic Positioning of Key Players
The competitive landscape is characterized by a mix of global equipment manufacturers, specialized technology providers, and massive distribution networks. Market concentration data indicates that the top three players hold approximately 32.4 percent of the market, while the top five control around 44.8 percent. This level of concentration suggests a competitive environment where scale advantages in distribution and manufacturing are significant, yet ample room remains for specialized innovators and regional leaders to capture value through differentiation.
Pentair plc continues to assert its position as a global leader, leveraging a comprehensive portfolio spanning pumps, filters, heaters, automation, and water treatment solutions across both residential and commercial segments. Their ability to integrate hardware with software services positions them well in a market increasingly driven by efficiency and connectivity. Similarly, Fluidra S.A. has built a formidable brand portfolio including Zodiac, Jandy, AstralPool, and Polaris, addressing everything from cleaning and filtration to heating and chemical systems. Their strategy emphasizes brand segmentation to address varied price points and consumer preferences across different geographies.
Hayward Holdings, Inc. remains a major force in the North American market, offering a wide array of equipment including pumps, filters, heaters, cleaners, lighting, and automation controls. Their focus on reliability and broad dealer networks reinforces their standing in the replacement and service markets. Maytronics Ltd. has carved a specialized niche through its Dolphin brand of robotic pool cleaners, capitalizing on the shift toward automated maintenance solutions that reduce labor dependency. This focus on high-value accessories allows them to punch above their weight in terms of margin contribution relative to volume.
In the residential infrastructure space, Latham Group, Inc. stands as the largest designer and manufacturer of in-ground residential pools, offering fiberglass pools, vinyl liners, and safety covers. Their recent milestone markings and product launches, including new plunge pools with integrated spas and partnerships in artistic swimming, signal a strategy of brand elevation and diversification into lifestyle experiences. Pool Corporation operates on the other side of the value chain as the largest wholesale distributor globally, wielding immense influence over product availability and pricing dynamics through its extensive sales centers and exclusive partnerships. Their recent showcases of new chemical systems and filter technologies highlight the importance of distribution partners in bringing innovation to market quickly.
Other notable participants include Jacuzzi Brands LLC with their premium positioning in spas and water features, Waterco Ltd. in filtration and treatment, and a growing cohort of manufacturers from China such as Emaux Water Technology and Guangdong Laswim, who are expanding their global footprint through cost-competitive equipment and accessories. Companies like Aqua Products Inc., S.R. Smith, Waterway Plastics, Speck Pumps, and Intex Recreation Corp. further diversify the landscape, addressing specific niches from robotic cleaners to above-ground solutions and specialized plumbing components. The interplay between these players defines pricing power, innovation speed, and channel access across the industry.
Innovation and Event Dynamics Shaping 2026
The flow of innovation in this sector is accelerated by trade shows and industry gatherings that serve as barometers for technological and market trends. The International Pool Spa Patio Expo in late 2025 demonstrated the industry's commitment to sustainability and product diversity, featuring participation from 40 countries and innovations across over 100 categories. Highlights included advancements in robotic cleaners, filtration efficiency, automation interfaces, and sustainability initiatives designed to support the 2026 buying cycle. Such events underscore the industry's pivot toward solutions that address energy consumption, water conservation, and operational ease.
Corporate activity in early 2026 further illustrates the dynamic nature of the market. Latham Group's recent activities, including the introduction of new deluxe plunge pools and strategic partnerships, reflect a focus on premiumization and brand visibility. Concurrently, Pool Corporation's retail summit showcased new chemical systems and exclusive partnerships with innovative solution providers, signaling a distributor-led push toward differentiated service offerings and proprietary product lines. These developments suggest that competitive advantage in 2026 will increasingly derive from the ability to bundle equipment with consumables, offer service-integrated solutions, and leverage exclusive channels to capture customer loyalty.
Strategic Imperatives for Decision Makers
As organizations prepare their strategies for the remainder of 2026 and beyond, several imperatives emerge from the current market intelligence. First, supply chain resilience must be prioritized. The tariff environment requires a rigorous review of sourcing strategies, with potential benefits to be gained from regionalizing production or securing long-term contracts that hedge against input cost volatility. Second, product portfolios should be evaluated through the lens of total cost of ownership for the end customer. As energy and water costs rise, solutions that deliver operational savings will command premium positioning and drive adoption.
Third, the recurring revenue potential in chemicals and maintenance tools should not be underestimated. With residential owners spending significantly on annual maintenance, businesses that can capture this recurring stream through subscription models, smart dosing systems, or service partnerships will build more predictable revenue bases. Fourth, competitive positioning requires clarity on where to compete. The market concentration data suggests that while leaders hold significant share, there are viable paths for specialists, particularly in high-growth segments like robotic cleaning and automation. Finally, geographic strategy must be nuanced. Growth rates and regulatory environments vary widely, and a one-size-fits-all approach risks misallocation of resources.
Conclusion: The Value of Deep Intelligence
The Worldwide Pool and Spa Supplies Market is evolving under a complex set of forces that demand more than superficial analysis. From the impact of trade policies on manufacturing costs to the shifting preferences of residential consumers and the strategic maneuvers of key competitors, the variables influencing success are numerous and interdependent. Our report provides the depth, granularity, and forward-looking perspective required to navigate this environment with confidence.
By accessing the full research, stakeholders will gain access to detailed segmentation analysis, precise regional forecasts, competitive benchmarking, and scenario models that quantify the impact of regulatory and economic variables. The insights contained within are designed to support critical decisions regarding market entry, product development, M&A targeting, and capacity planning. In a market projected to exceed 26 billion USD by 2032, the cost of incomplete intelligence is far greater than the investment in comprehensive analysis.
We invite you to explore the full report to unlock the specific data points, strategic frameworks, and actionable recommendations that will empower your organization to thrive in the dynamic world of pool and spa supplies. The currents are strong, but with the right intelligence, your strategy can not only withstand them but harness them for sustained growth.
For detailed analysis of this topic, please visit the official page: Worldwide Pool and Spa Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com