

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Military Grade Computer Market Hits $10.5B in 2025, Heading to $16.26B by 2032

Global Resilience: Strategic Imperatives in the Worldwide Military Grade Computer Market (2026-2032)
The defense technology landscape has entered a decisive phase. As geopolitical tensions reshape procurement priorities and operational theaters demand greater computational sovereignty, the Worldwide Military Grade Computer Market stands at a critical inflection point. For executives navigating procurement, R&D allocation, and supply chain resilience, understanding the trajectory of this sector is no longer optional—it is foundational to strategic readiness.
Based on our latest comprehensive analysis, the market is projected to expand from a base of approximately $10,500 million in 2025 to $16,263.31 million by 2032, reflecting a compound annual growth rate of 6.45%. This growth is not merely a function of increased defense spending; it represents a structural transformation in how militaries compute, process data, and maintain operational continuity under extreme conditions. Our freshly released Worldwide Military Grade Computer Market report dissects this evolution with granular precision, offering decision-makers a roadmap through a sector where mission assurance and technological agility must coexist.
A Market Anchored in Operational Necessity
Military-grade computing differs fundamentally from commercial IT markets. Where enterprise buyers optimize for cost and convenience, defense procurement prioritizes survivability, interoperability, and compliance with rigorous environmental and electromagnetic standards. The market's trajectory reflects a dual engine: modernization of legacy platforms and deployment of next-generation capabilities across ground, airborne, and naval domains.
Between 2020 and 2025, cumulative expansion demonstrated resilience even amid supply chain disruptions and component scarcity. In 2020, the market stood at $7,681.76 million; by 2025, that figure reached $10,500.0 million. The forecast period ahead compounds this momentum, with annual valuations climbing steadily toward 2032. This sustained trajectory signals that defense organizations are treating rugged computing not as a tactical utility but as a strategic asset class—one that directly enables command, control, communications, computers, intelligence, surveillance, and reconnaissance (C4ISR) functions across contested environments.
Yet raw valuation figures only tell the opening chapter. The substance of this market lies in how spending is distributed across form factors, platforms, and geographies, and how competitive dynamics are being reshaped by technological standards, regulatory frameworks, and raw material availability. Our report provides the full map; what follows is a strategic preview of the terrain.
Segmentation Dynamics: Where Value Concentrates
The military computing ecosystem bifurcates across three analytical dimensions—type, platform, and region—each carrying distinct investment and risk implications. In terms of product architecture, embedded systems and rugged mobile platforms represent the dominant expenditure categories, reflecting a shift toward distributed, edge-capable hardware that can operate independently of stable infrastructure. Servers and storage units, while smaller in absolute terms, are gaining strategic relevance as data-intensive battlefield architectures demand localized processing for latency-sensitive decision loops. Wearable and handheld computers further illustrate how soldier-system digitization is pushing computing intelligence into the tactical edge.
Platform-wise, ground-based systems currently command the largest share of compute investment, supported by the breadth of land-vehicle modernization programs worldwide. Airborne applications follow closely, driven by avionics upgrades, unmanned aerial system payloads, and cockpit digitization initiatives that demand SWaP-optimized rugged hardware. Naval platforms round out the triad, where corrosive marine environments and electromagnetic compatibility requirements impose particularly stringent qualification barriers.
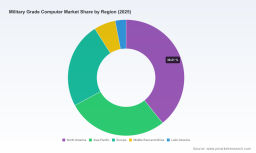
Geographically, the market displays pronounced concentration patterns. North America remains the most mature and investment-dense region, underpinned by sustained U.S. procurement cycles and export opportunities. Asia Pacific exhibits the strongest growth momentum, reflecting regional security reassessments and indigenous platform development. Europe maintains a stable, capability-focused demand profile, while Middle East & Africa and Latin America represent smaller but strategically significant deployments tied to specific modernization programs and allied cooperation frameworks.
Crucially, these segmentation dynamics are not static. They are being recalibrated by procurement policies, interoperability mandates, and supply chain constraints that differ dramatically across regions. The complete segmentation architecture—including revenue allocations, growth rate differentials, and sub-segment crossover effects—is mapped in detail within the report, where clients can identify which nodes of the value chain offer the highest strategic leverage for their specific business posture.
Competitive Architecture: Specialists, Integrators, and the Premium Tier
The competitive field in military-grade computing is characterized by a blend of incumbent defense electronics integrators, specialized rugged hardware manufacturers, and cross-over commercial entities that have adapted their platforms to defense specifications. Market concentration metrics indicate a moderately consolidated landscape, with the top three players holding approximately 34.2% of total market revenue and the top five accounting for roughly 51.85%. This structure suggests room for both established leaders and agile entrants who can meet qualification thresholds and deliver differentiated performance in harsh environments.
Several organizations define the sector's competitive contours. Curtiss-Wright Corporation exemplifies the mission-computer modernization playbook, with recent contract awards focused on MOSA-aligned computing architectures and platform upgrades for aircraft such as the U.S. Air Force C-17. Leonardo DRS has built a formidable position as a premier supplier of rugged military computer systems and displays, with sole-source battle management responsibilities and a portfolio exceeding 200,000 battle-proven systems qualified to military standards. General Dynamics and Northrop Grumman extend the integrator dimension, embedding rugged computing within broader mission systems and defense electronics portfolios for ground, naval, and airborne applications.
Private and multinational specialists further diversify the ecosystem. Getac Technology Corporation leverages MIL-STD-810H certified rugged platforms and COTS-aligned customization to serve defense applications in extreme conditions. Panasonic's Toughbook line brings commercial-hardened portability into field operations meeting military durability standards. Crystal Group, Mercury Systems, Kontron, and Extreme Engineering Solutions address embedded, VPX, and COM Express requirements, each emphasizing secure, size-weight-and-power-optimized architectures for mission-critical applications. MilDef Group, Neousys Technology, RuggON, and VarTech Systems contribute certified rugged computers and displays tuned to environmental and electromagnetic demands, while Wolf Advanced Technology, Acura Embedded Systems, Core Systems, and BAE Systems broaden the geographic and application footprint of rugged computing solutions across command, control, and connectivity environments. Elbit Systems Ltd. rounds out this cohort with integrated rugged computing and C4ISR offerings.
Recent developments underscore how product launches and program wins continuously reshape battlefield relevance. In March 2026, VersaLogic Corporation introduced the Raptor, an ultra-compact rugged embedded computer utilizing 13th Generation Intel processors designed for defense, edge, and uncrewed systems. The same month, Curtiss-Wright secured the selection to modernize U.S. Air Force C-17 mission computing with MOSA-aligned mission computers. In November 2025, Getac highlighted customized rugged military computer solutions in alignment with U.S. DoD COTS directions and MIL-STD-810H standards. These events are not isolated; they are indicators of the pace and precision with which competitive advantage is being contested.
The full competitive analysis in our report includes organizational profiles, strategic positioning, capability emphasis, and recent activity tracking across the key company set, enabling clients to benchmark partnership potential, competitive threats, and white-space opportunities with greater confidence.
Technology, Standards, and Regulatory Gravity
Military-grade computers do not succeed on performance alone. Qualification, certification, and regulatory compliance form the invisible scaffolding of this market. MIL-STD-810H remains the active standard for environmental testing, governing how rugged systems endure vibration, shock, temperature extremes, humidity, and particulate intrusion. Compliance with this standard, alongside electromagnetic compatibility requirements and platform-specific qualification processes, dictates not only product design but also time-to-field and qualification cost.
Parallel to technical standards, regulatory frameworks exert substantial influence over market behavior. The U.S. Department of Defense maintains ITAR and export control frameworks under 22 CFR Part 124 for defense services and technical data related to military computing systems. These controls shape global supply networks, partnership models, and cross-border technology transfer. They also create differentiated market access pathways, where companies with robust compliance infrastructure and secure manufacturing footprints enjoy structural advantages.
Supply-side risks add another layer of complexity. Recent years have highlighted the vulnerability of defense electronics to critical mineral and semiconductor-grade material disruptions. China's imposition of export controls and bans on gallium, germanium, and antimony—materials integral to semiconductors and defense electronics—has rippled through supply chains. The United States remains 100% import-reliant on gallium and approximately 85% reliant on antimony, with critical mineral shortages threatening defense production capacity for electronics including military computers. Rare earth elements face even broader concentration risks, with China dominating more than 90% of global processed rare earths used in military computing components. These realities are pushing procurement organizations and manufacturers alike toward diversification, stockpiling strategies, and qualification of alternative material pathways.
For companies operating in this space, regulatory and supply chain fluency is as important as engineering excellence. The report integrates these dynamics into market projections and competitive interpretation, helping clients anticipate how standards, controls, and raw material availability will shape pricing, lead times, and regional accessibility over the 2026-2032 horizon.
Strategic Reading for the 2026 Decision Cycle
As organizations finalize multi-year investment plans, three priorities emerge from the market's current trajectory:
- Platform modernization is cumulative, not cyclical. Mission computing refresh cycles span years, and programs winning today's milestones will influence demand well beyond the forecast window. Decision-makers should evaluate where their offerings align with active modernization campaigns across air, land, and sea domains.
- Certification is a moat, not a checkbox. MIL-STD compliance, ITAR readiness, and SWaP optimization are table stakes for credibility. Yet the differentiation point increasingly lies in how quickly and reliably these attributes can be demonstrated across product families and customization requests.
- Supply chain resilience has become a procurement criterion. With critical mineral concentration and export controls affecting component availability, buyers are factoring supplier geographic diversification, stock strategies, and alternative-material roadmaps into sourcing decisions. Companies that can articulate and deliver resilience will capture disproportionate influence in qualified vendor lists.
These themes are explored across every section of the report, from market sizing and segmentation to competitive profiling and regulatory context. The objective is not to present a static snapshot but to equip leadership teams with a decision-grade intelligence framework for 2026 and the years ahead.
Worldwide Military Grade Computer Market
Inside the Report: What Decision-Makers Will Gain
Our Worldwide Military Grade Computer Market study is structured to convert complex datasets into actionable strategic insight. Readers will find:
- A full historical and forecast market valuation series, anchored in consistent methodology and expressed in U.S. dollars, enabling revenue planning, benchmarking, and scenario modeling across the 2020-2025 historical window and the 2026-2032 forecast period.
- Detailed segmentation analysis across type, platform, and region, revealing where spending concentrates and how growth velocities differ by category and geography.
- Competitive landscape mapping with company profiles, capability summaries, and recent development tracking, providing a clear view of who is winning programs, launching products, and shaping standards adoption.
- Contextual analysis of regulatory frameworks, qualification standards, and raw material supply dynamics, integrated directly into market interpretation rather than treated as separate appendices.
- Identification of value-chain leverage points, enabling clients to prioritize market-entry pathways, partnership structures, and R&D investments in line with verified demand signals.
The report is intended for executives who require more than directional intuition. It is designed for teams that must justify capital allocation, align product roadmaps with procurement realities, and assess competitor moves against a quantified market baseline.
Access the Full Intelligence
The trajectory of the worldwide military grade computer market is being written now, in program offices, test ranges, and supply chain corridors around the world. To navigate it successfully, organizations need more than high-level estimates; they need precise segmentation, competitive granularity, and the strategic context to interpret change as it happens.
This article has outlined the strategic logic and the macro-scale direction of the market, but the full dataset, segmentation detail, company-level analysis, and scenario-ready forecasting are reserved for clients who engage directly with the complete study. The comprehensive intelligence—built to inform procurement strategy, market entry planning, and competitive positioning throughout 2026 and into 2032—is available through our official research portal.
For a market where mission assurance and technological adaptation determine outcomes, clarity is not a luxury. It is an operational requirement. We invite decision-makers to access the full report and equip their teams with the depth required to act decisively in the years ahead.
Embedded Computer Market
For detailed analysis of this topic, please visit the official page: Worldwide Military Grade Computer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com