

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Machine-Direction Orientation Films Market Hits $6.37B in 2025, 5.76% CAGR to 2032

Strategic Imperatives in the Worldwide Machine-Direction Orientation Films Market: A 2026 Outlook
The global packaging industry is undergoing a structural transformation driven by sustainability mandates, recyclability requirements, and the relentless pursuit of material efficiency. At the heart of this shift lies the machine-direction orientation (MDO) films market, a critical enabler of mono-material flexible packaging solutions that are increasingly mandated by regulatory frameworks and valued by brand owners. For enterprise decision-makers navigating the 2026 landscape, understanding the trajectory, competitive architecture, and value pools of this market is not optional—it is a strategic necessity. This article introduces the key findings and analytical scope of the latest Worldwide Machine-Direction Orientation Films Market study, positioning this intelligence as a foundational tool for capital allocation, supply chain strategy, and competitive positioning through the end of the decade.
From a macroeconomic perspective, the market has demonstrated consistent, compounding growth over the past half-decade. Revenue expanded from approximately $4.85 billion in 2020 to an estimated $6.37 billion in 2025, reflecting a steady upward trajectory that underscores the technology's transition from a niche specialty to a mainstream packaging substrate. The study projects this momentum to continue unabated through the forecast horizon, culminating in a market valuation approaching $9.42 billion by 2032. This expansion is underpinned by a compound annual growth rate of 5.76 percent, a figure that places MDO films in a favorable growth bracket relative to broader commodity polymer markets. For strategy teams, this growth profile signals durable demand drivers rather than cyclical fluctuations, warranting long-term capacity planning and technology investment considerations.
The Strategic Architecture of the Study
A market research report is only as valuable as its actionable granularity. This study is engineered to move beyond top-line sizing and deliver a granular, operation-ready intelligence framework for packaging converters, resin producers, equipment manufacturers, and brand owners. The analytical architecture is built around four interconnected pillars, each designed to translate market dynamics into executable strategic options.
1. Segmentation Dynamics and Value Pool Mapping
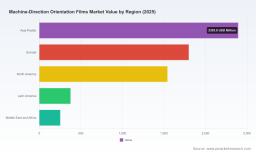
The report conducts a comprehensive decomposition of the market across material grades, application verticals, and geographic territories. By isolating consumption patterns, growth velocities, and structural shifts within each segment, the analysis reveals where margin pools are forming and where substitution risks are materializing. For instance, the material spectrum is evaluated across polyethylene, polypropylene, polyester, and polyamide-based substrates, with a focused lens on how mono-material architecture is reshaping share dynamics. Application-level scrutiny spans food and beverage packaging, personal care and hygiene, industrial and labeling uses, and medical and healthcare segments, mapping how regulatory pressure, barrier performance requirements, and conversion economics diverge across these end markets. Geographic dispersion is similarly mapped across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, contextualizing capacity footprints, trade flows, and regional regulatory calendars within a unified growth narrative.
High Barrier Mdo Pe Film Market
2. Competitive Landscape and Capability Benchmarking
Understanding who shapes the market—and how—is central to formulating winning strategies. The study profiles the leading participants that define production standards, drive technology diffusion, and influence commercial terms across the value chain. These include Charter Next Generation, RKW Group, Polifilm Extrusion, Trico Specialty Films, Avery Dennison, Coveris, Borealis, Longdapac, Cloud Film, Jiangsu Qianrun New Material Technology, Amcor, NOWOFOL, Lenzing Plastics, Futamura, Toray Industries, and Polysack Plastic Industries, among others. Rather than presenting a static directory, the report evaluates each player's technological positioning, product architecture, geographic reach, and strategic emphasis on recycle-ready, mono-material, and high-barrier film systems. This competitive mapping enables clients to identify white-space opportunities, assess supplier consolidation risks, and anticipate pricing and capacity dynamics in their respective niches.
3. Recent Developments and Capability Investments
Market structure is not static; it is being actively rewritten by capital investments, technology launches, and process innovations. The report integrates a detailed chronology of recent developments that signal where the industry's capability frontier is expanding. Notable moves include Charter Next Generation's deployment of new 9-layer and 5-layer extrusion lines equipped with MDO technology to scale high-barrier, recycle-ready film output; Amcor's operational launch of a new MDO line in Peru to extend the global reach of its AmPrima Plus recycle-ready portfolio; Reifenhäuser's presentation of MDO Ultra Stretch technology at K 2025, showcasing an ultra-thin, process-stable all-PE MDO film architecture with EVOH barrier for mono-material packaging; and Constantia Flexibles' multi-million-euro investment in a 5-layer blown film line with inline MDO to advance PE-based mono-material structures. These developments are cataloged with source attribution and strategic interpretation, allowing readers to trace the cadence of investment and infer where competitive advantages are being built.
Worldwide Machine-Direction Orientation Films Market
4. Market Dynamics, Regulatory Catalysts, and Input Cost Pressures
No strategic assessment is complete without a rigorous examination of the forces that will amplify or constrain growth. The study embeds a dynamic analysis of the regulatory environment, raw material economics, and compliance requirements that shape procurement and conversion decisions. On the regulatory front, the tightening trajectory of the European Packaging and Packaging Waste Regulation (PPWR) is accelerating the adoption of MDO technology as a pathway to mono-material recyclability, with compliance expectations intensifying from 2030 onward. Concurrently, food-contact safety remains a non-negotiable constraint, with MDO-PE films for food packaging required to align with U.S. FDA 21 CFR standards and equivalent global material safety regulations.
On the input side, the report contextualizes the volatility and directionality of key feedstocks. Polypropylene, a critical resin for many MDO film grades, has experienced price movements tied to contract settlements, plant turnarounds, and regional supply disruptions. Price dynamics in North America and Northeast Asia are tracked alongside far-east Asian spot indicators, providing a nuanced view of cost pressures that converters and resin suppliers must factor into pricing strategy and margin management. These dynamics are not presented in isolation; they are woven into a broader narrative that explains how raw material trajectories, regulatory calendars, and consumer-brand sustainability commitments interact to define the operating environment for MDO film producers and converters.
The Competitive Arena: Who Shapes the MDO Films Market
The MDO films market is characterized by a moderately concentrated competitive structure, with the top three participants accounting for approximately 18.45 percent of collective revenue and the top five representing roughly 27.6 percent. This fragmentation beyond the leading tier indicates a market where regional specialization, application-specific expertise, and technology differentiation play decisive roles. The study's competitive analysis goes beyond market share arithmetic to evaluate the strategic postures of the key companies that define the market's technological and commercial contours.
In North America, Charter Next Generation has positioned itself as a technology-forward producer of high-barrier, recycle-ready MDO-PE films, exemplified by its GreenArrow portfolio and its investments in advanced multi-layer MDO lines that support matte-finish print substrates and mono-material packaging architectures. Trico Specialty Films complements this regional landscape with its monoaxially-oriented MOPP and MOPE offerings, including the ENVIRITE line tailored for mono-material packaging needs. Avery Dennison contributes to the competitive fabric with high-clarity MDO films serving label and flexible packaging applications, leveraging brand recognition and conversion expertise to embed its products within broader packaging ecosystems.
Europe hosts a dense cluster of capable producers and material innovators. RKW Group manufactures MDO films, barrier films, and complementary solutions with a focus on flexible packaging applications, while Polifilm Extrusion offers POLIPURE MDO PE films—available with or without EVOH barrier—that serve as printing substrates and mono-material packaging components designed to replace conventional PET, OPP, and OPA structures. NOWOFOL provides NOWOSTRAIGHT MDO films engineered for flexible stand-up and retort pouches in food packaging, and Lenzing Plastics extends its portfolio into industrial and packaging applications with LDO film solutions. Coveris, headquartered in Vienna, develops MDO films that balance sustainability credentials with high-performance flexible packaging requirements, while Borealis acts as a critical upstream enabler by supplying resins and technical support that underpin recyclable mono-material film production. Constantia Flexibles' recent investment in inline MDO technology further illustrates how the European value chain is integrating orientation capabilities to deliver PE-based mono-material structures such as EcoLamHighplus.
In Asia, the competitive landscape reflects both scale and rapid capability accumulation. Longdapac produces high-barrier MDO-PE films for recyclable flat-bottom and stand-up pouches, addressing the demands of modern retail and e-commerce packaging formats. Cloud Film and Jiangsu Qianrun New Material Technology round out the regional profile by supplying MDO PE films within broader oriented film portfolios that also encompass BOPP, BOPET, and related substrates. Amcor's global footprint, including its recent Peru-based MDO line expansion for AmPrima Plus recycle-ready films, demonstrates how multinational packaging leaders are extending MDO capabilities across Latin America and other growth markets to serve brand-owner sustainability commitments at scale. Additional participants such as Futamura, Toray Industries, and Polysack Plastic Industries contribute specialized MDO film solutions that span sustainable packaging, high-performance applications, and flexible packaging formats, reinforcing the depth and diversity of the global competitive set.
The strategic implication for clients is clear: competitive advantage in this market is increasingly derived from the ability to deliver mono-material, recycle-ready, high-barrier film systems with consistent processability and compliance assurance. Suppliers and converters that align their capabilities with these priorities—and that can navigate regional regulatory requirements and input cost volatility—are best positioned to capture share in a market that rewards technological integration and sustainability performance.
Market Dynamics: The Forces Reshaping 2026 and Beyond
The MDO films market does not evolve in a vacuum. Its trajectory is being shaped by an interlocking set of regulatory, economic, and technological forces that demand proactive strategic management. Three dynamics stand out as particularly consequential for 2026 decision-making.
Regulatory pressure as a technology accelerant. The global movement toward packaging recyclability is no longer a directional preference—it is becoming a compliance requirement. Stricter EU PPWR requirements on packaging recyclability, effective from 2030, are driving material substitution toward mono-material structures that can be efficiently recycled within existing streams. MDO technology is central to this transition because it enables polyethylene-based and polypropylene-based films to achieve the barrier performance, strength, and sealability required for demanding applications while preserving recyclability. In this context, MDO films are transitioning from a performance upgrade to a regulatory compliance pathway, which elevates their strategic importance for packaging portfolios targeting European and increasingly global markets.
Input cost volatility and margin resilience. The economics of MDO film production are sensitive to resin pricing, particularly for polypropylene and polyethylene grades that serve as primary feedstocks. Recent price movements—including increases tied to polymer-grade propylene contract settlements, plant turnarounds, and Middle East supply disruptions—illustrate the exposure that converters and resin suppliers face to commodity cycles and regional supply shocks. With polypropylene spot prices in far-east Asian markets experiencing notable upward movement and North American prices reacting to contract dynamics, margin management has become a central operational challenge. The study contextualizes these movements within a broader framework, helping clients anticipate cost trajectories, evaluate contract structures, and assess how input cost fluctuations may influence pricing power and competitive positioning across segments.
Compliance complexity as a market barrier and differentiator. Food-contact compliance and material safety are non-negotiable requirements that shape both product development and market access. MDO-PE films destined for food packaging must satisfy U.S. FDA 21 CFR standards and analogous global regulations, creating a compliance layer that raises the barrier to entry for undifferentiated producers while rewarding those with established quality systems and regulatory expertise. This dynamic reinforces the value of scale, technical capability, and compliance assurance in the competitive hierarchy, and it underscores why the study's analysis of regulatory requirements is integrated directly into its market dynamics assessment rather than treated as a peripheral footnote.
Why This Study Matters for 2026 Decision-Making
Enterprise strategies for 2026 cannot be built on generalized market narratives or lagging indicators. They require forward-looking, segment-aware intelligence that connects market sizing to the operational and competitive realities that drive value creation. This study is designed to meet that requirement. It provides a rigorously quantified baseline of market size and growth, a detailed segmentation map that reveals where growth and margin are concentrated, a competitive profiling framework that clarifies capability leadership and strategic positioning, and a dynamics assessment that anticipates the regulatory and economic forces most likely to alter the operating environment.
For converters evaluating capacity investments, the study offers context on where demand is structurally expanding and which film architectures are gaining commercial traction. For resin producers and equipment suppliers, it clarifies the technology requirements and application pulls that will shape procurement and co-development priorities. For brand owners and packaging specifiers, it illuminates the trade-offs between material performance, recyclability, compliance, and total cost, enabling more informed sourcing and portfolio decisions. In each case, the study's value lies in its ability to translate market data into strategic implication—turning size, share, and growth figures into actionable intelligence that informs capital deployment, supplier selection, and market-entry timing.
Navigating the Intelligence: What the Full Report Unlocks
This article has outlined the strategic contours of the Worldwide Machine-Direction Orientation Films Market and the analytical scope of the accompanying study. It has demonstrated the growth momentum, the competitive diversity, and the dynamic forces that make this market a critical consideration for 2026 planning. Yet the full depth of the intelligence—precise segment sizing, regional and application-level breakdowns, competitive capability comparisons, detailed investment chronologies, and forward projections through 2032—is contained within the complete report. For executive teams, strategy functions, and commercial leaders who require the granularity needed to validate investment theses, calibrate supply strategies, and benchmark competitive positioning, the full study provides the comprehensive evidence base that high-stakes decisions demand.
The Worldwide Machine-Direction Orientation Films Market is entering a phase in which technological capability, regulatory alignment, and sustainability performance will increasingly determine competitive outcomes. Organizations that equip themselves with detailed, forward-looking intelligence will be better positioned to anticipate shifts, seize opportunities, and manage risks in a market that rewards precision and strategic foresight. The complete report delivers that intelligence in a structured, decision-ready format, and it is available for access through our research portal for teams seeking to translate market insight into executable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Machine-Direction Orientation Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com