

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 15.2mm Steel Strand Market to Reach $3,558.62 Million by 2032, 4.5% CAGR Outlook

Navigating the 15.2mm Steel Strand Market: Strategic Intelligence for 2026 and Beyond
The global infrastructure landscape is undergoing a period of calibrated transformation. As public and private capital converge on resilient transport networks, energy transition assets, and next-generation urban development, the demand for high-performance prestressing materials has entered a decisive phase. At the center of this shift sits the 15.2mm steel strand segment, a critical enabler of structural integrity across bridges, highways, commercial and residential buildings, and heavy industrial infrastructure. Our newly released market research provides a comprehensive, decision-grade appraisal of this segment, engineered specifically to guide corporate strategy, capital allocation, and competitive positioning through the 2026 to 2032 forecast horizon.
For executives, procurement leaders, and strategic planners, the core value of this study lies not in macro-level commentary, but in actionable intelligence. The report synthesizes historical performance from 2020 through 2025 with a rigorous forward-looking framework, translating complex supply-demand dynamics into clear strategic waypoints. By grounding analysis in verified pricing mechanisms, compliance trajectories, and capacity deployment patterns, we enable organizations to anticipate market inflection points rather than merely react to them.
Market Architecture and Growth Trajectory
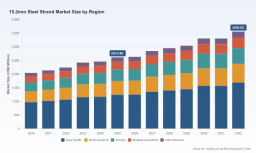
The 15.2mm steel strand market has demonstrated consistent expansion across the historical evaluation window. Total market revenue grew from approximately 2,045 million USD in 2020 to an estimated 2,615 million USD by 2025, reflecting an annualized expansion rate of roughly 4.5 percent over the past half-decade. This momentum carries into the near-term forecast, with the market projected to reach 2,633 million USD in 2026 before accelerating into the late 2020s and early 2030s. By 2032, market valuation is anticipated to approach 3,559 million USD, underscoring a sustained, infrastructure-led demand cycle.
It is important to recognize that this growth profile is not uniformly distributed across segments or geographies. Our analysis isolates the structural drivers behind this trajectory, examining how regional development priorities, infrastructure investment pipelines, and material substitution patterns interact to shape total addressable demand. Rather than presenting static snapshots, the report maps the evolving interplay between civil engineering megaprojects, energy sector expansion, and the broader construction ecosystem. This layered approach allows decision-makers to understand not only where the market is heading, but why it is moving along that path.
Pricing behavior within this segment is inherently sensitive to upstream inputs and macroeconomic conditions. Fluctuations in high-carbon steel wire rod costs, shifts in regional market conditions, and evolving regulatory frameworks all contribute to periodic price recalibrations. By tracking these variables through a structured analytical lens, the report equips stakeholders with the visibility needed to negotiate contracts, manage inventory exposure, and align procurement timelines with anticipated price regimes.
Core Report Scope and Operational Deliverables
This research is designed as a practical strategic toolkit rather than a conventional market summary. The full publication delivers granular breakdowns across material classifications, end-use verticals, and geographic corridors, paired with forward-looking scenario modeling that accounts for both baseline growth and disruptive variance. Readers will gain access to:
- A detailed segmentation analysis covering uncoated, galvanized, and epoxy-coated strand formats, with specific attention to performance differentials, application suitability, and cost-structure implications.
- End-use demand mapping across bridges and highways, commercial and residential buildings, energy and industrial infrastructure, and ancillary construction applications, highlighting where volume concentration and growth acceleration are most pronounced.
- A regional demand assessment that situates market opportunity within local infrastructure pipelines, trade flows, and policy incentives, without relying on superficial geographic aggregations.
- An in-depth examination of regulatory and technical compliance requirements, including alignment with international standards governing tensile strength, low-relaxation properties, and corrosion-resistant specifications.
- Forward-looking forecasts that extend through 2032, incorporating base-case trajectories, sensitivity parameters, and structural risk factors relevant to supply planning and investment timing.
- Strategic recommendations tailored to manufacturers, distributors, specification engineers, and procurement teams seeking to optimize market exposure and competitive positioning.
The operational emphasis of the report ensures that findings are directly translatable into commercial strategy. Whether the objective is to evaluate capacity expansion, identify partnership opportunities, assess pricing power, or refine product mix strategy, the study provides the structured evidence base required to move from hypothesis to execution.
Competitive Landscape: Positioning, Capability, and Differentiation
The 15.2mm steel strand market features a diversified competitor base, with participation spanning specialized Chinese producers, established Japanese and Taiwanese manufacturers, and growing capacity bases in India and South Korea. Competition is increasingly defined by a combination of production scale, technical compliance, coating innovation, and geographic reach. Our competitive analysis evaluates the strategic posture of key market participants, mapping their capabilities against the evolving demands of infrastructure specifiers and procurement organizations.
Chinese manufacturers continue to anchor substantial portions of global supply, with multiple Tianjin-based and Shandong-based enterprises offering 15.2mm seven-wire ordinary and low-relaxation strand in strength grades including 1750 MPa, 1830 MPa, and 1860 MPa. Several of these producers have expanded their compliance footprints to align with GB/T5224, ASTM A416, and related international benchmarks, enabling broader access to bridge, structural, and photovoltaic bracket applications. Capacity deployment remains a differentiating factor, with select facilities operating at scale to support both domestic infrastructure programs and export shipments.
In India, producers are increasingly focused on uncoated stress-relieved and low-relaxation strand formats for prestressed concrete applications, supporting the country's expanding civil engineering and construction pipeline. Korean and Taiwanese participants bring a strong emphasis on standardized compliance across multiple international specifications, including ASTM A416, BS 5896, EN 10138, and JIS G3536, often with production calibrated to 1860 MPa tensile performance and low-relaxation requirements. These capabilities position them as credible suppliers for cross-border projects requiring multi-standard certification and consistent quality assurance.
15.2mm Steel Strand Market
Prestressed Concrete Strand Market
On the advanced materials front, select Japanese-linked operations have broadened their focus beyond standard strand formats to include epoxy-coated and filled ultra-high-strength prestressing solutions. Recent industry engagements have highlighted the technical rationale, testing protocols, and application cases for epoxy-coated PC strand in post-tensioned bridge systems, including 15.2mm configurations within multi-strand tendon arrangements. This trajectory signals a broader market movement toward corrosion-resistant and high-durability strand formats in environments where service-life extension and maintenance reduction carry significant economic weight.
Market concentration remains moderate, with competitive intensity distributed across a broad supplier base rather than consolidated around a narrow group of dominant players. This fragmentation creates both opportunity and complexity. Buyers benefit from multiple sourcing pathways and comparative pricing leverage, while suppliers must differentiate through technical reliability, compliance breadth, logistics efficiency, and customer-specific engineering support. The report's competitive assessment provides a structured framework for evaluating these dynamics, allowing organizations to identify where incumbency advantages exist, where substitution risk is rising, and where partnership or acquisition strategies may yield disproportionate strategic value.
Industry Dynamics, Standards, and Material Innovation
Several structural forces are reshaping the operating environment for 15.2mm steel strand suppliers and buyers alike. At the material level, pricing behavior is closely tied to the cost trajectory of high-carbon steel wire rods, which serves as the foundational input for strand production. Periodic volatility in raw material costs, combined with shifting market conditions and policy-driven demand signals, introduces a layer of pricing uncertainty that must be managed proactively. Organizations that integrate input-cost monitoring into their procurement and pricing strategies are better positioned to protect margins and maintain supply continuity during periods of market recalibration.
On the compliance side, regulatory and standards alignment continue to play a defining role in market access. Epoxy-coated prestressing strand configurations for 15.2mm applications are evaluated against ASTM A882/A882M-2020 and ISO 14655 frameworks, while broader prestressing strand specifications are benchmarked to GB/T5224, ASTM A416, BS 5896, EN 10138, and JIS G3536, particularly where 1860 MPa tensile strength and low-relaxation characteristics are specified. These standards do more than define technical minimums; they function as commercial gateways, influencing procurement eligibility, specification approval, and cross-border trade feasibility. The report maps these compliance pathways in detail, helping stakeholders understand which certifications are becoming table stakes and where additional specification alignment can open new project pipelines.
A parallel dynamic is the growing emphasis on durability-enhancing strand formats. As infrastructure assets face more demanding environmental exposure profiles and longer design-life expectations, corrosion protection and coating integrity have moved from niche considerations to central procurement criteria in many bridge and industrial applications. This shift is prompting both specification changes and product development responses, with epoxy-coated and related protective formats gaining traction where lifecycle cost arguments outweigh initial material premiums. The research evaluates this transition from both a demand-side and supply-side perspective, identifying where adoption is accelerating and what technical or commercial barriers remain.
Strategic Value for 2026 Decision-Making
As organizations move deeper into the 2026 planning cycle, the imperative is to replace assumption-led forecasting with evidence-backed scenario planning. The 15.2mm steel strand market is large enough to absorb incremental capacity, yet specialized enough to reward players who understand specification nuances, regional procurement behavior, and the technical differentiators that shape bidding outcomes. This report is built to support that level of strategic precision.
For manufacturers and material suppliers, the study offers a clear view of where demand concentration is forming, which product formats are gaining specification share, and how compliance portfolios influence competitive reach. For distributors and trading entities, it provides visibility into regional demand rhythms, price-setting dynamics, and the shipment patterns that underpin reliable supply commitments. For engineering firms, contractors, and procurement teams, it delivers a structured basis for evaluating supplier capability, anticipating material availability, and aligning project timelines with realistic market conditions.
Crucially, the report does not merely describe where the market has been; it translates historical patterns and forward indicators into decision-oriented implications. By connecting market size evolution, segmentation behavior, competitive capability, and regulatory trends into a unified analytical narrative, we enable leaders to test strategy against multiple plausible futures rather than betting on a single linear projection.
Accessing the Full Intelligence Package
The insights summarized here represent the strategic framework of our latest market research, but the full analytical depth, quantitative breakdowns, competitive profiles, and forecast modeling reside within the complete report. To support rigorous planning and confident execution, we invite stakeholders to access the full publication, where detailed segmentation data, regional demand assessments, pricing dynamics, and company-level capability evaluations are presented in a format built for immediate commercial application.
In a market defined by infrastructure ambition, material differentiation, and evolving compliance expectations, the organizations that succeed will be those equipped with precise, forward-looking intelligence. This research is designed to provide exactly that foundation, enabling informed capital deployment, smarter sourcing strategy, and stronger competitive positioning as the 15.2mm steel strand market advances through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: 15.2mm Steel Strand Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com