

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tris (Clorisopropyl) Phosphate Market Size Hits $1050M in 2025, 4.82% CAGR Forecast to 2032

Strategic Imperatives in the Tris (Clorisopropyl) Phosphate Market Through 2032
The global landscape for Tris (Clorisopropyl) Phosphate, commonly known as TCPP, is entering a pivotal phase defined by intersecting regulatory pressures, supply chain realignments, and evolving end-use demands. For corporate strategists, procurement leaders, and investors, the window to shape positioning ahead of the 2026-2032 forecast horizon is narrowing. Our latest market research delivers a disciplined, data-grounded assessment of where value will concentrate, which operational levers will matter most, and how competitive dynamics will reward or penalize missteps in the years ahead.
Why the 2026 Decision Window Demands a Fresh Analytical Lens
The period between 2026 and 2032 is not a routine extrapolation of past growth patterns. It is a window shaped by compounding forces: raw material cost volatility that continues to anchor manufacturing economics, regulatory scrutiny that is reshaping compliance pathways across major consumption zones, and trade remedy actions that are rewiring cross-border sourcing logic. Companies that treat these variables as isolated risks will find themselves reacting to margin compression, supply disruptions, and market access constraints. Those that map them into an integrated strategy will be positioned to capture share, optimize input costs, and align product portfolios with the next generation of flame retardant requirements.
The market has demonstrated resilient upward trajectory over the recent historical period, with revenue climbing from 845.2 million USD in 2020 to an estimated 1050.0 million USD in 2025. The forecast horizon extends that trajectory, projecting revenues of approximately 1099.81 million USD in 2026 and reaching 1457.86 million USD by 2032. These figures reflect a compound annual growth rate of 4.82 percent, a pace that signals steady expansion rather than explosive disruption. Yet beneath that headline growth lies a more nuanced story: shifting grade preferences, application-specific demand drivers, regional sourcing recalibration, and competitive intensity that varies dramatically across market segments. Understanding which forces will accelerate, which will plateau, and where margin pools will form is precisely where strategic value is created or lost.
What This Market Research Delivers for Executive Decision-Making
This study is built for practitioners who need more than a macro summary. It is structured to translate market intelligence into actionable planning across commercial, procurement, regulatory, and competitive strategy functions. The report framework is designed to answer the questions that decision-makers face when evaluating capacity commitments, sourcing transitions, product development roadmaps, and market entry or expansion choices.
Tris (Clorisopropyl) Phosphate Market
The analysis begins with a rigorous market sizing and forecasting architecture that traces historical performance from 2020 through 2025 and projects forward across the 2026-2032 period. Rather than presenting aggregated numbers in isolation, the report embeds them within a framework that connects growth trajectories to underlying demand drivers, cost structures, and supply-side constraints. This ensures that forecast figures are interpretable in operational terms, not merely statistical outputs.
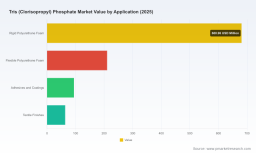
A central pillar of the research is the segmentation architecture, which decomposes the market along axes that matter for commercial planning. The report examines how demand splits across major geographic consumption zones and how those regional patterns intersect with trade flows, tariff exposure, and localization trends. It also evaluates the divergence between product grades, distinguishing high-purity offerings from standard-grade volumes, and connects those grade dynamics to application requirements in sectors such as rigid polyurethane foam, flexible polyurethane foam, adhesives and coatings, and textile finishes. By mapping where each segment derives its value and what constraints shape its growth, the analysis equips readers to assess which segments will command premium positioning and which will face intensified price competition.
Equally important is the operational and regulatory context woven throughout the study. The report addresses how feedstock economics, particularly the cost contribution of key production inputs such as propylene oxide, phosphorus oxychloride, and chlorine gas, influence manufacturing profitability and pricing behavior. It also examines the compliance landscape that is reshaping procurement decisions and product acceptance, including REACH self-classification considerations, TSCA evaluation developments, and the broader trajectory of halogenated flame retardant scrutiny. These factors are not treated as peripheral footnotes; they are integrated into the analytical narrative because they directly affect sourcing strategy, product qualification timelines, and long-term market access.
In addition to structural analysis, the research includes practical instruments for strategy development. The report provides a competitive benchmarking framework that compares incumbent suppliers and emerging entrants across dimensions such as capacity scale, grade specialization, regional footprint, regulatory readiness, and vertical integration. It also incorporates scenario-based considerations that help readers test strategic assumptions against plausible shifts in trade policy, input costs, and demand composition. The goal is to give executives a decision-ready toolkit rather than a static market snapshot.
Competitive Landscape: Scale, Specialization, and Strategic Realignment
The TCPP market is characterized by a broad supplier base, yet competitive advantage is increasingly determined by a smaller set of capabilities: cost-efficient production at scale, technical differentiation in high-purity or application-specific grades, regulatory documentation maturity, and the ability to serve as a reliable partner in formulation development. The report profiles the principal companies shaping this landscape and analyzes how their strategic posture positions them for the forecast period.
At the premium and technology-oriented end of the spectrum, global players such as ICL Group Ltd., Lanxess AG, and Clariant AG continue to reinforce their positions through vertically integrated supply chains, brand-recognition in flame retardant systems, and focused emphasis on high-purity grades for demanding applications. These companies are not simply selling commodity volume; they are competing on reliability, compliance readiness, and co-development with downstream formulators. ICL Industrial Products, for example, has been advancing specialized TCPP-based packages tailored to electric vehicle battery enclosure foam applications, signaling how product differentiation is extending into new performance-critical use cases. Lanxess continues to market TCPP through its additive portfolio with a clear orientation toward automotive, electronics, and polyurethane foam sectors, supported by full REACH compliance positioning. Clariant pursues a similar specialization strategy, emphasizing customized flame retardant packages developed in collaboration with system houses.
Albemarle Corporation maintains a notable presence in the North American market, supplying TCPP within its broader chlorinated flame retardant portfolio and targeting polyurethane foam and related polymer applications. Its role illustrates how global chemical companies leverage portfolio breadth and regional distribution strength to sustain market relevance even as specialized players compete on grade and technical service.
In Northeast Asia, Daihachi Chemical Industry Co., Ltd. represents a producer profile oriented toward electronics and automotive applications, with a focus on technical specifications that align with precision manufacturing requirements. This positions the company within a segment of the market where product consistency, documentation, and application support can matter as much as price.
A substantial portion of competitive dynamics, however, is shaped by the expanding Chinese manufacturing base. Companies such as Jiangsu Yoke Technology Co., Ltd., Zhejiang Wansheng Co., Ltd., Shandong Brother Sci. & Tech. Co., Ltd., Zhejiang Honghao Technology Co., Ltd., Taizhou Xin'an Flame Retardant Co., Ltd., Jiangsu Firex Chemical Co., Ltd., and Shandong Taixing New Material Co., Ltd. collectively contribute significant capacity and a wide range of commercial offerings. Some operators are investing in quality certifications and REACH documentation to strengthen export competitiveness, while others continue to compete aggressively on price in price-sensitive end markets across Asia and the Middle East. The report examines how this heterogeneity within the Chinese supplier base is influencing global pricing architecture, procurement options, and the risk-reward calculus for buyers weighing cost savings against compliance and quality assurance.
Distribution and intermediary players also play an important role in shaping market accessibility. Firms such as Wego Chemical Group, Riverland Trading, Silver Fern Chemical, The Chemical Company, and Valtris Specialty Chemicals provide specialized distribution, grade availability, and supply partnership structures that connect producers with end users across multiple regions. Valtris, for instance, has expanded collaboration with major Asian chemical groups to enhance TCPP availability in the U.S. and European markets, illustrating how distribution partnerships can function as strategic levers for supply diversification and market reach. SMC Global further exemplifies the evolving entry pathways into Western markets, introducing a TCPP and formulated flame retardant series manufactured in India with an emphasis on quality standards and regulatory compliance for the U.S. market. These developments show that the competitive map is not static; it is being reshaped by new manufacturing origins, partnership architectures, and targeted product launches.
The market concentration data underscores why competitive strategy matters. With the top three firms accounting for approximately 42.5 percent of market revenue and the top five reaching roughly 58.8 percent, the market retains meaningful fragmentation while still offering clear advantages to scale players and differentiated specialists. For buyers, this concentration profile shapes negotiation leverage, supply continuity planning, and supplier qualification strategies. For competitors, it defines the threshold at which scale, branding, or technical service can become decisive.
Regulatory, Trade, and Cost Forces That Will Shape Strategy
No strategic assessment of this market is complete without addressing the structural pressures that influence both supply economics and market access. Feedstock costs remain a central determinant of manufacturing economics. With key inputs comprising a substantial share of total production costs, fluctuations in propylene oxide, phosphorus oxychloride, and chlorine gas markets can quickly translate into pricing pressure and margin variability. The report examines how producers and buyers can anticipate these cost dynamics and structure contracts, sourcing strategies, and inventory planning accordingly.
On the regulatory front, the environment is evolving in ways that affect procurement confidence and product qualification timelines. TCPP has been subject to self-classification as a suspected human carcinogen under REACH registrant assessments following long-term study findings, and related regulatory attention continues to shape the broader flame retardant discourse. At the same time, distinct but related compounds have undergone their own risk evaluations under TSCA frameworks, reinforcing the importance of monitoring regulatory trajectories even when a given substance remains in active use. The report integrates these compliance considerations into commercial strategy, helping readers understand how documentation readiness, test data packages, and regulatory engagement can become competitive differentiators rather than mere administrative requirements.
Worldwide Tris (2-Ethylhexyl) Phosphate Market
Trade policy adds another layer of complexity. U.S. imports of TCPP from China remain subject to additional duty exposure under Section 301 tariff provisions, and recent affirmative trade remedy determinations concerning certain alkyl phosphate esters from China have heightened scrutiny on pricing practices and fair-value assessments. These developments are not abstract legal matters; they influence landed cost comparisons, supplier qualification logic, and the attractiveness of alternative sourcing regions. The research maps these trade dynamics against regional market structures so that readers can evaluate how tariff exposure, antidumping considerations, and supply diversification options interact in practical sourcing decisions.
How to Use This Research for 2026 Planning and Beyond
The strategic value of this study lies in its ability to connect market structure with decision logic. For procurement and supply chain leaders, the report provides a basis for evaluating sourcing portfolios, assessing the trade-offs between cost, compliance, and continuity, and identifying where supplier diversification or dual-sourcing can reduce exposure to tariff and trade remedy risk. For commercial and product strategy teams, it offers a framework for assessing which grade and application segments are likely to sustain premium positioning and where competitive intensity may compress returns. For market entry and expansion planning, it supplies context on regional demand patterns, regulatory readiness, and the competitive profiles of both established and emerging suppliers.
The research is also designed to support scenario thinking. Because the forecast period spans a volatile mix of cost, regulatory, and trade variables, the report helps readers test strategic options against multiple plausible futures rather than anchoring to a single baseline. Whether the objective is to defend margin, enter new application verticals, reposition a product portfolio, or restructure a sourcing footprint, the analysis is built to inform the choice set with evidence rather than assumption.
Next Steps
Full market sizing, segment analysis, competitive benchmarking, and scenario planning details are developed in depth within the complete report. Given the pace of regulatory developments, trade policy adjustments, and supplier innovation, the organizations that move earliest to align strategy with evidence will have the strongest position as the 2026-2032 cycle unfolds. We invite decision-makers to access the full study for the segmented data, company-level profiling, and operational recommendations needed to translate market insight into concrete action.
For detailed analysis of this topic, please visit the official page: Tris (Clorisopropyl) Phosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com