

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
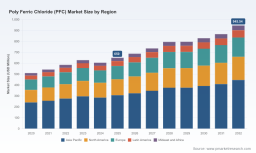
PW Consulting: Global Poly Ferric Chloride Market to Reach $945.54 Million by 2032 with 5.51% CAGR

Strategic Intelligence for the Poly Ferric Chloride Market 2026–2032
The global supply chain for advanced water treatment chemicals is entering a phase of structural recalibration. As municipal authorities, industrial operators, and environmental regulators tighten compliance standards, demand for high-performance coagulants has shifted from cyclical fluctuation to sustained, policy-driven growth. Poly ferric chloride (PFC) has emerged as a cornerstone chemical in this transition, offering superior flocculation efficiency, broader pH tolerance, and lower residual sludge generation compared to traditional aluminum-based alternatives. For executives navigating procurement, capacity planning, and geographic expansion in 2026 and beyond, market intelligence must move beyond backward-looking summaries and into actionable forecasting. This report delivers that precision.
The market valuation trajectory tells a clear story of maturation and steady acceleration. Tracing historical performance from 2020 through the base year of 2025, the sector has demonstrated consistent expansion, culminating in a 2025 baseline that anchors a robust forward projection. Over the forecast window extending through 2032, the market is positioned to compound at a measured yet resilient pace, translating into substantial revenue expansion across both established and emerging consumption hubs. The arithmetic is straightforward: baseline revenue scales into a multi-year growth pathway that rewards early movers with optimized pricing strategies, targeted capacity investments, and disciplined inventory positioning. Yet the headline figures only frame the opportunity. The real strategic leverage lies in understanding where value is being created, which operational levers are reshaping margins, and how competitive dynamics are reconfiguring market access.
Decoding Structural Shifts Across Forms, Applications, and Geographies
The architecture of PFC consumption is no longer monolithic. Procurement patterns now reflect a deliberate split between operational convenience and storage logistics, with buyers evaluating liquid formulations against solid or powder variants based on application scale, transportation cost structures, and on-site handling capabilities. This bifurcation influences not only end-user preference but also manufacturer product roadmaps, blending facility investments, and regional distribution networks. Simultaneously, the application landscape reveals a dominant concentration in centralized water purification, while secondary demand streams continue to gain traction in effluent management, industrial process clarification, and specialized manufacturing workflows. Each consumption vertical carries distinct regulatory exposure, seasonal procurement rhythms, and tolerance for chemical substitution, requiring analysts and buyers to map demand density rather than treat the market as a single aggregate.
Geographic distribution further complicates the demand picture. Consumption patterns distribute unevenly across major economic zones, with certain regions commanding disproportionate share due to infrastructure investment cycles, aging water network modernization programs, and localized production availability. Other territories are experiencing incremental but accelerating uptake as environmental discharge standards tighten and municipal budgets prioritize coagulant procurement over alternative treatment pathways. For strategic planners, this means that aggregate growth masks divergent regional realities. A volume expansion in one corridor may be offset by price compression in another, while supply chain routing, freight cost volatility, and import dependency ratios introduce hidden margin variables that only granular mapping can reveal.
Competitive Dynamics and the New Operational Radar
Market positioning in PFC is defined by a blend of established multinational chemical platforms, regionally anchored specialty producers, and export-oriented manufacturers scaling global distribution footprints. Leading European and North American firms continue to leverage integrated R&D programs, formulation optimization, and long-term municipal contracts to secure recurring revenue streams, while Asian manufacturers have expanded export capacity, refined production consistency, and targeted price-sensitive demand corridors. The competitive field remains moderately fragmented at the top tier, with concentration metrics indicating that no single group dominates the landscape outright. This dispersion creates room for strategic partnerships, selective acquisitions, and formulation-level differentiation rather than pure volume competition.
Recent corporate actions underscore how players are repositioning themselves ahead of the next demand cycle. One prominent European water treatment specialist expanded its production capacity for coagulant portfolios across its European operations, signaling confidence in sustained municipal and industrial procurement. In parallel, a major Asian chemical manufacturer introduced a high-purity PFC grade engineered for advanced wastewater treatment scenarios, reflecting a broader industry shift toward performance-tiered product lines that command premium positioning in regulated environments. These developments are not isolated events; they are indicators of where capacity, purity standards, and application-specific engineering are converging to reshape competitive benchmarks.
Supply-side realities further complicate strategic planning. Raw material input costs remain a persistent variable, with historical disruptions in key precursor markets having periodically rippled through manufacturer pricing structures. Regional price volatility for iron-based feedstocks and ancillary processing inputs has forced producers to tighten hedging strategies, renegotiate long-term contracts, and reinterpret pass-through mechanisms in customer agreements. On the regulatory axis, compliance frameworks in key import destinations have enforced stricter documentation, safety data submission, and chemical registration requirements, adding administrative and timing costs to cross-border trade flows. Trade policy measures in certain major markets have additionally introduced tariff layers on specific import streams, altering landed-cost calculations and nudging procurement teams toward regional sourcing alternatives or reformulated supplier mixes.
What the Research Deliver Actually Maps
A market narrative this layered cannot be navigated with headlines alone. The full research architecture is built to translate macro trajectory into decision-grade intelligence. Readers gain access to a structured breakdown of demand by physical form, consumption by application vertical, and regional revenue distribution, all calibrated against historical baselines and forward projections. The study traces how procurement volume, price behavior, and substitution risk interact within each segment, enabling buyers and producers to isolate high-probability growth corridors rather than relying on broad averages.
Worldwide Poly Ferric Chloride (PFC) Market
Beyond segmentation, the report examines the operational and commercial levers that determine margin resilience. It maps the competitive profiles of the entities actively shaping supply, evaluates recent capacity expansions and product launches as leading indicators of market intent, and contextualizes those moves within raw material cost cycles, compliance overhead, and trade-exposed routing. The analysis also integrates regional procurement dynamics, highlighting how infrastructure spending patterns, environmental discharge mandates, and import dependency ratios feed into localized pricing behavior. For organizations evaluating supplier diversification, plant location economics, or export market entry, these layers convert raw data into execution-ready scenarios.
The deliverable is structured for practical use rather than academic recitation. It connects demand forecasting to formulation strategy, aligns regional consumption mapping with logistics planning, and grounds competitive benchmarking in observable corporate actions rather than speculative positioning. Decision-makers can use the framework to evaluate whether to lock in long-term supply agreements, where to concentrate sales coverage, which product grades warrant R&D or blending investment, and how tariff or compliance exposure might alter total cost of ownership across different sourcing routes.
Positioning for 2026 and Beyond
The next phase of PFC market development will reward participants who treat chemical procurement as a strategic function rather than a transactional line item. As water infrastructure modernization accelerates and industrial effluent standards grow more stringent, demand will continue to scale along a predictable upward path, but the distribution of that growth will be uneven, contingent, and highly sensitive to local policy and supply conditions. Organizations that embed granular market mapping into their planning cycles will be able to anticipate pricing pressure points, identify where premium-grade formulations can secure differentiated positioning, and determine which geographic corridors offer the most favorable risk-to-reward ratio for capacity or distribution investment.
This worldwide market analysis is designed to convert that complex environment into a clear decision roadmap. By aligning historical performance, forward valuation, segmentation behavior, competitive movement, and structural cost drivers into a unified framework, the research equips executives with the context needed to move from reactive procurement to proactive strategy. The full dataset, scenario mapping, and vendor-level benchmarking contained in the complete publication provide the depth required to validate assumptions, stress-test sourcing choices, and calibrate growth initiatives with precision.
Data-Driven Market Intel for 2026 Planning. The worldwide poly ferric chloride market is projected to expand steadily through 2032, underpinned by compounding demand from municipal purification, industrial effluent management, and targeted application segments. Growth is supported by a shifting balance between liquid and solid forms, diverging regional procurement intensity, and competitive repositioning among multinational incumbents and export-focused producers. Raw material cost variability, regulatory compliance requirements, and trade-policy exposure continue to shape margin structures and sourcing preferences across corridors.
For enterprises preparing 2026 procurement strategies, capacity decisions, and market-entry evaluations, the complete research offers a structured view of where value is concentrating, which segments carry the highest substitution sensitivity, and how leading players are adjusting production formats and product grades in response to demand quality shifts. The full study includes detailed segmentation pathways, regional consumption mapping, competitive profiling, and recent corporate developments that collectively convert high-level growth signals into actionable intelligence.
Polymeric Aluminum Ferric Sulfate Market
Explore the complete worldwide poly ferric chloride market report to access the full segmentation breakdowns, forward valuation tables, competitive landscape mapping, and scenario-ready procurement context needed to align your 2026 strategy with measurable market trajectory.
For detailed analysis of this topic, please visit the official page: Worldwide Poly Ferric Chloride (PFC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com