

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Barrel Compressor Market Hits $5.42B in 2025, Forecasts 4.69% CAGR to 2032

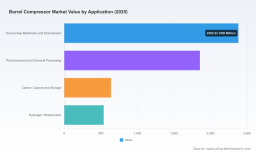
Global Barrel Compressor Market Strategic Outlook: Navigating the 2026 Industrial Landscape
The worldwide barrel compressor market stands at a critical inflection point as industrial operators balance legacy hydrocarbon demands with emerging decarbonization mandates. For senior executives, procurement leaders, and capital allocation committees, understanding the trajectory of this specialized turbomachinery segment is no longer optional; it is a fundamental component of operational resilience and long-term competitive positioning. As we move through 2026, the convergence of high-pressure process requirements, offshore expansion, and carbon management infrastructure is reshaping supply chains, pricing architectures, and technology roadmaps. This exclusive market intelligence briefing outlines the strategic landscape, highlights the operational forces at play, and demonstrates why access to granular, forward-looking analysis is indispensable for decisive corporate planning.
Market Trajectory and Macroeconomic Context
Barrel compressors have long occupied a specialized niche within the broader industrial compressor ecosystem, distinguished by their vertically split casing architecture that enables efficient maintenance, robust performance under corrosive or high-pressure conditions, and streamlined bundle extraction without disrupting connected piping infrastructure. This design preference has sustained steady demand across complex process environments, and recent performance data confirms a mature yet steadily expanding market profile. The global revenue base has demonstrated consistent year-over-year expansion, crossing the five-billion-dollar threshold and projecting sustained momentum through the end of the decade. A compound annual growth rate of approximately 4.7 percent reflects a market that is neither volatile nor stagnant, but rather shaped by methodical capacity additions, incremental efficiency upgrades, and targeted deployment in high-value applications.
While the headline trajectory provides a useful directional signal, executive decision-making requires a more nuanced understanding of how growth distributes across technology variants, end-use sectors, and regional corridors. Supply-side constraints, raw material price volatility for specialized steels and alloys, and extended lead times for casings and impellers have introduced tactical procurement considerations that ripple through capital planning cycles. Simultaneously, evolving compliance frameworks and the continued dominance of API 617 as the foundational design and testing benchmark keep engineering teams anchored to proven reliability parameters, even as a ninth edition is actively developed to address next-generation service requirements. These intersecting forces create a market environment where strategic timing, supplier relationships, and specification precision carry measurable financial consequences.
2026 Decision Drivers: CCS, Hydrogen, and Offshore Pressures
The most consequential shifts in barrel compressor demand are being catalyzed by energy transition imperatives and ultra-deep offshore development. Carbon capture and storage initiatives are transitioning from pilot-scale demonstrations to commercial megaprojects, requiring compression solutions capable of handling dense-phase and high-pressure CO2 streams over extended operational lifecycles. Hydrogen infrastructure expansion introduces its own set of metallurgical, sealing, and thermodynamic challenges, pushing manufacturers and end-users to re-evaluate material selections and stage configurations. In parallel, all-electric and electrified offshore platforms are driving demand for vertically split barrel designs that can thrive in space-constrained, maintenance-sensitive environments while minimizing operational footprint.
These application vectors do not simply add volume; they alter procurement logic. Projects targeting high-pressure process gas services demand tighter tolerances, more sophisticated multistage arrangements, and integrated skid packages that reduce field installation risk. Engineering teams are increasingly weighing single-stage barrel configurations against multi-stage architectures, balancing throughput requirements, step-down pressures, and total cost of ownership across decades of operation. Because competitive differentiation in this segment is closely tied to technical specificity and project-execution track records, decision-makers benefit from insight that goes beyond top-line sizing and into the structure of demand itself. Our research framework addresses this need by mapping functional deployment patterns, quantifying preferred architectures, and isolating the application categories where compression intensity is accelerating fastest.
MVR Compressor Market
Competitive Landscape: Strategic Positioning and Capital Allocation
The barrel compressor sector is characterized by a concentrated cohort of established turbomachinery manufacturers, each pursuing distinct commercial strategies through product specialization, service expansion, and targeted project awards. A handful of leaders command a disproportionate share of market value, creating an environment where incumbents leverage their engineering heritage, after-sales service networks, and global project references to secure complex bids. The top players maintain a strong hold on high-pressure oil and gas, petrochemical processing, and increasingly, carbon management applications, while regional dynamics continue to reward suppliers with localized manufacturing capacity, regional service hubs, and the ability to navigate local content expectations.
European and Japanese engineering houses remain central to the high-end barrel compressor segment. MAN Energy Solutions, operating under its Everllence brand, continues to advance modular and rebundling solutions for offshore, high-pressure oil and gas, and CCS deployments, with recent contract momentum reinforcing its footprint in large-scale capture projects. Baker Hughes is actively extending its barrel compressor portfolio into corrosive, high-pressure, and CO2-rich environments, including integrated packages for floating production installations where reliability and all-electric compatibility are paramount. Siemens Energy maintains a strong reputation for single-shaft vertically split centrifugal solutions engineered for extreme pressure regimes, positioning the company favorably in demanding process and upstream service conditions. On the Japanese side, Hitachi Industrial Products and Mitsubishi Heavy Industries Compressor Corporation continue to deploy extensive field references and process-gas expertise, with Mitsubishi recently strengthening its aftermarket capabilities through the acquisition of a Swiss rotating equipment maintenance specialist, a move that underscores the growing commercial importance of lifecycle service in this segment.
Beyond the established incumbents, a broader field of capable competitors expands the options available to buyers and intensifies competition for specialized contracts. Atlas Copco Gas and Process brings integrally geared and centrifugal capabilities that extend into high-pressure barrel-type applications, while Kobelco Compressors leverages its process gas heritage to address industrial and oil and gas requirements. ShenGu Group has built a distinctive reputation for very large barrel-type centrifugal units serving petrochemical reforming and hydrocracking operations, and Elliott Group remains focused on multistage barrel configurations optimized for hydrogen-rich and high-pressure process gases in refining and upstream environments. The presence of these manufacturers, combined with the project activity they are landing, signals a market where competitive intensity is rising not only on equipment price but on engineering speed, package integration, and service responsiveness.
Recent Developments Shaping Procurement Strategy
Market behavior is increasingly defined by time-sensitive project wins and capability upgrades that alter supplier positioning. Recent contract awards illustrate how barrel compressor deployments are being embedded into high-visibility decarbonization and offshore electrification initiatives. One notable engagement secured delivery of two barrel-type compressor skids for a major offshore carbon capture project in Thailand, targeting millions of tons of CO2 storage annually with offshore installation and operations commencing in the late 2020s. Another significant milestone involved the supply of barrel compressor lines for an all-electric floating production initiative in Angola, highlighting the growing intersection between electrification roadmaps and high-pressure compression requirements.
On the service and capability side, recent acquisitions and portfolio enhancements are expanding the depth of manufacturer offerings, particularly in maintenance, refurbishments, and long-term lifecycle support. These developments matter because barrel compressors are capital-intensive assets whose financial outcomes are heavily influenced by uptime, field serviceability, and the ability to execute retrofit and rebundling programs without disrupting continuous process operations. Decision-makers evaluating vendor shortlists should therefore weigh recent project references and service expansion moves alongside technical specifications, as these indicators often provide earlier signals of supply reliability and commercial stability than headline pricing alone.
Worldwide Barrel Compressor Market
Why This Research Is Essential for 2026 Planning
Corporate strategy teams require actionable intelligence that links macro market sizing with segment-level distinctions, procurement risk, and supplier positioning. The Worldwide Barrel Compressor Market study is engineered to provide exactly that level of operational clarity. Readers will find structured analysis covering historical performance through the most recent baseline year, followed by an extended forecast horizon designed to support multi-year capital planning. The report examines market size progression, growth rates, and revenue trajectories in a format built for cross-functional use, from engineering evaluation to financial modeling and procurement strategy.
Beyond aggregated sizing, the study delivers operational segmentation that enables readers to assess how barrel compressor demand distributes across technology variants, application categories, and regional markets. This structure helps teams identify where demand intensity is accumulating, which configurations are gaining preference in high-pressure or corrosive service, and how regional procurement environments differ in terms of sourcing dynamics, content expectations, and lead-time risk. The competitive landscape section profiles major manufacturers, summarizes their strategic focus, and contextualizes recent contract activity and capability moves that influence supplier selection. Additional sections address material and production considerations, standardization frameworks, and the macro forces driving adoption in carbon management, hydrogen, and offshore applications.
To protect the proprietary analytical work and preserve the depth required for high-stakes decision-making, this overview intentionally presents only the strategic framework and headline indicators. The full report contains the detailed segment breakdowns, regional market sizing, type and application splits, concentration analytics, and forward-looking scenario discussion that executives need to validate assumptions and pressure-test procurement plans.
Next Steps for Strategic Leaders
In a market where capital deployment cycles span years and project specifications increasingly intersect with environmental and efficiency mandates, timely intelligence is a decisive advantage. The 2026 planning environment calls for clarity on demand distribution, supplier competitive dynamics, and the structural shifts reshaping barrel compressor procurement across industrial and energy applications. Complete market sizing, segmentation detail, competitive intelligence, and forward forecasts are available in the full Worldwide Barrel Compressor Market research release. Access the comprehensive study to align your strategic planning with verified data, refine vendor evaluations, and strengthen capital allocation decisions across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Barrel Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com