

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Zinc L-Carnosine Hits $135.5M in 2025, CAGR 6.15% to 2032. Asia Pacific Leads at 62.08%

Unlocking Growth in the Zinc L-carnosine Market: Strategic Imperatives for 2026 and Beyond
Market Trajectory: A Decade of Structured Expansion
The global landscape for Zinc L-carnosine is entering a definitive phase of maturation, driven by converging forces in gastrointestinal therapeutics, nutraceutical demand, and regulatory evolution. As we analyze the trajectory from 2020 through 2032, the market demonstrates a clear inflection point around 2025, followed by sustained compound growth that rewards early strategic positioning. Our latest research consolidates this complex ecosystem into a actionable intelligence framework designed specifically for executive decision-makers, supply chain architects, and R&D strategists operating in 2026.
Historical data from 2020 to 2025 reveals a compound annual growth pattern that reflects both steady pharmaceutical adoption in Asia and the gradual, cautious expansion of supplement-grade supply chains in Western markets. The trajectory does not suggest a speculative bubble, but rather a structurally anchored expansion built on clinical validation, manufacturing compliance, and growing consumer awareness of mucosal health and targeted zinc delivery. By 2026, the market baseline has already shifted into a higher tier, and the forecast period through 2032 outlines a consistent upward curve that outpaces many adjacent gastrointestinal ingredient segments.
For corporate planners, this macro arc is only the starting point. A headline growth figure, while useful for boardroom context, cannot inform sourcing budgets, capacity allocation, or market-entry timelines. What separates a reactive posture from a proactive strategy is visibility into the segmentation mechanics that actually drive revenue flows, the compliance gates that determine supplier eligibility, and the geographic pricing dynamics that shape margin structures. Our report isolates these operational layers without diluting them into oversimplified aggregates, allowing leaders to align their 2026 roadmaps with realistic, data-grounded expectations.
Strategic Landscape: Where Competitive Advantage Is Actually Won
The competitive architecture of Zinc L-carnosine is defined by a concentrated group of well-positioned players, with the top five operators already commanding a majority share of industry activity. The top three alone account for a substantial fraction of commercial movement, underscoring an environment where relationship-based supply chains, regulatory filings, and differentiated quality claims weigh heavily in procurement decisions. This concentration is not a barrier to entry for disciplined newcomers, but it does signal that generic price competition alone will not secure sustainable positioning.
The competitive fabric is visibly bifurcated along manufacturing geography and regulatory lifecycle. Japanese originators and marketers continue to anchor the clinical narrative, leveraging long-standing drug approvals and extensive real-world use in peptic ulcer management. Their role as reference products in bioequivalence frameworks reinforces their influence over generic development pathways. Meanwhile, Indian and Chinese manufacturers have systematically expanded their compliance footprints, pursuing WHO-GMP alignment, US filings, and regional documentation to unlock both pharmaceutical-grade procurement and supplement-tier distribution. This dual-engine supply base provides global buyers with more sourcing flexibility, but it also demands heightened diligence around documentation consistency, purity parameters, and batch-to-batch reproducibility.
Recent operational developments illustrate how quickly the competitive dimension can shift. Activity in 2025 and 2026 has included new API documentation submissions, regional registration updates, and use of established formulations as reference standards in pharmacokinetic evaluations. At the same time, scientific commentary has expanded the conceptual perimeter of Zinc L-carnosine beyond its traditional gastric focus, prompting manufacturers and formulators to examine broader therapeutic and functional applications. These moves do not merely represent isolated company news; they reshape procurement criteria, alter competitive benchmarks, and influence how buyers evaluate long-term supplier reliability.
Segment Architecture: How Demand, Grade, and Geography Really Interact
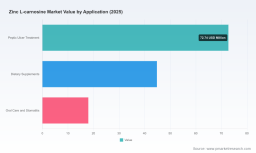
Any practical market strategy must start with an honest reading of the demand architecture. In this market, the dominant application pull originates from peptic ulcer treatment, where Zinc L-carnosine has established a durable evidence base and long-term usage history in approved territories. This therapeutic anchor creates a stable, clinically oriented demand stream that rewards suppliers with rigorous quality systems, traceable documentation, and proven consistency. At the same time, dietary supplement usage represents a significant and growing second pillar, reflecting consumer interest in gastrointestinal comfort, mucosal support, and zinc-based formulations. This segment operates under different commercial logic, where brand narrative, distribution reach, and cost-efficiency often matter as much as clinical provenance.
Zinc L-carnosine Market
A third application area, spanning oral care and stomatitis-related use, rounds out the demand profile. Though smaller in absolute scale, it matters strategically because it expands the addressable market beyond core gastroenterology and introduces additional formulation and packaging considerations. The interplay between these application streams is not simply additive; it influences production planning, inventory depth, and the value of maintaining parallel product grades for different customer segments.
On the supply side, pharmaceutical-grade material continues to represent the majority of commercial value, reflecting the importance of regulatory-grade compliance and the higher price tolerance of drug and reference-product applications. Food and supplement-grade volume forms a substantial complementary stream, where throughput, cost discipline, and flexible packaging can be equally decisive. For procurement teams, the practical question is not which segment is larger in isolation, but how the two grades interact across supply interruptions, quality audits, and cross-market distribution. The most resilient operators design their production and certification strategy with this duality in mind.
The regional distribution of activity also warrants careful interpretation. Asia Pacific remains the most substantial market geography by commercial intensity, capturing a dominant share of demand activity. North America and Europe follow as significant but structurally different markets, each with distinct regulatory pathways, end-user expectations, and channel dynamics. The rest of the world contributes a smaller yet increasingly relevant footprint as import channels expand and local distribution partnerships mature. These geographic patterns influence warehousing strategy, lead-time planning, and the relative attractiveness of serving API buyers versus finished-product formulators in each zone.
Regulatory and Operational Dynamics: The Hidden Moats of 2026
One of the most consequential themes for 2026 is the uneven regulatory status of Zinc L-carnosine across jurisdictions. In Japan, Korea, and China, the ingredient has long been approved and commercialized as an anti-ulcer drug, with generic competition active for over a decade in certain markets. In Western jurisdictions, however, the same material is largely positioned as a dietary supplement, which fundamentally alters the compliance conversation, marketing claims, and buyer expectations. This split has direct commercial implications: it affects which claims can be made, which documentation is required, and how quickly a supplier can integrate into a pharmaceutical versus supplement supply chain.
Manufacturing compliance has therefore become a primary competitive differentiator. API-grade production increasingly depends on demonstrable GMP alignment, active filings, and certifications that reduce procurement risk. Recent years have seen continued activity around major documentation submissions and regional registrations, particularly among Chinese and Indian producers targeting international buyers. These filings do not guarantee market success, but they do lower friction in qualification processes and expand the pool of suppliers eligible for higher-value contracts. In a market where active commercial status is stable and no major recalls or discontinuations are reported, the differentiator shifts from crisis management to proactive qualification and documentation strength.
Quality specifications and raw material composition are equally central. Zinc L-carnosine is a chelated complex derived from L-carnosine and zinc acetate, with defined compositional ranges for carnosine and zinc content. That specification matters because it affects downstream formulation behavior, customer validation requirements, and the perceived reliability of a supplier's technical package. As buyers comparison-shop across geographies, the ability to present clear certificates, reproducible purity, and consistent analytical documentation has become a deciding factor in supplier selection. In practice, the procurement decision is increasingly less about whether Zinc L-carnosine is available, and more about which supplier can most efficiently satisfy the documentation and quality expectations of a given channel.
L-Carnitine Market
Regulatory evolution is also introducing new long-term variables. Registration activity for novel food status in Europe and ongoing compliance work in multiple markets suggest that the commercial wall between drug and supplement use may remain intact for now, but the strategic importance of regulatory readiness is intensifying. Companies that treat compliance as a static cost center risk losing access to higher-margin procurement streams, while those that invest early in documentation, certifications, and regional registrations can convert regulatory diligence into market access.
What Our Report Delivers: Decision-Ready Intelligence
Our Zinc L-carnosine Market research is built for teams that need to move from high-level market awareness to concrete operational choices. Rather than offering a static snapshot, the report maps the market as a working system, with explicit attention to sizing logic, growth drivers, segmentation behavior, and competitive positioning. The analysis is designed to support demand forecasting, supplier evaluation, geographic expansion planning, and product-grade strategy across pharmaceutical, nutraceutical, and related formulation contexts.
Readers will find a structured breakdown of the market baseline and forward projection, anchored to historical performance and extended across the forecast window through 2032. The report integrates the major segmentation dimensions that matter for commercial planning, while preserving the analytical rigor required to evaluate relative opportunity rather than relying on broad generalizations. It also provides context on concentration patterns, so procurement and business development teams can better calibrate sourcing risk and assess how dependent the market is on a limited number of influential participants.
Beyond figures, the report translates market dynamics into operational implications. It examines how regulatory status shapes channel access, how compliance documentation influences supplier qualification, and how demand differences across applications create distinct pricing and volume behaviors. Recent developments are evaluated not as isolated news items, but as indicators of where competitive advantage is being built—through reference-product relevance, new filings, registration expansions, and scientific discussion that broadens the ingredient's perceived value proposition.
Crucially, the analysis is framed for decision latency. In a market where multiple international suppliers are actively upgrading their documentation and where application demand continues to diversify, the window to align procurement, R&D, and commercial strategy is narrowing. The report is intended to shorten the distance between market observation and execution, giving leadership teams a clearer basis for prioritizing investments, selecting partners, and anticipating structural shifts before they become obvious to the broader market.
How to Use This Intelligence in 2026
For manufacturers and API suppliers, the strategic priority is to treat compliance and documentation quality as market-access assets. In a landscape where active filings, GMP alignment, and specification clarity increasingly determine eligibility for higher-value procurement, the winners will be those who can demonstrate repeatable quality while maintaining cost efficiency. Companies that can serve pharmaceutical and supplement channels with well-differentiated product lines may capture more resilient demand than those competing solely on volume pricing.
For brand owners, formulators, and distributors, the immediate concern is supplier selection under variable regulatory conditions. Because the same ingredient can function as a drug substance in one region and a supplement component in another, purchasing teams need to evaluate not just price and availability, but the regulatory context of the destination market, the documentation packet offered, and the supplier's ability to support future registration or qualification needs. A supplier's geographic origin matters less than its demonstrated compliance depth and its alignment with your end-market requirements.
For investors and corporate strategists, the market offers a case study in how a mature specialty ingredient can still generate meaningful expansion when supported by clinical legitimacy, regulatory specialization, and diversified application demand. The concentration of activity among leading players suggests that partnership, acquisition, or exclusive supply arrangements could be more effective than unfocused competition. At the same time, the presence of active regional manufacturing bases means that sourcing diversification is achievable for buyers who know how to assess quality systems rather than brand names alone.
Looking Ahead
The next phase of the Zinc L-carnosine market will be defined less by sudden disruption than by the cumulative impact of regulatory readiness, quality differentiation, and application expansion. Demand rooted in gastrointestinal therapeutics provides stability, while supplement-grade channels and adjacent oral-care applications add growth optionality. Suppliers and buyers who understand how these forces interact will be better positioned to navigate pricing, qualification, and geographic expansion with confidence.
This report is designed to give you that understanding at a strategic level while preserving the detail needed for execution. The full analysis contains the segmentation breakdowns, competitive profiles, development timelines, and regional dynamics that underpin the market outlook. For teams planning 2026 sourcing, product development, or market-entry moves, the complete dataset provides the evidence base required to move from intuition to informed commitment.
For detailed analysis of this topic, please visit the official page: Zinc L-carnosine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com